How the housing industry is preparing for the age of AI

How the housing industry is preparing for the age of AI

Synthetic intelligence (AI) and device understanding (ML) existing extraordinary options to expand homeownership and housing in the U.S. But for opportunity homebuyers to benefit from new know-how, the market should figure out a way to keep bias out of selection-generating styles, experts explained Monday.

“The most important possibility in my thoughts in the close to to medium phrase stays [finding] methods to take unstructured info and leveraging that and turning it into machine readable device facts,” stated Steve Holden, senior vice president of one-family members analytics & modeling at Fannie Mae.

Holden spoke on the subject matter of leveraging information science and option facts to raise accessibility to homeownership at Property finance loan Bankers Association’s (MBA’s) Technologies Remedies Convention & Expo at San Jose, California on Monday. 

Fannie Mae’s concentrate on incorporating machine understanding is to get a rich profile of consumers’ threat and use that to examine the suitability for achievement in homeownership.

In distinct, Holden mentioned the prospect of teaching laptop or computer algorithms to overview bank statements and determining borrowers who have no credit rating but are producing dependable lease payments each month.

“We really should think about that (reliable rent payments) in their (borrowers’) analysis of hazard (…) If you’re a renter, none of these payments are regarded as. So this thought that you can go to the financial institution assertion and extract that details and leverage it from the conclusion-making is a actually effective and essential innovation to access specified sectors of the populace,” Holden said.

Rocket Businesses is focused on making use of know-how to faucet into a prospective purchaser base. 

Brian Stucky, direct for Rocket Ethical AI at Rocket Central, noted the fast escalating Hispanic homeownership fee. By 2040, 70{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} of new owners will be Latino but several could be denied a house loan since of their high financial debt-to-earnings levels.

“If Hispanics are falling out a good deal of the time for the reason that of the DTI, what does that necessarily mean?(…) What is a portion of that that we can probably look at to make a small little bit improved because in the end it is going to be growing underwriting in some trend to consist of these features that may support us determine clientele that are getting turned down now but are very likely heading to be good credit score risks for us,” Stucky claimed.

From the housing offer side, machine discovering designs could assist deal with bias in the collateral valuation process, Peter Carroll, govt of community policy & market relations at CoreLogic, said.

“I’ve viewed full building tasks at their infancy phase (…) stopped dead in their tracks simply because there is a perception that there are not likely to be any product sales comparable houses in the community and therefore there won’t be any home finance loan financing, which is their (builders’) takeout and for that reason there is no point executing the venture,” Carroll mentioned.

The united states faces an undersupply of housing of 1.1 million units and rising with respect to solitary-family members household one- to 4- device entry stage households, in accordance to CoreLogic.

There is a incredible urge for food from states, housing finance organizations, regional subsidy divisions of metropolitan areas and counties and zoning divisions to interact in this dialogue, Caroll reported, noting the options of technology in regards to addressing small housing provide.

The housing industry will have to have to figure out how to integrate synthetic intelligence and equipment discovering although holding bias from creeping into the small business conclusion-earning product, he claimed.

“You’ve likely read machine discovering referred to as a black box, it is tricky to glimpse at and recognize why a choice was rendered from the inputs that it was offered. That is a thing that will have to be conquer in advance of we have wholesale adoption and use across the sector,” Stucky stated. 

Detailing the reasoning driving choices coming out of the designs will be vital in a closely regulated marketplace like housing, Holden explained.

“One of the items we assume about a ton is when we’re obtaining conclusions coming out of the products or examination coming out of the versions, conveying what those outcomes are and what they indicate and how they are acquiring created. That becomes a great deal a lot more complicated as you start out to lean much more seriously on equipment learning and AI-form methodologies,” Holden stated. 

2023 Q2 Housing Market Trends: What To Expect

2023 Q2 Housing Market Trends: What To Expect

The first three months of 2023 are in the guides, and the quarter generated issue between actual estate gurus. Understandably so, given the mix of rising mortgage curiosity premiums, declining property gross sales and ongoing stock and affordability difficulties.

But what do April, May and June have in retail store for home sellers, customers and other players in the housing sector? We questioned sector insiders to establish housing tendencies and forecasts for the next quarter of the year. Browse on for their insights.

Q2 2023 will differ from usual second quarters

Typically, the next quarter is the most energetic three-thirty day period cycle of the calendar year for listings, consumer interest and house sales, claims Nadia Evangelou, senior economist and director of serious estate analysis for the National Association of Realtors. “Two of the busiest promoting months are Could and June, with June typically the peak month of the year,” she suggests.

But this 12 months appears to be various. Selma Hepp, chief economist for CoreLogic, expects an uncommon spring year due to fresh new problems above lender failures, as well as the inclination for individuals to sit items out in situations of ambiguity. “In typical, the financial outlook is progressively far more unsure,” she states. “Recent developments in the monetary market, blended with the Federal Reserve’s persistence in slowing inflation raises, raises the likelihood of a economic downturn going on sooner, which would lead to increasing unemployment and slower cash flow development. That would weigh on buyer shelling out — and housing affordability — in the next quarter.”

Dennis Shirshikov, a strategist for true estate web site Awning, agrees that Q2 2023’s housing local weather appears to be cloudy. “With ongoing money cloudiness, it’s difficult to predict how the economy and housing industry will accomplish,” he states. “If there is swift motion to decrease fiscal and banking uncertainty, loan providers may be much more open up to originating home finance loan financial loans and there could be a superior pickup in action — specially if mortgage charges are reduced.”

The climb back to normalcy won’t transpire all at the moment, predicts household-banking lawyer Scott Krinsky, a associate with the Romer Debbas legislation organization in New York Town. “The most telling indicator we’ve witnessed so far is that every single time property finance loan prices have dropped, we have subsequently viewed an increase in exercise from potential buyers who experienced been ready patiently on the sidelines,” he states. “The hope is that we’ve by now noticed rock bottom in phrases of over-all current market exercise.”

Q2 home finance loan level projections

Where do the professionals foresee mortgage loan costs across the next quarter? The consensus is that they will most likely hover in close proximity to latest degrees — unlucky news for these hoping to see a significant lower.

“I visualize home finance loan costs for the 30-yr set-price property personal loan to normal 7. p.c, as opposed to 6. {1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} for the 15-12 months fixed-fee home loan personal loan,” suggests Albert Lord, founder and CEO of Lexerd Funds Management in Summit, New Jersey.

Rick Sharga, founder and CEO of market-intelligence company CJ Patrick Enterprise, thinks rates will seesaw involving 6.5 and 7. per cent for 30-yr loans, as opposed to 5.75 to 6.25 {1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} for 15-calendar year loans. “But if inflation proceeds to decrease and the Federal Reserve stops raising rates, we could see house loan rates start to reverse training course by the close of the quarter, settling into the 6. p.c range,” he suggests.

Factors other than the Fed could influence Q2 prices as very well. If rising worry in the banking sector persists, states Evangelou, “mortgage fees will probably drop quicker than expected. I see the ordinary charge on a 30-year fastened property finance loan to be all-around 6.2 p.c this quarter.”

Wherever residence prices and stock are heading

If charges continue being superior and purchaser enthusiasm wanes, several anticipate home costs softening as the yr progresses. Even so, residence affordability continues to be significantly out of arrive at for a massive variety of prospective buyers, and that pattern isn’t most likely to transform in the 2nd quarter.

“While I really do not think we will see the ridiculous skyrocketing selling prices that 2021 and early 2022 introduced, the shortage of households for sale is possessing a enormous impact, triggering charges to remain higher,” states Ralph DiBugnara, president of Property Certified and SVP of Cardinal Economical. “Prices will stay that way for the remainder of 2023.”

“The blend of history high selling prices and greater curiosity costs has decimated affordability for several would-be customers, in particular first-time purchasers who never have fairness to tap into for big down payments,” says Sharga.

Contemplate that the source of residences for sale continues to be at about fifty percent of what would stand for a well balanced, “healthy” industry. “Inventory figures are higher than they were a yr ago, but new listings are really lessen,” Sharga proceeds. “That suggests stock is raising only for the reason that it is using more time to promote houses once they are listed — fewer new listings are coming to current market.”

Unless of course charges consider a tumble this quarter, never anticipate resale listings to enhance anytime before long, both. “Homeowners with a sub-4 per cent mortgage bank loan, which signifies about 70 p.c of debtors, aren’t in a hurry to promote their property and acquire on a new property finance loan with a fee shut to 7 {1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b},” Sharga suggests. “I think several customers in the 2nd quarter will simply wait around for current market circumstances to increase.”

Procedures for homebuyers and sellers

With the Q2 current market on the lookout uncertain, ought to you buy a residence now or hold out? Many experts counsel that prospective buyers in a protected economical place, with occupation steadiness, should pull the trigger quickly on a residence purchase. That is for the reason that the mix of charges, rates and stock may not trend strongly in their favor in the small term.

“If you can find a residence you appreciate and can pay for at today’s selling prices, really do not wait around,” states Sharga. “Home rates in most of the region are unlikely to crash, and property finance loan charges will only occur down quite gradually if they decrease at all this calendar year.”

Krinsky advises those people on the lookout to get in spring or summertime to “keep diligent by staying related with your actual estate broker and loan officer. By checking the developments, you can achieve a stronger feeling of comfort and ease and assurance when you make your mind up the time is right to purchase.”

What about individuals looking to sell their dwelling in Q2? Spring is traditionally the ideal time to sell, immediately after all, and while this spring may well be atypical, you could even now check out to acquire edge of greater purchaser website traffic. “Home income are envisioned to increase by 5 percentage details in the next quarter,” states Evangelou.

“Don’t wait to list your dwelling in the hopes of acquiring an extra 5 percent on your invest in rate,” claims Shirshikov. “You may possibly pass up the wave of spring purchasers and ultimately stop up with a residence on the market place for numerous months.”

On the other hand, if you aren’t in a rush to relocate, it could make feeling to pause in the hopes that market problems get well. “The marketing climate ought to enhance in the 2nd 50 {1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} of 2023 and all over again in 2024, so endurance is referred to as for,” Sharga suggests. “If you do have to have to promote your house faster, be sensible with your record price. Listing a home with an unrealistic asking rate will probably final result in multiple selling price reductions.”

Cavco Industries: Meeting The Evolving Needs Of The Housing Industry (NASDAQ:CVCO)

Cavco Industries: Meeting The Evolving Needs Of The Housing Industry (NASDAQ:CVCO)
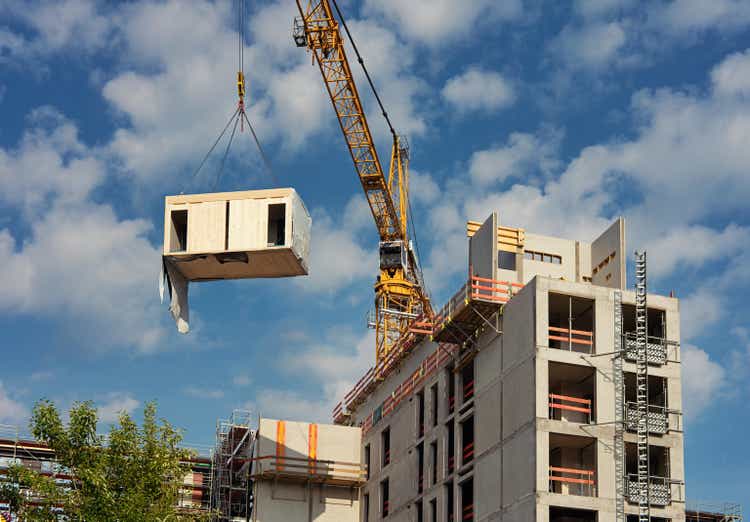
Crane lifting a wooden building module to its position in the structure.

JARAMA/iStock via Getty Illustrations or photos

Thesis

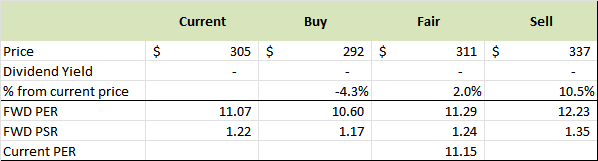
Cavco Industries Inc. (NASDAQ: CVCO) is a major firm with fantastic keep track of file of profits and earnings growth. The corporation has reached organic expansion as a result of improving current operational performance and pursued strategic investments and acquisitions to expand their producing

After banking crisis, the housing market faces even more uncertainty

After banking crisis, the housing market faces even more uncertainty

New info from the National Affiliation of Realtors confirmed a 14.5{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} raise in household gross sales in February, a big increase relative to anticipations.

Current residence product sales have gone down continually each individual thirty day period for an full calendar year now. Stock has also been at historic lows. Even though today’s facts might be good information for the market, it comes versus a clean backdrop of financial institution collapse and standard recession stress.

Robert Padilla and his wife Patricia have been on the lookout for a house to get in Santa Fe, New Mexico, for about a calendar year.

“It’s just the two of us, but we have family that we’d like they arrive down to visit us,” Padilla mentioned. “So we needed a a few bed room, two bathtub.”

But there hasn’t been much to seem at in their cost vary — which is about $350,000. Padilla is effective as a stability guard for general public educational institutions. The properties they’ve observed have been disappointing.

“The roofs are leaking,” he claimed. “They’ve experienced animals dwelling in there. chickens. I necessarily mean we just cannot do that.”

If home loan rates had been lower, Padilla states they’d be equipped to glimpse at nicer residences. Rates have appear down from their substantial of a lot more than 7{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} past November. But with premiums about 6.5{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b}, getting is out of get to for many residence buyers.

It is all a little bit of a unfavorable suggestions loop amongst buyers and sellers, claims Selma Hepp, main economist at CoreLogic.

“Both sides assume it is a negative time to acquire and it is a negative time to market,” Hepp said. “And so both of those are sitting down on the sidelines.”

According to her, this trend has been worsening. “Both attribute it to better mortgage loan charges,” Hepp explained.

And now there’s the uncertainty of a banking disaster to element in. “A whole lot of the expectation is that home finance loan charges may perhaps once more go up, and that we will see a tightening of lending ailments,” she claimed.

Hepp also details to shopper sentiment staying minimal as an obstacle. Logan Mohtashami, a guide analyst for HousingWire, agrees.

“A pal of mine that performs in the lending sector, explained to me that a homebuyer just took all the funds out of out of their financial institution, because they had been fearful that the bank was gonna go underneath,” Mohtashami said. “They said, ‘We never want to even acquire a home, we just really don’t want to shed our cash.’”

But Mohtashami and other analysts do see a flicker of hope for the housing market heading ahead.

“Rates may perhaps lower even more in the coming months dependent on reactions to the money market place,” stated Nadia Evangelou, a senior economist for the National Affiliation of Realtors, the team that releases the month-to-month property sales stories.

Evangelou stated she is cautiously optimistic mainly because contract signings rose noticeably for the 2nd straight month and which is a fantastic indicator for home revenue. But like quite a few analysts and would-be household customers and sellers — she’s keeping her breath for the federal reserve’s up coming shift.

There is a great deal happening in the entire world.  Via it all, Marketplace is right here for you. 

You rely on Marketplace to crack down the world’s functions and convey to you how it influences you in a truth-primarily based, approachable way. We rely on your money guidance to continue to keep making that attainable. 

Your donation nowadays powers the independent journalism that you rely on. For just $5/thirty day period, you can enable maintain Market so we can hold reporting on the issues that make any difference to you.  

Housing market gets boost as home sales see highest spike since 2020

Housing market gets boost as home sales see highest spike since 2020

White House prepares new tenant protections, alarming housing industry

White House prepares new tenant protections, alarming housing industry

The field is bracing for “some pretty rigorous regulation,” stated Jerry Howard, CEO of the National Association of Property Builders, whose customers incorporate landlords. “They want to be very careful about what they’re performing,” claimed Howard, who was a person of a handful of market associates at a November White Dwelling conference on tenant protections. “There’s a genuine possibility of generating a difficulty that doesn’t exist.”

With a feasible recession looming, the Biden administration will be wanting for techniques to offer reduction to income-strapped Americans suffering from a higher charge of living. Considering that the U.S. House is now underneath Republican regulate, the sort of sweeping financial legislation enacted in the course of the last two decades is off the table.

Democratic lawmakers together with Sen. Elizabeth Warren (D-Mass.), are leaning on the administration to go large by curbing rent boosts at millions of units in attributes with authorities-backed home loans – a long-shot go the White Property is not severely weighing, in accordance to a individual with know-how of the conversations.

“People just can’t pay for to reside,” explained Rep. Jamaal Bowman (D-N.Y.), who spearheaded a letter final 7 days with Warren calling on President Joe Biden to concern an executive action limiting rent hikes in properties backed by the Division of Housing and City Advancement or Fannie Mae and Freddie Mac, the federal government-controlled house loan financiers. “We want to force the president as considerably as feasible to lighten the stress of lease on day-to-day people today.”

Democrats want the administration to enact new limitations on hire hikes and punish landlords they accuse of price-gouging — “not just concepts, not just tips, but what can the president do through government action to lighten the burden on folks and place a lot more dollars in their pockets,” Bowman explained in an job interview.

The White Home declined to comment on the particulars of likely new regulations, pointing to a statement it introduced previous week in reaction to the letter from Democrats.

“We are exploring a wide established of administrative actions that even further our dedication to guaranteeing a truthful and reasonably priced market for renters across the country,” spokesperson Robyn Patterson said. “We appear forward to continuing to do the job with lawmakers to reinforce tenant protections and strengthen rental affordability.”

Though lease is continue to driving up over-all inflation — thanks in portion to a information lag in the official inflation gauge — the national median rent has fallen for 4 straight months, according to the most up-to-date info from Apartment List. New lease need plummeted in the second 50 {1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} of 2022, when the web desire for residences fell into detrimental territory for the to start with time due to the fact 2009, in accordance to an assessment by RealPage Marketplace Analytics.

“Complicating this method isn’t excellent at any time in the industry cycle,” said Greg Brown, senior vice president of government affairs at the Nationwide Condominium Affiliation. “But we’re in the fourth straight thirty day period of hire declines. I believe issues are adjusting once more, so it does increase the issue, are they responding to a situation of 3 to four months back, not what is presently happening or will be going on in the in close proximity to long run?”

The association and 10 other marketplace groups urged Biden to resist stress to lay new federal needs on prime of current laws and said that executing so would “further exacerbate affordability worries,” in a letter past month.

Even as demand from customers eases, the market place is about to see a surge in offer – portending further price cuts. A lot more condominium models are at the moment beneath design than at any place considering that 1970.

“A good deal of rental provide is going to be finishing in 2023 — we’re likely to see extra completions than we have in 40-furthermore decades,” said Jay Parsons, chief economist at RealPage, a home administration software provider. “The stability of power genuinely has shifted toward renters — they’re likely to have extra options, more aggressive pricing and greater discounts.”

Bowman and tenant advocates argue that modest declines in rents – the countrywide median fell .8 p.c in December – hardly make a dent in tenants’ expenses following the eye-popping gains of the previous couple of years.

Even right after falling from its July peak, the median inquiring selling price in November was however 20.9 percent increased than it was at the same time in 2019, prior to the pandemic struck, according to the hottest month to month rent report from Real estate agent.com. About 53 p.c of tenants said their lease had greater by more than $100 for each month above the final year, in accordance to the most up-to-date Family Pulse study by the Census Bureau.

Hire was escalating even prior to Covid, Bowman mentioned, adding that a lot of of his constituents commit about fifty percent their profits on housing.

“The cooling result in the marketplace isn’t meaningfully switching situations for tenants,” claimed Tara Raghuveer, director of the Properties Warranty campaign at People’s Action. Raghuveer also attended the November White House meeting.

“The lease is nonetheless too damn high,” she reported.