The 2022 housing market: A tale of two halves

The 2022 housing market: A tale of two halves

Marty Inexperienced thinks of the housing sector in 2022 as two extremely diverse motion pictures. The 1st fifty percent of the year, with home finance loan rates in the 3s and 4s, was like “Fast and Furious.” Houses were offering at a fever pitch in a make any difference of days, with numerous features, waived contingencies and potential buyers paying out $100,000(!) more than asking selling price. Large octane things.

But the housing marketplace in the 2nd half of 2022? “The Major Chill” or “Frozen,” states Green, principal at actual estate regulation company Polunsky Beitel Inexperienced. The selection of dwelling listings dried up, contracts ended up canceled, the number of purchasers even now out there demanded concessions, home loan fees spiked to 7{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} and homebuilder sentiment strike rock base.

By September, a full-fledged housing sector recession experienced established in.

“The 2002 housing marketplace has been a tale of two halves,” said Inexperienced.

And, the marketplace appears to be like probably to continue to be frozen nicely into 2023, specialists instructed HousingWire.

A house loan price lockdown freezes the housing market place

Homeowners who refinanced during the pandemic simply just aren’t heading everywhere, according to Nick Smith, controlling husband or wife and CEO at Rice Park Funds Administration.

“They are not marketing and have a good deal of equity in their homes. The better house loan premiums are also placing a wet blanket on desire for new housing,” he stated.

Many thanks to the Federal Reserve’s benchmark rate staying around zero for two full years and producing file-low property finance loan costs, a small minority of home owners now have an incentive to refinance at all in 2023. The elevated property finance loan rate atmosphere has designed a home finance loan rate lockdown impact of types, restricting the pool of prospects for the home loan sector.

With households taking longer to sell, owing in element to greater house loan charges, consumers in 2022 had negotiating energy to get concessions or credits to lower rates down for a constrained time period. People trends are likely to proceed in 2023.

Momentary rate buydowns have turn out to be a preferred concession, primarily between homebuilders, in which just one out of 10 loans aspect a vendor-paid buydown, said Peter Idziak, senior affiliate at Polunsky Beitel Inexperienced. Adjustable-price mortgages are also in vogue, enabling purchasers to partially overcome historically undesirable house affordability.

Owners in 2022 also tapped into their residence fairness, which peaked at $11.5 trillion in the second quarter of 2022, capitalizing on residence fairness loans and dwelling fairness line of credit history (HELOC). In the 3rd quarter of 2022 by yourself, HELOC and dwelling fairness bank loan originations rose 47{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} and 43{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} yr more than yr respectively, according to Transunion‘s newest offered information. 

With credit card debt amounts growing and a recession looming, it is effortless to see far more people today turning to the equity in their homes to pay out down credit rating cards or make up for a liquidity shortfall prompted by job loss.

“With the economics of cash-out refinance worsening amidst better prices, house owners are showing increased willingness to use property fairness strains of credit score (HELOC) and dwelling equity loans to tap equity,” a Housing Finance Policy Center report states.

Layoffs, LOs leaving the marketplace for good 

The mortgage loan business shrinking by more than 50 {1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} to an estimated $1.7 trillion in 2022 from 2021 intended home loan creditors have had to cut expenses – mostly through layoffs.

Leading 10 lenders, which include Wells Fargo, Pennymac, Assured Charge and loanDepot, have gone by various layoffs all over the 12 months, and smaller sized regional loan companies, which aimed to develop by concentrating on the order market place, were being strike just as really hard, if not more durable. 

Other smaller sized creditors, which include genuine estate tech startup Reali and Sprout House loan, shuttered, although Very first Guaranty Home finance loan Corp filed for Chapter 11 individual bankruptcy. Some scaled-down gamers, which include Inlanta Mortgage, which ended up employing LOs and department managers in the summer months, abruptly announced to shut down before this thirty day period, citing an “unanticipated drop in property finance loan product or service desire.”

The leading mortgage originators, who exceeded the landmark $1 billion in origination quantity in every of the earlier two years, weren’t immune to soaring premiums either. Shant Banosian, govt vice president of income at Assured Level, laid off about 50{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} of his group, and Thuan Nguyen, CEO of Financial loan Manufacturing facility, lowered his corporation sizing by fifty percent this 12 months. 

The top rated producing LOs who focused on order home loans had been positioned in a improved spot than these whose business depended on refis. Banosian, whose financial loan origination volume will be close to $1 billion in 2022, mentioned he turned housing industry headwinds into an prospect to focus on new geographic marketplaces. 

With a huge increase in distant work and his core group of customers purchasing households across the state – no matter if it be family vacation residences, a lot more reasonably priced areas, or for new function chances – Banosian was at danger of shedding purchasers when they went to states his workforce was not functioning in. 

“As they (current shoppers) went to do organization in these new states, we figured out where by the true estate agents are, and who the players are, where by the marketplaces they are buying and did some study and began producing cellular phone phone calls,” he said in an job interview with HousingWire. 

The LOs who are in it for the long haul have absent old school: meeting up with actual estate brokers, having licenses in various states and utilizing social media to get their names out. These who joined all through the refi boom or did not develop referral interactions have completely exited the business. Or will quickly.

Loan officer headcount in the marketplace could drop by 45{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} from final year’s approximated 353,120 LOs nationwide, which expanded by 34{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} from 2019, according to projections from Stratmor Team.

If the industry encounters a 65{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} fall in origination quantity from the peak in the fourth quarter of 2020 to a trough in the 1st quarter of 2023, the Mortgage Bankers Association initiatives output employment will possible need to be scaled back again by 24 to 31{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b}.

“We are also heading into the seasonally lessen wintertime months, so we really should anticipate reduced volumes to keep on at the very least for the following two quarters,” claimed Shampa Bhattacharya, director for U.S. non-Lender money establishments at Fitch Scores.

“Everybody is going to have a black eye right here. It’s not a deficiency of motivation for financial loans, the financial loans don’t exist,” Brian Hale, founder and CEO at Property finance loan Advisory Companions, explained.

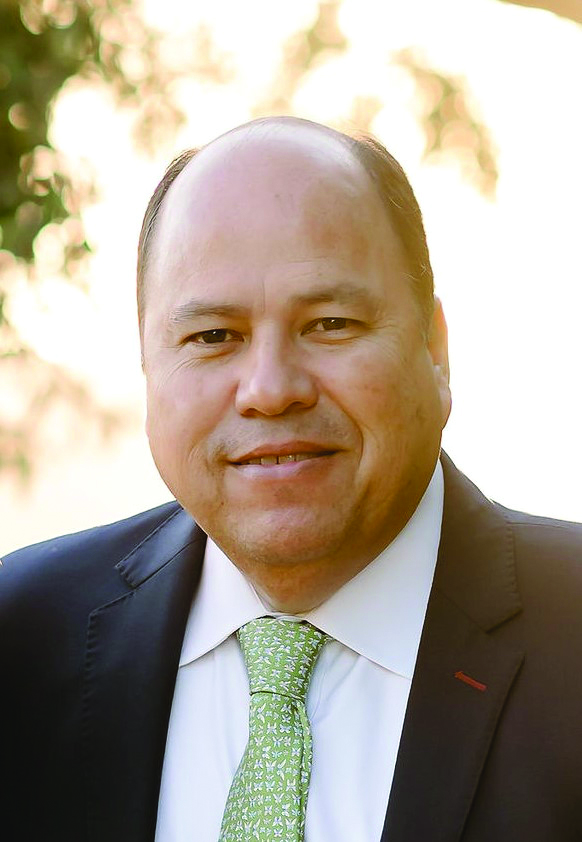
An inside look at the latest trends in housing regulation and policy, featuring the 2022 Vanguard Honoree, Armando Falcon

An inside look at the latest trends in housing regulation and policy, featuring the 2022 Vanguard Honoree, Armando Falcon

In this series of interviews, we focus on the men and women who are shaping the point out of housing at the major — the policy and regulation specialists. The FHFA and the GSEs are critical to painting the picture of today’s housing marketplace and marketplace tendencies. To help get rid of some gentle in this location, many of the 2022 HousingWire Vanguard honorees shared their insights on what’s happening at the federal amount that’s heading to have an affect on housing this 12 months and into 2023.

Armando Falcon, CEO at Falcon Capitol Advisors

Falcon_Armando-Regulation
Armando Falcon, CEO at Falcon Capitol Advisors

HousingWire: Which traits in housing regulation are you and your group most centered on as we move into 2023?

Armando Falcon: Hunting ahead to 2023, there are a couple of wide trends that we are focusing on. The to start with is the total enterprise transformation that is taking spot in the home finance loan field. This is the outcome of several forces: the Fed’s anti-inflation coverage the immediate deceleration in lending that’s resulted in a 40{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} fall in apps the growing cost of house loan generation, which has now damaged the $10,000 for every loan threshold and the continued push in direction of digitization in mortgage loan lending.

These are prime of intellect for my workforce, our purchasers and the sector. The second wide development is accessibility to homeownership and affordability. Dwelling rates have in no way been increased, pent-up desire stronger and housing stock tighter. These ailments are hard for even the average homebuyer, permit on your own minimal-earnings and minority consumers.

There is a increasing sentiment in the two the community and private sectors that more requirements to be completed to help people, specially underserved buyers, get ready for homeownership and to shut the affordability gap. We’re observing new power and new initiatives in this area at numerous house loan and housing businesses.

Similarly, massive lenders are expanding their ESG and social responsibility applications. The dedication is genuine, and we see it only acquiring much better.

HW: As a 2022 Vanguard honoree, what has been your proudest accomplishment?

AF: Is it alright to say that I am proud of building a consulting firm designed of some incredibly talented folks who are supporting the mortgage loan market adapt to a current market in changeover? That I’m proud of the part that they are playing in supporting modernize property finance loan generation and the secondary marketplace? Mainly because I am.

About the earlier 15 yrs, our team has developed to more than 50-moreover associates, several of whom have held management positions at leading loan companies, tech and details companies and mortgage loan companies.

It’s really hard to decide just a person project because we’ve had many interesting engagements recently: for instance, our do the job with Ginnie Mae on its Digital Collateral Method or the asset income program that we handle for HUD that has moved a lot more than 50{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} of these vacant homes to nonprofit companies for reasonably priced housing or the analytic get the job done we offer to the business individuals to enable them evaluate development on their ESG investments.

These engagements are assisting to make the property finance loan business far more productive and far more resilient, two objectives that I pursued as a regulator and carry on to emphasis on as a guide to the business.

HW: What major adjustments in federal regulation and legislative guidelines need to people be paying out extra interest to?

AF: As I talked about, there is a large amount of desire and momentum about the regulation of issues of affordability and inclusion in homeownership. It is a priority at FHFA, FHA, HUD and Ginnie Mae. These organizations are making an attempt to occur up with creative options to make housing more inexpensive and homeownership additional achievable.

There is practically a New Offer spirit at perform. We’re also seeing new marketplace-primarily based initiatives coming from the personal sector. 1 of the nation’s largest loan companies, for instance, has just announced that it is tests a new plan that will give zero-down payment mortgages with no closing expenditures to very first-time homebuyers in Black and Hispanic neighborhoods in five big towns.

HW: How has your knowledge as the director of OFHEO (now FHFA) affected your initiatives and management at Falcon Capital?

AF: The GSEs and Ginnie Mae have been evangelical in their aid of digital lending. Nowadays approximately 5{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} of all conforming home loans are eNotes, and all of the companies are on record encouraging loan providers to originate extra property digitally. Ginnie Mae has been accepting eNotes on a pilot foundation given that the beginning of the calendar year. In June, they expanded their Digital Collateral System, and they are now in the system of accepting new applications from eIssuers, eCustodians, and subservicers. This was an vital milestone in digitizing govt lending, which was roughly a $757 billion sector.

HW: Falcon Money often works with govt agencies in system management and regulation method. Is there one particular task or partnership that you are very pleased of in specific?

AF: Creditors see the value in offering their shoppers the similar variety of easy digital expertise that they come upon in other features of their life (e.g., banking, purchasing, transportation). They are also concerned that if they really don’t offer this experience, more substantial countrywide retail lenders will. This is why I think these initiatives will proceed even in the smaller, much more aggressive environment that the market is now facing.

Making electronic, somewhat than paper, assets offers increased cash industry efficiencies and lessens prices and mistakes. Latest ROI reports have revealed that eClosings and eNotes can help save originators roughly $400 per loan. That’s a major variety when you take into consideration that the ordinary originator misplaced $82 for every loan in the 2nd quarter, in accordance to the Mortgage Bankers Association.

This interview was at first posted in the Oct/November difficulty of HousingWire Journal. To perspective the whole concern, click here.

2022 marked the end of cheap mortgages and now the housing market has turned icy cold : NPR

2022 marked the end of cheap mortgages and now the housing market has turned icy cold : NPR

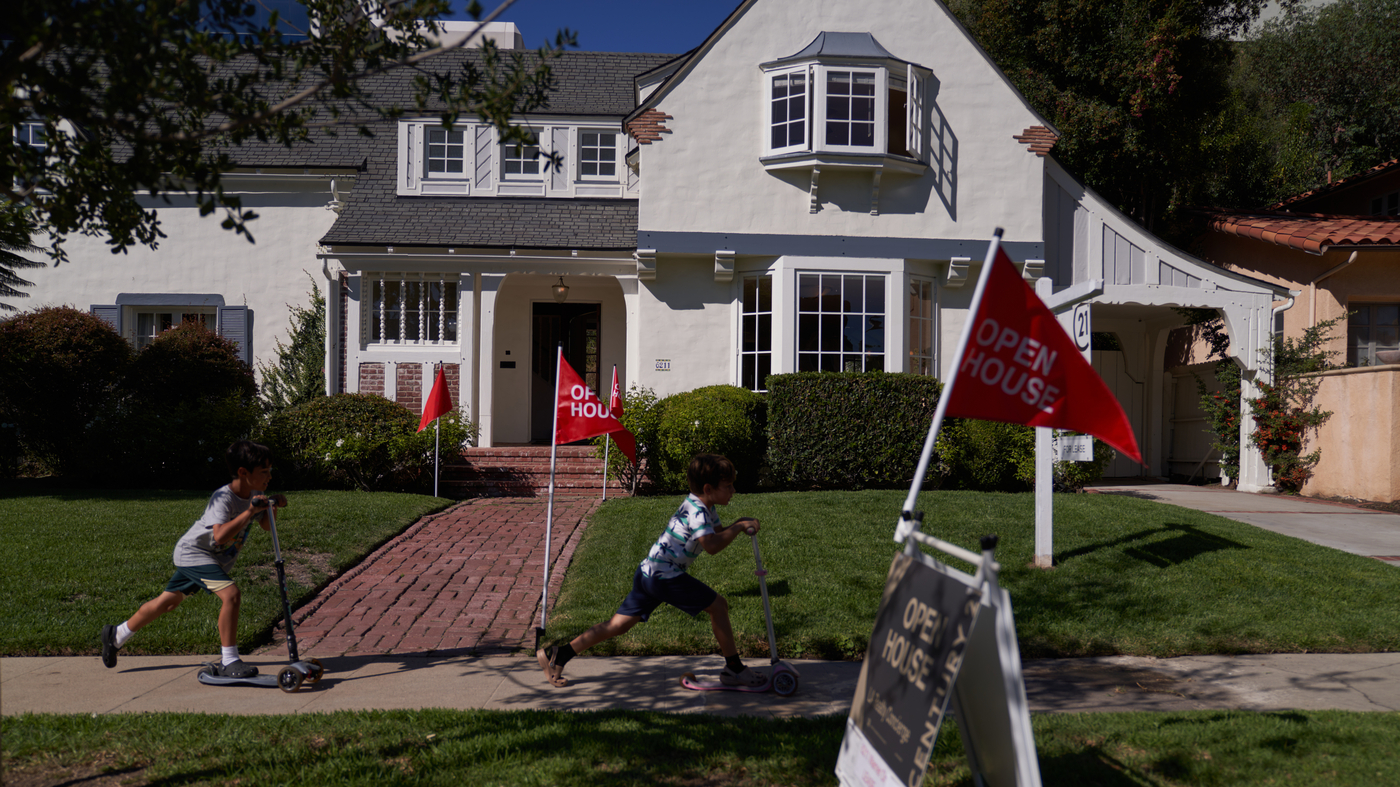
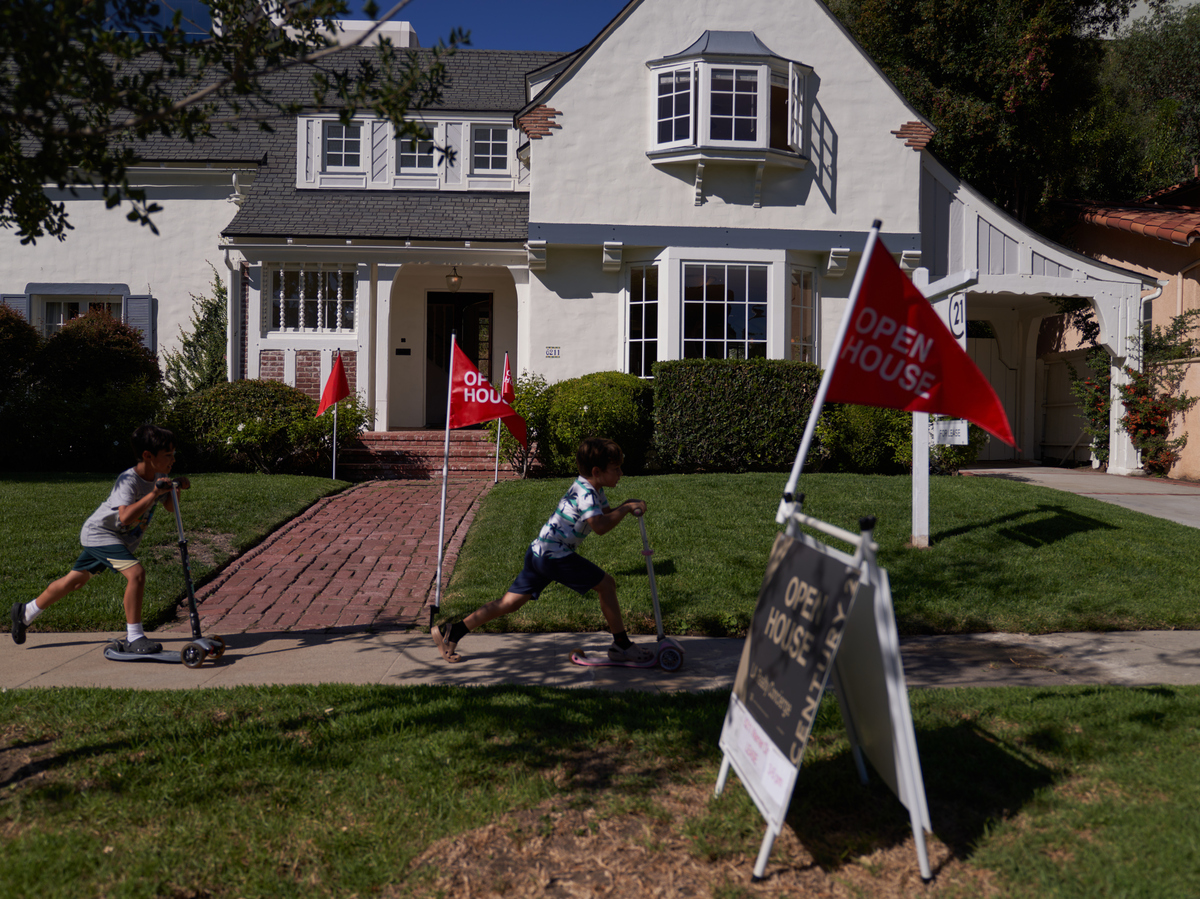
Small children ride scooters past a property for sale in Los Angeles. Dwelling product sales have slowed as mortgage loan charges have climbed.

Allison Evening meal/Getty Photos


disguise caption

toggle caption

Allison Supper/Getty Pictures


Children trip scooters previous a home for sale in Los Angeles. Household profits have slowed as mortgage loan charges have climbed.

Allison Dinner/Getty Pictures

Evan Paul and his spouse entered 2022 thinking it would be the 12 months they would eventually buy a household.

The couple — each experts in the biotech market — were being completely ready to put roots down in Boston.

“We just form of acquired to that position in our lives where we have been fiscally pretty secure, we wished to start off owning kids and we needed to just form of settle down,” suggests Paul, 34.

This yr did convey them a child lady, but that household they dreamed of never materialized.

Large dwelling selling prices have been the preliminary insurmountable hurdle. When the Pauls to start with started off their research, small interest costs at the time experienced unleashed a getting frenzy in Boston, and they had been relentlessly outbid.

“There’d be, you know, two dozen other delivers and they’d all be $100,000 more than inquiring,” states Paul. “Any any time we experimented with to wait around right until the weekend for an open residence, it was long gone prior to we could even glimpse at it.”

Then arrived the Fed’s persistent interest fees hikes. Soon after a handful of months, with home finance loan fees climbing, the Pauls could no lengthier afford to pay for the properties they’d been seeking at.

“At first, we started out reducing our anticipations, seeking for even more compact residences and even fewer perfect spots,” says Paul, who eventually recognized that the superior home loan fees were being pricing his spouse and children out all over again.

“The stress and anxiety just caught up to me and we just made a decision to contact it quits and keep off.”

Purchasers and sellers set plans on ice

The sharp raise in house loan charges has solid a chill on the housing industry. Numerous prospective buyers have paused their search they can for a longer period manage dwelling costs they have been considering a year in the past. Sellers are also cautious of listing their homes mainly because of the higher home finance loan prices that would loom above their subsequent buy.

“People today are trapped,” suggests Lawrence Yun, chief economist with the Countrywide Affiliation of Realtors.

Yun and other people explain the market place as frozen, one in which residence revenue activity has declined for 10 months straight, in accordance to NAR. It truly is the longest streak of declines because the team started out monitoring profits in the late 1990s.

“The sellers aren’t placing their properties on the marketplace and the purchasers that are out there, certainly the electric power of their greenback has modified with soaring fascination fees, so there is a little little bit of a standoff,” says Susan Horowitz, a New Jersey-dependent genuine estate agent.

Apparently, the standoff has not experienced a great deal impression on charges.

Property price ranges have remained largely higher inspite of the slump in revenue activity since stock has remained low. The inventory of unsold current households fell for a fourth consecutive thirty day period in November to 1.14 million.

“Anything at all that will come on the sector is the 1 salmon operating up stream and each bear has just woken up from hibernation,” states Horowitz.

But even that craze is starting to crack in some markets.

At an open up home for a charming starter property in Hollywood a single modern weekend, agent Elijah Shin failed to see lots of folks swing via like he did a calendar year in the past.

“A yr in the past, this in all probability would’ve now offered,” he claims. “This house will sell, way too. It’s just heading to just take a minimal little bit more time.”

Or a great deal for a longer period.

The cottage 1st went on the current market again in August. Four months afterwards, it’s even now waiting for an supply.

Here are 3 housing trends that will influence the home furnishings industry in 2023

Here are 3 housing trends that will influence the home furnishings industry in 2023

SCARSDALE, NY — Bungalows floorplans, retrofitted areas and calming hues are just three of the developments that will affect buyer purchases in 2023, according to the yearly trends report from The System Assortment, an online resource for hundreds of housing plans.

In accordance to corporation officers, Millennial choices, inflation and social media sharable spaces will generate dwelling layout in the coming calendar year, developing cozier, more comfortable and aesthetically pleasing areas with distinct item implications.

“Home design and style will encounter meaningful transform in 2023, with some style tendencies driven by creative, new tips inspiring Millennials — a technology representing a lot more than 40{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} of dwelling customers and social media driven — though other people will be affected by the realistic reality imposed on budgets by greater fascination fees and inflation,” reported Laurel Vernazza, house design and style expert at The System Assortment.

With insights gained from dependable architects, builders, realtors, contractors, and other housing field authorities, The Plan Selection releases its top rated house design and making trends every single 12 months and offers the adhering to predictions for 2023:

Bungalow obtain-in

Millennial and empty nesters who want to downsize in type are gravitating towards fashionable bungalow designs, in accordance to officials. Significant ceilings and open up flooring designs underscore the want for home furnishings that can “float” in a room, and considerably less square footage reinforces choices for multifunctional, smaller-scale designs that showcase form and perform.

Every single room counts

Increased desire prices are prompting a lot of home owners to transform their current home as an alternative of obtaining a new one particular, and The Program Assortment predicts that “overlooked alcoves, nooks, and corners” will be redesigned into “compact, colourful and inviting spaces.”

Potential merchandise tie-ins include distinctive art, unique lights, and a stand-on your own cupboard or desk that can rework space less than stairs or at the stop of a hallway into a useful home nook.

Colors that calm

In addition to the white, grey and black colorways that have been preferred in modern years, The System Assortment is forecasting that character-influenced shades of blue, inexperienced, and lilac will be well-liked in 2023, aspect of a visual aesthetic that references bringing the outside the house in.

Bonus pattern prediction

Two new interior characteristics forecast by The Approach Collection could influence gift, décor, and housewares buys in 2023. The prep pantry — a individual prep spot off the kitchen area — and a effectively-appointed mudroom that serves as a changeover in between the outdoor and primary dwelling regions are two preferred attributes of the household that offer possible retail opportunities for in tabletop, residence textiles, and inventive storage remedies.

See also:

I’m Cindy Hodnett, government editor of manufacturer advancement for BridgeTower Media’s Property Furnishings Division. Most just lately, I labored in a internet marketing content growth position, and now I’m putting my editor’s hat back again on for Furnishings Right now, Home Accents Currently, Gifts & Attractive Add-ons, Designers These days, Residence Textiles Nowadays and Home Furnishings Information. My 1st introduction to the trade aspect of property furnishings was as an editor for FT in 2012 and founding editor of Designers Today in 2015, and now I’m after yet again working along with some of the industry’s most dedicated industry experts to retain our readers educated about the gatherings, persons, and organizations that impact their business enterprise.