Views expressed by Entrepreneur contributors are their personal.
You’re reading Entrepreneur India, an global franchise of Entrepreneur Media.
Sustainability and recycling are overarching themes for the long run of business enterprise, as is evident from the quantity of consideration paid to them in the news cycles as perfectly as world wide governments.
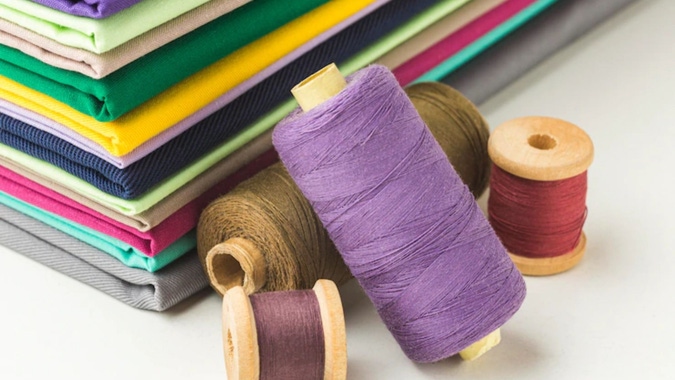
Freepik
The industry segment is anticipated to see a contraction at the very least until finally 2024. India’s $200 billion textile and attire field is experiencing a disaster as customers in Europe, U.S and other large marketplaces for Indian makers have cut paying out on clothing, as inflation is on rise and consequences of the Ukraine war lead to extra hardships. COVID constraints in China have also been between contributing variables. Returning to normalcy will take some time, likely by 2025.
The textile business, like the relaxation of the globe, is changing to new demands by implementing new approaches of production. The demand from customers for all-natural fibers like cotton, silk and linen has amplified exponentially. Most of this comes from a new generation of prospects who are willing to shell out extra for sustainability. This is a fantastic detail, as it is the demand from customers that will generate organisations to turn out to be additional sustainable, apart from regulation. According to a report by the UN, “Every 2nd, the equivalent of a person garbage truck of textiles is landfilled or burned. If absolutely nothing improvements, by 2050 the manner market will use up a quarter of the world’s carbon price range.”
Troubles like accountable producing, recycled thread apparel, reduced usage of electricity, sustainable and eco-welcoming clothing traces, lower water utilization, and zero-discharge producing are some of the challenges that concern the industry. The Govt of India is pushing textile suppliers to have zero-discharge crops so that fewer pollutants are enable out into freshwater bodies. This will bear fruit, but over time as organisations adapt to the mandates. The timeframe for this has been fixed for 2030.
Another crucial problem that the sector is grappling with is the usage of coal for boilers. A reduction in carbon footprint demands the phasing out of coal electricity, but cleaner choices are high priced. Textile gamers have questioned for alternate resources and engineering like gas to be provided at subsided rates, else the added expenditures will have to be handed on to buyers.
A move in the correct way to lessen pollution and progress sustainability is traceability — the means to monitor and trace the entire lifestyle-cycle of the merchandise from uncooked content and remaining great to intake, disposal and recycling. If key players adopt this kind of tactics, the industry’s effectiveness could strengthen, ensuring frequent source of top quality material and greater risk management.
Circularity is an additional important difficulty from a sustainability perspective. Recycling a garment will help in decreasing GHG emissions, saves means and aids increase economic, social and environmental rewards.
Countries like China and those in Europe have a coverage to recycle textile squander. India does not have these types of a plan yet, and a appropriate plan where the Indian textile industry can add in advancing electrical power transition commitments and recycle textiles is will need of the hour.
It is envisioned that by 2030-2035, most of the organised sector textile companies will be utilizing a sustainable product of doing organization. Tamil Nadu could turn out to be a model state for this sector – most of the makers in the state use 100 for each cent environmentally friendly electrical power, and have implemented zero liquid-discharge in processing. They also have PET recycling vegetation, use squander from spinning procedures to make yarn and fabric, deliver 100 per cent PET-recycled textile products for apparel, use garment cutting waste recycling to make new dresses, dwelling their plants in inexperienced-certified properties, and so on.
Residence health care’s 2022 was dimmed by the dim cloud of Medicare rate cuts. That cloud nevertheless hangs overhead in 2023.
To climate the storm, providers are scrambling to locate responses to persistent complications, specifically staffing shortages. At the similar time, they’re renegotiating arrangements with Medicare Gain (MA) designs and pivoting from specific services lines to other people. They’re trying to develop into additional successful – in any way achievable.
Just like any new year in the dwelling health business, 2023 delivers an onslaught of problems, but also possibilities.
As January will get underway, the workforce at Home Health and fitness Treatment Information took a stab at identifying leading trends for 2023. The subsequent are based on our analysis, reporting and considerable marketplace expertise.
Curious what we forecasted for last yr? Revisit our 2022 predictions below.
The selection of property health agencies will continue to decline
About the previous couple yrs, the number of present residence overall health agencies has steadily diminished.
In 2020, there had been 9,378 agencies, as opposed to 9,893 in 2019 and 10,852 in 2014, according to the Investigate Institute for Household Care’s 2022 Dwelling Treatment Chartbook.
There are a selection of elements that counsel this will continue.
Just one of these is the ongoing staffing issues vendors are experiencing. While staffing has alway been a ache level, the impact of the pandemic has place a critical strain on recruitment and retention. Additional compounding issues, nurses have left health and fitness treatment altogether due to burnout.
Even although the household health industry’s common turnover fee has gone down a little bit, it hasn’t been a considerable adequate dent to enhance staffing circumstances for vendors. There have been symptoms of improvement in the again 50 percent of 2022, but perhaps not enough to hold up with mounting desire set forth by the country’s aging populace.
In 2022, the turnover price for LPNs was 30.25{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b}, down from 36.54{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} 2021, and 31.19{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} for RNs, down from 32.35{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} in the past year, in accordance to info from the most new Property Treatment Salary & Added benefits report from Healthcare facility & Healthcare Payment Company.
In the long run, not having sufficient labor has restricted development: Past year, David Totaro, chief authorities affairs officer at Bayada Household Wellness Care, explained that the corporation had a practically 67{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} referral decrease rate. As an field the house overall health decrease fee was 58{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} past 12 months, according to CarePort information.
Worsening referral-rejection fees in 2023 will possible consider a toll on agencies’ base traces, and people that just cannot sustain a business in this natural environment will be pressured to close store.
An additional main element that will add to a minimize in the amount of present agencies: residence overall health amount cuts.
With the property wellness ultimate payment rule, suppliers noticed a 7.85{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} permanent adjustment to the 30-working day payment level. As well as, the U.S. Centers for Medicare & Medicaid Providers (CMS) will usher in other cuts and lasting adjustments connected to the rebalancing of the Individual-Driven Groupings Design.
“This 7.85{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} cut is worse than initially proposed and when absolutely carried out in 2024, will end result in an rapid drop in access to household overall health,” Partnership for Quality Home Health care CEO Joanne Cunningham claimed in a assertion in November. “This will have adverse effects on the availability of treatment for the most chronically unwell of the Medicare populace and outcome in access to care challenges. Even though this short-time period stage-in blunts the rapid impact, the prolonged-phrase penalties of this rule, until mitigated, will devastate accessibility to treatment in the home.”
Businesses will have to adapt to a extra complicated rate-for-service Medicare setting
At the time there have been signals of COVID-19 eventually letting up, household health companies have been hit with a payment rule proposal from the CMS that ended up gripping significantly of their emphasis for the calendar year.
Even though CMS didn’t apply its proposed cuts in its ultimate rule for 2023, the agency is relocating forward with plans to claw back again billions in perceived PDGM overpayments whilst instituting long-lasting fee adjustments.
Both CMS and the Medicare Payment Advisory Commission (MedPAC) feel dwelling health and fitness businesses are overpaid. Suppliers disagree, pointing to inflationary expenditures, staffing constraints, weak MA reimbursement, amongst other base-line burdens.
Vendors and CMS are not possible to occur to a resolution, meaning providers require to equipment up for what could be yrs of unsteady payment from their traditionally ideal payer, price-for-service Medicare.
The omnibus investing bill passed in December will need CMS to be a lot more transparent with its methodologies and figures. That could be a phase in the correct path. Sector advocates, such as Homecare Homebase, have previously shared their have math.
The home health and fitness market has a great deal of good friends in Congress who agree cuts are unfair. Even so, making more than enough momentum to get them to intervene in household wellness affairs is a tall activity.
As a last vacation resort, there could even be legal motion versus CMS.
HHCN sees this as staying the defining battle of this era of property health and fitness leaders and advocates, a single that started in 2022 and will carry on by 2023.
Big names will remain lively in the household health M&A area
Last yr noticed gamers this sort of as UnitedHealth Team (NYSE: UNH), CVS Well being (NYSE: CVS) and other people make important moves in the residence-centered care M&A place.
In 2022 by yourself, CVS Overall health inked an $8 billion deal to invest in Signify Wellbeing (NYSE: SGFY), and UnitedHealth Group introduced designs to obtain LHC Team Inc. for approximately $6 billion.
Household-dependent treatment has been heralded as the upcoming of wellness care, so it should really be no shock that merchants, insurers and other significant firms are vying for the chance to work within just the area.
Payers, in distinct, are in a wonderful position to obtain into property overall health.
“The money that they experienced set aside to shell out on medical utilization did not get expended for the duration of the pandemic,” Michael Abrams, controlling associate of Numerof & Associates, explained to HHCN in December. “The pent-up desire that there was concern would materialize when the pandemic sort of faded under no circumstances definitely materialized. They have been left with, you could say, a windfall profit, which they have been employing to acquire their way into things of the overall health care shipping system vertical integration.”
Also, now that the residence wellbeing last rule has been introduced, potential buyers have a much better strategy of what the upcoming of the sector holds and will be much more keen to choose a leap.
Even though America’s company giants will retain their attention on dwelling-centered care chances, there is a fantastic opportunity that 2023 passes without having a further monster, jaw-dropping mega deal that is anywhere shut to UnitedHealth Group’s LHC Group invest in.
That’s legitimate for the reason that, on a single hand, the dwelling wellness field is even now remarkably fragmented, with the premier organizations only managing solitary-digit sector shares. When LHC Group is providing to UnitedHealth Team, HHCN does not anticipate any of its in close proximity to-sizing friends to choose a comparable route.
And on the other hand, executing mega promotions will be tough in 2023, with curiosity rates large and buyers’ borrowing-qualities confined.
SNF-to-home diversion will hit a pace bump
When experienced nursing amenities (SNFs) ended up having difficulties mightily with COVID-19 at the commencing levels of the pandemic, property wellness stakeholders jumped on what they observed as an prospect.
SNF-at-property designs and SNF diversion to residence wellness in basic grew to become the chat of the city. But in 2023, HHCN sees that slowing down.
For a person, SNF referrals have rebounded. In actuality, they are at 104{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} of what they had been prior to the pandemic, in accordance to CarePort.
Resource: CarePort
In the meantime, the Select Household Treatment Act of 2021 – which would produce an increase-on to the household overall health reward, letting for far more SNF-form individuals to be referred to the house – has misplaced momentum.
CMS also laid out a proposal on Dec. 15 that would be certain there is not inappropriate SNF diversion to household well being treatment in MA.
Providers, whilst dealing with the aforementioned and troublesome fee natural environment, will possible aim far more on bread-and-butter worries as opposed to investing in new assistance strains or SNF-at-home systems.
General public players will see a rebound
For most publicly traded dwelling wellbeing providers, 2022 was not a banner year.
As a substitute of rebounding from two very hard several years because of to the COVID-19 pandemic and all else that arrived with the community health and fitness crisis, a number of property well being corporations ongoing to wrestle. That was the circumstance for industry-foremost corporations and newcomers to the scene.
In August, Enhabit Inc. (NYSE: EHAB) turned the most recent player on the community market. In its 1st quarter, Enhabit struggled to locate footing thanks to increasing expenditures for each go to, an maximize in the use of PTO from personnel, a minimize in admissions at acute care hospitals and various other components.
Earnings for Enhabit barely saw an uptick in the pursuing quarter as the organization touted its agreements with managed care ideas, which is becoming a craze close to the field.
Aveanna Healthcare Holdings Inc. (Nasdaq: AVAH) experienced related struggles. Just after a calendar year of currently being a publicly traded corporation, Aveanna had difficulties with labor, economic inflation, higher-than-expected adjustments in earnings reserves and numerous other enterprise dealings.
For all of the optimism heading into 2022, several of the significant house well being players might have been a year much too early in considering that they would be in a position to settle into a new typical.
Now, with the ultimate rule in location, the start of Property Wellbeing Worth-Based mostly Paying for (HHVBP) model’s very first functionality 12 months and other variables tied to the pandemic that may well not be as huge of an challenge, 2023 appears to be like to be a yr of stabilization.
“We anticipate this enterprise to expand in the large-solitary digits 12 months immediately after yr and go on to create gross margins in the superior 40s to 50{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b},” former Aveanna CEO Tony Weird explained in November.
Other providers like the Pennant Group Inc. (Nasdaq: PNTG) and Amedisys (Nasdaq: AMED), who also experienced up and down decades, should really anticipate balance in the yr in advance.
HHVBP will set off more value-primarily based care preparations outside of rate-for-service Medicare
Price-dependent care styles have been prolonged touted. Now, suppliers are obtaining their arms pressured with HHVBP. But that could be a superior issue.
Now that the initially efficiency yr is right here, there is a actual risk that value-primarily based arrangements are here to continue to be and will turn out to be an even larger sized aspect of the way house overall health providers do small business.
CVS Health and fitness, for occasion, is a person of the largest organizations in the place. Ahead of creating the Signify offer, it experienced by now been flirting with house-based treatment, but it even now needed a business that drove worth and had more abilities in the household.
“This acquisition will improve our connection to people in the house and enables providers to better address affected person needs as we execute our vision to redefine the health and fitness treatment knowledge,” CVS Wellbeing CEO Karen Lynch reported in a assertion just after the acquisition was announced. “In addition, this combination will strengthen our capability to develop and acquire new solution offerings in a multi-[payer] technique.”
Leaders in the market consider that price-based treatment has handed the tipping place and 2023 ought to be the year where it will become a far more mainstream technique to care in the property.
Just in the previous four months, Humana Inc. (NYSE: HUM) has claimed household health is important to its worth-based mostly care technique, Aveanna has fully commited to value-based mostly treatment in the extensive-expression long term, and Amedysis has told other programs to “take note” of their case-price offer with CVS Health’s Aetna.
“I feel it’s below to keep,” Signify Chief Healthcare Officer Dr. Marc Rothman informed HHCN in December. “I feel you’re observing extra providers just eventually accepting that they have to consider draw back hazard. And you’ve obtained lots additional companies forming to aid enable these factors.”
C-suite leadership shake-ups will prioritize payer executives
The dwelling-based care place has seen important turnover throughout the C-suite level in excess of the past 18 months, with management alterations at Amedisys, Encompass Health and fitness (NYSE: EHC)/Enhabit, EvergreenHealth Residence Care, Aid at Property and somewhere else standing as illustrations.
That pattern was reflective of a sector-large development in 2022. More than 830 health care CEOs experienced remaining their roles as of August very last calendar year, with hospital main executives departing at a history pace, in accordance to knowledge from business enterprise and government coaching firm Challenger, Gray & Xmas.
From 2021 to 2022, house health C-suite leaders left their posts regardless of the simple fact salaries routinely climbed.
On the lookout in advance towards 2023, HHCN sees a lot more C-suite variations coming, but not for the reason that of burnout, lackluster effectiveness or unfavorable motives, essentially. As property well being providers try to develop outside of payment-for-company Medicare towards hazard- and worth-based mostly payment models, they’ll increasingly flip to executives who are familiar with how payers believe.
VNS Overall health is a excellent example of a supplier that has now done so, with CEO Dan Savitt formerly at UnitedHealth Team and Landmark, for instance. AccentCare’s chief, Steve Rodgers, previously led OptumHealth Collaborative Care, far too.
With rate-for-services Medicare enrollment shrinking, MA and risk-primarily based payment designs will become the long run of the market. C-suite shake-ups will mirror that truth in 2023.
There will be extra expense in instruction, technological innovation in response to bigger-acuity patients
The patients likely into the clinic in 2023 will be sicker than regular. In switch, when they are referred out to home wellbeing businesses, they will nonetheless be sicker.
Average size of stay for patients inside of the clinic was 11{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} lengthier in October 2022 than it was in Oct 2019, according to CarePort. In the meantime, patients are far extra probable to be suffering from muscular conditions, alcohol or drug abuse, and fat reduction than they were being in the previous.
Resource: CarePort
Working with sicker individuals will call for new strategies of delivering home overall health companies, regardless of whether bolstered by improved schooling, greater engineering or both.
How to adapt to this adjust is what Lissy Hu, the president of connected networks at CarePort, just lately known as the “million-dollar dilemma.”
“It’s the million dollar question, right?” she stated. “And so as we imagine about property health and taking treatment of these bigger-acuity individuals, I assume a lot of house health organizations are now investing in treatment coordination, analytics and teaching their workforce to service some of these larger-acuity people. I imagine we’re heading to see much more of that than in the earlier.”
In 2023, HHCN predicts agencies will wrestle dealing with greater-acuity put up-acute patients – acquiring methods to evolve due to the fact of that challenge.
Contributions from Joyce Famakinwa, Patrick Filbin and Robert Holly.
In this post, PYMNTS analyzes developments shaping the banking industry in the EMEA location.
Zooming in on the diverse subregions shows that the EMEA banking sector remains at diverse levels of progress and development, irrespective of the acceleration in the digitization of fiscal providers throughout the areas.
1. UAE and Saudi Arabia Guide MENA Neobank Wave
Although electronic-very first banking is comparatively experienced in Europe and the U.S., in the Center East and North Africa (MENA), neobanks have nevertheless to acquire keep to the exact extent.
But in 2022, a string of launches and bulletins in the United Arab Emirates (UAE) and Saudi Arabia have signaled the arrival of digital financial institutions in the Gulf, with the rest of the location not considerably behind.
In the UAE, immediately after YAP officially debuted earlier this yr, govt-backed Wio followed go well with in September with an preliminary target on the compact to medium-sized organization (SMB) market.
In the meantime, in excess of the border in Saudi Arabia, three homegrown neobanks have all been granted licenses by the Saudi central bank (SAMA) — STC Bank and Saudi Digital Financial institution in June 2021 and D360 in February 2022.
Moreover being two of the most energetic FinTech marketplaces in the MENA location, UAE and Saudi Arabia have neobanks that are also properly positioned to companion and collaborate offered the countries’ geographic and cultural proximity.
For case in point, Wio’s CEO Jayesh Patel referenced Saudi Arabia as “an exceptionally intriguing market place [with] a ton of innovation and FinTechs” that the neobank could perhaps develop into.
2. African Banks Collaborate With FinTechs
In several African nations, the banking market does not have almost the achieve it does in other markets, with millions of folks without having entry to a bank account.
As these types of, the continent’s banks are evolving to embrace the alternative implies of accessing financial services most popular by numerous African shoppers.
For case in point, pan-African bank Ecobank is pursuing an software programming interface (API) strategy that will allow non-lender FinTechs to link to its monetary infrastructure and accessibility a increased vary of items and products and services.
As Djiba Diallo, the bank’s FinTech guide, advised PYMNTS, by enabling tech companions to access and experiment with Ecobank’s APIs by way of the bank’s sandbox, “FinTechs, 3rd get-togethers, telcos and any other firm that would like to offer ground breaking electronic payment methods to their customers” can effortlessly spouse with Ecobank.
Echoing Diallo, Richard Southey, chief digital experience officer at South African financial institution Absa, explained that “banks on their possess are never heading to be equipped to build all the bespoke purposes, which are heading to be significant in the direction of an informal trader, for occasion.”
He added that “FinTechs are commencing to address those complications [and] we are looking at far more and much more banks finding involved putting out API marketplaces for FinTechs to climb on to.”
3. European Banking institutions Doubling Down on Sustainability
Next the COP27 local climate convention in 2022 and the growing position of banks in slowing the hurt of global climate transform, more money establishments (FIs) are performing towards placing their funds the place their mouth is to embrace a additional proactive stance on sustainable investing and permit individuals to commit far more responsibly.
For instance, the Internet-Zero Banking Alliance has witnessed FIs representing 40{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} of world banking assets dedicate to aligning their lending and financial commitment portfolios with internet-zero emissions by 2050, quite a few European banking institutions have set their very own formidable targets.
And as the variety of environmentally aware shoppers will increase across the continent, banking institutions now routinely check and report on their net-zero development.
For instance, Lloyds publishes common “net-zero exercise updates” assessing its development toward its environmental targets.
In the meantime, European banking companies are main the demand to roll out carbon trackers that assistance folks watch the carbon emissions their paying out generates.
4. Financial institutions Known as to Hook up to CBDC Programs
As central banking institutions in the EMEA region keep on to take a look at and acquire their possess digital currencies, there are expanding phone calls for FIs to much better define their purpose as mediators amongst central banking institutions and customers in central lender electronic currency (CBDC) techniques.
For case in point, the European Central Bank (ECB) issued a progress report on the electronic euro project in December outlining its findings on what the role of banking companies will be ought to it come to a decision to situation a CBDC.
Substantially like present Eurosystem payment rails, any digital euro infrastructure would delegate most customer-dealing with capabilities to financial institutions, although the Eurosystem would be responsible for the precise settlement of transactions.
Of program, should it finally choose to go after a CBDC, banking institutions won’t be the only intermediaries that will have to interoperate with the electronic euro program.
In September, the ECB announced that it experienced selected 5 associates to be involved in a “prototyping exercise” for the digital euro job. Along with the Spanish bank Caixabank, payment processors Nexi and Worldline have been picked out to take part in the physical exercise as nicely as Amazon and the European Payment Initiative.
For all PYMNTS EMEA protection, subscribe to the day-to-day EMEA Newsletter.
PYMNTS Knowledge: Why Individuals Are Hoping Electronic Wallets
A PYMNTS research, “New Payments Possibilities: Why Customers Are Seeking Digital Wallets” finds that 52{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} of US consumers experimented with out a new payment process in 2022, with many picking out to give digital wallets a try for the initially time.
See Far more In: Absa, banking, banking market, CBDC, Central Financial institution Digital Forex, weather alter, Ecobank, EMEA, ESG, Eurosystem, FinTech, MENA, neobank, Web-Zero Banking Alliance, Information, saudi arabia, Sustainability, UAE
From the pandemic’s affect on offer chains to geopolitics, the earlier couple yrs have been characterised by uncertainty. As we head into a new year, this uncertainty remains and is anticipated to just take a toll on world-wide trade growth.
The Earth Trade Firm expects trade expansion to slow sharply but continue being good in 2023. Past the numbers, I imagine trade is the lifeline of economies around the globe, with the potential to reduce poverty and inequality.
This is wherever trade finance comes in—to make worldwide trade accessible by making certain that importers obtain their goods and exporters obtain their payments. But the core ecosystem—exporters, importers and banks—is complicated with a number of parties concerned in a solitary transaction.
As a CEO of a world trade finance network, there are 3 components at perform that I consider will reshape the foreseeable future of trade finance. Mixed, these have the likely to contribute to the resiliency of the sector by bringing assurance and sizeable advancement to trade finance globally.
1. There are however large possibilities to digitize trade finance.
The trade finance industry is closely reliant on paper and handbook procedures to make sure that liquidity flows by the ecosystem and pitfalls are managed. Even with the momentum we’ve viewed in the earlier handful of decades from financial institutions and corporates embracing blockchain know-how in their trade finance procedures, there is however space for further development.
One particular area is digitizing documentation and the bill of lading (BL). In accordance to McKinsey, an digital invoice of lading (eBL) would help save $6.5 billion in immediate fees and allow $40 billion in international trade.
A very small percentage of BLs are now electronic, which signifies a huge upside chance, however, the current closure of TradeLens, an eBL system formed by Maersk and IBM, highlights the issues of collaboration in between huge organizations and the field. We remain hopeful for extra prevalent adoption of the eBL in the long term, as electronic innovation should be embraced in order to go the industry forward.
As with all electronic transformation, there is some hesitation to soar on board until finally requirements come in. But, in my feeling, playing the waiting around sport will just keep the field again. Criteria will arrive in, and anyone ought to be ready to adapt and be open to them as they become more codified.
The last several decades have been about the electronic transformation of industries, and I feel this will continue to be matter selection just one for a long time to arrive.
2. Integration between money establishments and fintechs will be important to long run advancement.
As the trade finance industry moves forward with its digitization endeavours, collaboration concerning financial institutions and fintechs will be essential to reworking the potential.
Many banking associates have reported that they are just at the commencing of their digital journey when it arrives to trade finance. The the greater part also do not have the resources–whether which is time or money–to experiment with technologies that could drive even more efficiencies in the marketplace. This is in particular correct when concentration on core business enterprise all through hard financial occasions indicates all palms are concentrated on their conventional enterprises.
This is in which fintechs can assist comprehensive the photo, as they are significant in a bank’s digitization journey and can connect the common architecture to external knowledge flows. Inside monetary institutions, lots of have developed architectures that enable them to be integrated with unique fintechs across diverse regions, with the target of streamlining workflows and driving efficiencies that will in the long run include value for their clientele.
3. The up coming wave of innovation in trade finance is in digital property.
Ultimately, the increasing desire in digital property is now also apparent in trade finance. Even though cryptocurrencies and Central Financial institution Electronic Currencies are usually associated with electronic assets, there is a diverse option situation with electronic trade belongings as opposed to digitalization of payments.
Electronic asset transactions are recorded in safe digital ledgers. Blockchain is an illustration of a form of dispersed ledger engineering (DLT), where transactions are grouped in blocks of information which are linked with each other cryptographically.
Devoid of a use case, like the transformation of trade finance, blockchain or DLT would just be an impressive or fascinating know-how. This is exactly where I see the prospective for digital property to make world-wide trade far more efficient.
Trade and trade finance is complex, with numerous get-togethers and processes associated to facilitate the motion of merchandise and solutions from one port to an additional. Take the letter of credit score (LC) for case in point. It is a mostly manual procedure that has been about for much more than a century—and nonetheless mainly managed on a frequent information transfer system recognised as mailing paper files.
A electronic LC is an example of tokenization (disclaimer: this is a remedy my corporation gives). And by leveraging distributed ledger technological know-how (DLT), there is prospective to digitize much more trade finance procedures by working with wise contracts to generate electronic trade assets.
There is also an chance to produce tokenized digital assets to depict lender danger. I imagine this will produce a extra inclusive potential for trade finance and amount the actively playing industry for SMEs and regional banking companies who tend to make smaller sized transactions. When it arrives to how trade is financed, banking companies normally target on originating new trade finance financial loans, but the substantial friction and processing fees signifies they are typically incentivized to goal larger sized transactions. Digitizing the system will indicate decreasing the expense to support transactions and enabling smaller sized transactions, the kinds that the SMEs depend on to be far more rewarding.
These 3 drivers—the option to even more digitise trade finance, the increased collaboration among financial institutions and fintechs, as nicely as the probable to make tokenised digital assets in trade finance—are switching the character of how trade finance is performed in the encounter of the difficulties we’re observing. With all three things at enjoy, it will bring assurance, effectiveness and substantial growth to trade finance globally commencing in 2023.
In this series of interviews, we focus on the men and women who are shaping the point out of housing at the major — the policy and regulation specialists. The FHFA and the GSEs are critical to painting the picture of today’s housing marketplace and marketplace tendencies. To help get rid of some gentle in this location, many of the 2022 HousingWire Vanguard honorees shared their insights on what’s happening at the federal amount that’s heading to have an affect on housing this 12 months and into 2023.
Armando Falcon, CEO at Falcon Capitol Advisors
Armando Falcon, CEO at Falcon Capitol Advisors
HousingWire: Which traits in housing regulation are you and your group most centered on as we move into 2023?
Armando Falcon: Hunting ahead to 2023, there are a couple of wide trends that we are focusing on. The to start with is the total enterprise transformation that is taking spot in the home finance loan field. This is the outcome of several forces: the Fed’s anti-inflation coverage the immediate deceleration in lending that’s resulted in a 40{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} fall in apps the growing cost of house loan generation, which has now damaged the $10,000 for every loan threshold and the continued push in direction of digitization in mortgage loan lending.
These are prime of intellect for my workforce, our purchasers and the sector. The second wide development is accessibility to homeownership and affordability. Dwelling rates have in no way been increased, pent-up desire stronger and housing stock tighter. These ailments are hard for even the average homebuyer, permit on your own minimal-earnings and minority consumers.
There is a increasing sentiment in the two the community and private sectors that more requirements to be completed to help people, specially underserved buyers, get ready for homeownership and to shut the affordability gap. We’re observing new power and new initiatives in this area at numerous house loan and housing businesses.
Similarly, massive lenders are expanding their ESG and social responsibility applications. The dedication is genuine, and we see it only acquiring much better.
HW: As a 2022 Vanguard honoree, what has been your proudest accomplishment?
AF: Is it alright to say that I am proud of building a consulting firm designed of some incredibly talented folks who are supporting the mortgage loan market adapt to a current market in changeover? That I’m proud of the part that they are playing in supporting modernize property finance loan generation and the secondary marketplace? Mainly because I am.
About the earlier 15 yrs, our team has developed to more than 50-moreover associates, several of whom have held management positions at leading loan companies, tech and details companies and mortgage loan companies.
It’s really hard to decide just a person project because we’ve had many interesting engagements recently: for instance, our do the job with Ginnie Mae on its Digital Collateral Method or the asset income program that we handle for HUD that has moved a lot more than 50{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} of these vacant homes to nonprofit companies for reasonably priced housing or the analytic get the job done we offer to the business individuals to enable them evaluate development on their ESG investments.
These engagements are assisting to make the property finance loan business far more productive and far more resilient, two objectives that I pursued as a regulator and carry on to emphasis on as a guide to the business.
HW: What major adjustments in federal regulation and legislative guidelines need to people be paying out extra interest to?
AF: As I talked about, there is a large amount of desire and momentum about the regulation of issues of affordability and inclusion in homeownership. It is a priority at FHFA, FHA, HUD and Ginnie Mae. These organizations are making an attempt to occur up with creative options to make housing more inexpensive and homeownership additional achievable.
There is practically a New Offer spirit at perform. We’re also seeing new marketplace-primarily based initiatives coming from the personal sector. 1 of the nation’s largest loan companies, for instance, has just announced that it is tests a new plan that will give zero-down payment mortgages with no closing expenditures to very first-time homebuyers in Black and Hispanic neighborhoods in five big towns.
HW: How has your knowledge as the director of OFHEO (now FHFA) affected your initiatives and management at Falcon Capital?
AF: The GSEs and Ginnie Mae have been evangelical in their aid of digital lending. Nowadays approximately 5{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} of all conforming home loans are eNotes, and all of the companies are on record encouraging loan providers to originate extra property digitally. Ginnie Mae has been accepting eNotes on a pilot foundation given that the beginning of the calendar year. In June, they expanded their Digital Collateral System, and they are now in the system of accepting new applications from eIssuers, eCustodians, and subservicers. This was an vital milestone in digitizing govt lending, which was roughly a $757 billion sector.
HW: Falcon Money often works with govt agencies in system management and regulation method. Is there one particular task or partnership that you are very pleased of in specific?
AF: Creditors see the value in offering their shoppers the similar variety of easy digital expertise that they come upon in other features of their life (e.g., banking, purchasing, transportation). They are also concerned that if they really don’t offer this experience, more substantial countrywide retail lenders will. This is why I think these initiatives will proceed even in the smaller, much more aggressive environment that the market is now facing.
Making electronic, somewhat than paper, assets offers increased cash industry efficiencies and lessens prices and mistakes. Latest ROI reports have revealed that eClosings and eNotes can help save originators roughly $400 per loan. That’s a major variety when you take into consideration that the ordinary originator misplaced $82 for every loan in the 2nd quarter, in accordance to the Mortgage Bankers Association.
This interview was at first posted in the Oct/November difficulty of HousingWire Journal. To perspective the whole concern, click here.
BOSTON, Dec. 22, 2022 /PRNewswire/ — Data Bridge Market Research has recently published a Report, titled, “Vending Machine Market” The report offers an extensive analysis of key growth strategies, drivers, opportunities, key segment, Porter’s Five Forces analysis, and competitive landscape. Market research information of Vending Machine report analyses prime challenges faced by the Vending Machine industry currently and in the coming years, which gives idea to other market participants about the problems they may face while operating in this market over a longer period of time. This Global Vending Machine market report contains all the company profiles of the major players and brands. These factors consist of but are not limited to latest trends, market segmentation, new market entry, industry forecasting, future directions, opportunity identification, strategic analysis and planning, target market analysis, insights and innovation.
Data_Bridge_Market_Research_Logo
The vending machine market is expected to be growing at a growth rate of 9.55{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} in the forecast period of 2022 to 2029.
An automated machine that is meant to supply the users with a diverse range of products: snacks, beverages, pizzas, cupcakes, newspapers, tickets, etc. A slot machine dispenses a product to the users supported the quantity of cash inserted and choice of the merchandise.
The innovative machine and vending effortlessness is the major factor accelerating the growth of the vending machine market. Furthermore, burgeoning requirement for ready to eat snacks, and on-the-go drinks, due to unsystematic schedule and lifestyle which is expanding the goods business are also expected to drive the growth of the vending machine market. However, strict regulations regarding the sales of unhealthy, junk food and tobacco products in public places and the majority of commercial spaces restrains the vending machine market, whereas, fixed product prices will challenge the vending machine market growth.
Some of the major players operating in the Vending Machine market are:
Why should you prefer DBMR’s market insights report?
Detailed vendors report with competitive landscape
Data on revenue-generating market segments
Details on the market shares of various regions
Off-the-shelf research reports
Reports can be tailored to meet the customer’s needs
Trusted by more than 100 fortune 500 organizations
Information about the market’s key drivers, trends, and challenges
Parent market analysis
Five-force market analysis
Key Industry Segmentation: Vending Machine Market
On the basis of product, the vending machine industry is segmented into beverage, food, tobacco, and others.
On the basis of application, the vending machine market is segmented into retail sites, public transport hubs, offices and institutions, and others.
On the basis of payment mode, the vending machine market is bifurcated into cash and cashless.
Consider Data Bridge Market Research for this Report which would Help Impact Your Revenues Positively
This study offers the latest product news, trends, and updates from the industry’s leading players who have leveraged their market position.
It also offers strategic plans and standards to arrive at informed business decisions adopted by the main players, thereby advocating your go to market strategies.
In addition, it offers insights into the dynamics of customer behaviour that can help the organization better curate market strategies
Usage of exclusive tailor-made tools along with primary research, secondary research and our in-house data model helps us in extracting the exact market numbers
Mapping the customer in 3P grid comprising of Purpose, Planning and Positioning, thereby delivering a solution by keeping the prospecting client at the sweet spot
The market research report includes all of the market’s valuable elements, such as sales growth, product pricing & analysis, growth opportunities, and recommendations for addressing market challenges
The report covers all the primary mergers & acquisitions, alliances, and collaborations that have generated additional opportunities for market players or in some cases, challenges
Data Bridge Market Research relies on industry-wide databases for both regional and global authentic data, which enables the team to decipher the precise trends and existing scenario in the market.
The report takes a 360-degree approach to ensure that the niche and emerging aspects are also factored in to ultimately get accurate results.
Analyst Support: Speak to our research analysts to solve any queries you may have before or after buying the report.
Analyst Support: Get you query resolved by speaking to our research analysts before and after purchasing the report.
Customer Satisfaction: Our team of research analysts will accommodate all your research needs and customize the report accordingly.
Long-standing experience: Our team of analysts will offer elaborate and accurate insights pertaining to the market.
This report supplies a forward-looking perspective on different driving factors or controlling the market gain.
This report assists to make wise business choices using whole insights of this market and also from creating a comprehensive evaluation of market sections.
The countries covered in the vending machine market report are U.S., Canada and Mexico in North America, Germany, France, U.K., Netherlands, Switzerland, Belgium, Russia, Italy, Spain, Turkey, Rest of Europe in Europe, China, Japan, India, South Korea, Singapore, Malaysia, Australia, Thailand, Indonesia, Philippines, Rest of Asia-Pacific (APAC) in the Asia-Pacific (APAC), Saudi Arabia, U.A.E, Israel, Egypt, South Africa, Rest of Middle East and Africa (MEA) as a part of Middle East and Africa (MEA), Brazil, Argentina and Rest of South America as part of South America.
North America is expected to be the most extensive geographical market over the determined period due to conditions, such as changing lifestyles and huge demand for comfort meals. On the contrary, Asia-Pacific (APAC) is considered to be the fastest-expanding sector in the period of 2022 to 2029. Japan is a particularly profitable nation in the regional market. Growing investment and corporate areas in Asia-Pacific (APAC) are also adding to the vending machine demand.
Refrigerated Vending Machine Market, By Retail Channel (Supermarket, Hypermarket), Application (Food Service, Food and Beverage Distribution, Food and Beverage Retail, Other), End-User (Food Processing Industry, Food Service Industry, Full Service Restaurant and Hotels, Quick Service Restaurants, Catering Services), Country (U.S., Canada, Mexico, Germany, Sweden, Poland, Denmark, Italy, U.K., France, Spain, Netherlands, Belgium, Switzerland, Turkey, Russia, Rest of Europe, Japan, China, India, South Korea, New Zealand, Vietnam, Australia, Singapore, Malaysia, Thailand, Indonesia, Philippines, Rest of Asia-Pacific, Brazil, Argentina, Rest of South America, U.A.E, Saudi Arabia, Oman, Qatar, Kuwait, South Africa, Rest of Middle East and Africa) https://www.databridgemarketresearch.com/reports/global-refrigerated-vending-machine-market
Smart Vending Machine Market, By Type (Retail Vending Machine, Self Service, ATM), End Use Industry (Retail Industry, Entertainment and Hospitality, Medical, Transportation/Public Transport, Others), Product (Single Specialized Machines, Full-Line Machines), Technology (Саѕhlеѕѕ Ѕуѕtеmѕ, Теlеmеtrу Ѕуѕtеmѕ, Vоісе Rесоgnіtіоn), Country (U.S., Canada, Mexico, Germany, Sweden, Poland, Denmark, Italy, U.K., France, Spain, Netherland, Belgium, Switzerland, Turkey, Russia, Rest of Europe, Japan, China, India, South Korea, New Zealand, Vietnam, Australia, Singapore, Malaysia, Thailand, Indonesia, Philippines, Rest of Asia-Pacific, Brazil, Argentina, Rest of South America, U.A.E., Saudi Arabia, Oman, Qatar, Kuwait, South Africa, Rest of Middle East and Africa) https://www.databridgemarketresearch.com/reports/global-smart-vending-machine-market
Intelligent Vending Machines Market, By Product Dispensed (Salty and Savory Snacks, Bakery Products, Confectionery Products, Beverages, Others), Application (Retail Sites, Public Transport Hubs, Offices/Institutions), Installation Site (Offices, Retail Stores, Public Places, Others), Country (U.S., Canada, Mexico, Brazil, Argentina, Rest of South America, Germany, Italy, U.K., France, Spain, Netherlands, Belgium, Switzerland, Turkey, Russia, Rest of Europe, Japan, China, India, South Korea, Australia, Singapore, Malaysia, Thailand, Indonesia, Philippines, Rest of Asia-Pacific, Saudi Arabia, U.A.E, South Africa, Egypt, Israel, Rest of Middle East and Africa) https://www.databridgemarketresearch.com/reports/global-intelligent-vending-machines-market
Knitwear Market, By Product Type (T-Shirts and Shirts, Sweaters and Jackets, Sweatshirts and Hoodies, Shorts and Trousers, Evening Dresses, Suits, Leggings), Material Type (Natural, Synthetic, Blended), Application (Outerwear, Innerwear, Sportswear, Others), Consumer Group (Men, Women, Kids), Distribution Channel (Online, Offline) https://www.databridgemarketresearch.com/reports/global-knitwear-market
Facial Cleanser Market, By Product Type (Foam-Type Cleanser, Solvent-Based Cleanser, No Foam Cleanser, Collagen Type Cleanser, Face Cream, Face Wash and Face Oil), Skin Type (Neutral Skin, Dry Skin, Oily Skin, Mixed Skin and Sensitive Skin), Type (Normal Type, Scrub Type and Efficacy Type), End-User (Personal and Commercial), Application (Skin Whitening, Moisturizing, Repair, Blackheads, Oiliness, Dryness, Anti-Aging and Dark Spots), Distribution Channel (Online Channel and Offline Channel), Usage (Male and Female), Country (U.S., Canada, Mexico, Brazil, Argentina, Rest of South America, Germany, France, Italy, U.K., Belgium, Spain, Russia, Turkey, Netherlands, Switzerland, Rest of Europe, Japan, China, India, South Korea, Australia, Singapore, Malaysia, Thailand, Indonesia, Philippines, Rest of Asia-Pacific, U.A.E, Saudi Arabia, Egypt, South Africa, Israel, Rest of Middle East and Africa) https://www.databridgemarketresearch.com/reports/global-facial-cleanser-market
An absolute way to forecast what future holds is to comprehend the trend today!
Data Bridge Market Research set forth itself as an unconventional and neoteric Market research and consulting firm with unparalleled level of resilience and integrated approaches. We are determined to unearth the best market opportunities and foster efficient information for your business to thrive in the market. Data Bridge endeavours to provide appropriate solutions to the complex business challenges and initiates an effortless decision-making process. Data Bridge is an aftermath of sheer wisdom and experience which was formulated and framed in the year 2015 in Pune.
Data Bridge Market Research has over 500 analysts working in different industries. We have catered more than 40{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} of the fortune 500 companies globally and have a network of more than 5000+ clientele around the globe. Data Bridge adepts in creating satisfied clients who reckon upon our services and rely on our hard work with certitude. We are content with our glorious 99.9 {1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} client satisfying rate.
Contact Us:- Data Bridge Market Research US: +1 888 387 2818 UK: +44 208 089 1725 Hong Kong: +852 8192 7475 Email:- corporatesales@databridgemarketresearch.com