How the Silicon Valley Bank Collapse Impacts the Auto Industry

How the Silicon Valley Bank Collapse Impacts the Auto Industry

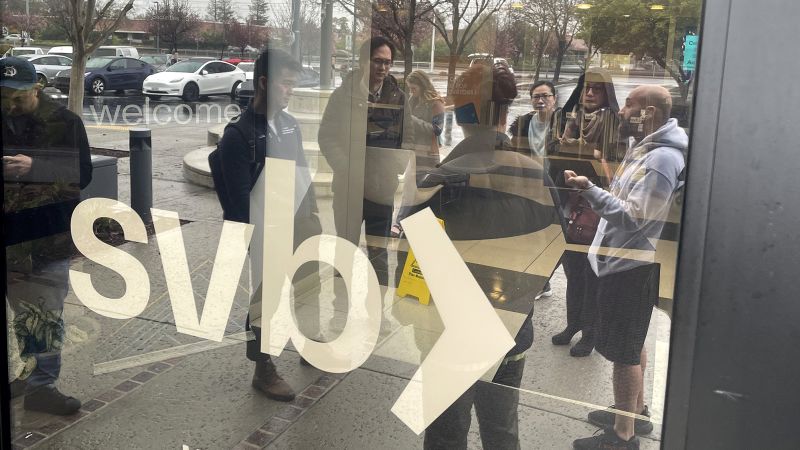
You may possibly have read about Silicon Valley Bank’s collapse by now. Information networks all around the earth have claimed on extended lines of folks waiting around outdoors lender branches in a panic and hoping to withdraw every penny of hard cash in their accounts out of the panic they may possibly shed it all. Silicon Valley Lender (SVB) held more than $200 billion in assets, but over the program of a weekend it experienced the second most significant financial institution collapse in background. If you happen to be asking yourself how a financial institution you in all probability have not read of bought so large, that is because SVB primarily bargains with startups and undertaking capitalists, that’s why the Valley-influenced identify.

As soon as news of SVB’s collapse started off to distribute, it was uncovered just how a lot of huge and small tech providers and other begin ups either experienced dollars tied up in SVB or vice versa. For the car earth, the Silicon Valley connection experienced many asking yourself if there were any automotive providers tied up in this mess, so we did some digging. Our lookup turned up quite a few automobile businesses that have financing from SVB like, which incorporates: TrueCar, OTTO Motors, Clearpath Robotics, Beepi, AutoLeap, Trucker Route, and DRIVIN.

How does SVB’s collapse affect these firms and the car marketplace as a whole? Even though these companies have previously gained their funding from SVB, they is not going to be equipped to protected any much more from SVB at this issue. The California lender was taken in excess of by federal regulators on Friday. A reported open govt investigation into SV Financial institution could consequence in much more attention on the concerned companies’ funds than they’d likely like, as very well. Taking into consideration the automotive market place is still in restoration mode from the pandemic and pursuing chip shortage any tech firm that depends on automakers as shoppers might see dire straits if they won’t be able to secure an additional resource for funding.

Car marketplace economical pundit Fortunate Lopez predicts things could get a lot worse in the long run, but for now he sees organizations these kinds of as TrueCar working with income stream concerns. “TrueCar is a superior case in point of this. They cost sellers a set sum of income to do business, but most of their dollars that they applied to run their functions comes from investors,” explained Lopez. “They are in want of a significant funds infusion.” We attained out to TrueCar for remark, and are waiting around to listen to back again.

Indirectly, the SVB’s difficulties has prompted California buyers to get rid of self esteem in the industry as the concern of “bank contagion” grows. Even while this kind of fears feel to be abating at publishing time, Benzinga documented that Wolfe Research downgraded its outlook on Tesla stock because of to “macroeconomic issues” subsequent SVB’s collapse. That’s they vital takeaway for the car industry—which is a lot the similar for the broader banking world article-SVB-collapse: It shakes confidence in that system, which could direct to tighter lending for Silicon Valley-aligned businesses, automotive or otherwise, though resulting in potential funding issues for companies that for whom SVB might have been their only funds faucet.

Western Alliance Bank Issues Updated Financial Figures in Wake of Industry Developments

Western Alliance Bank Issues Updated Financial Figures in Wake of Industry Developments

PHOENIX, March 10, 2023–(Small business WIRE)–Western Alliance Financial institution (NYSE: WAL), in light-weight of latest market situations, updates the pursuing financial (unaudited) information:

  • Funds remains potent with CET1 of 9.32{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b}, as of 12/31/2022. We assume CET1 to continue to increase from yr stop amounts to 9.5{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} or larger at to start with quarter conclude

  • Asset top quality stays superb, and we have seasoned no major adjustments due to the fact 12 months stop, which includes categorised belongings, non-executing property, and cost-offs

  • Additionally, Western Alliance affirms its whole-12 months deposit expansion direction of 13{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} – 17{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b}

About Western Alliance Bancorporation

With more than $65 billion in belongings, Western Alliance Bancorporation (NYSE:WAL) is a person of the country’s leading-doing banking corporations. By its most important subsidiary, Western Alliance Bank, Member FDIC, business enterprise consumers profit from a entire spectrum of customized banking answers and remarkable assistance sent by business specialists who set clients initially. Important accolades consist of getting ranked #1 top rated-accomplishing big bank with property bigger than $50 billion in 2021 by both equally American Banker and Bank Director. Serving consumers throughout the place where ever company happens, Western Alliance Financial institution operates personal, complete-support banking and fiscal brand names with places of work in important markets nationwide. For additional data, stop by westernalliancebank.com.

Cautionary Notice Concerning Forward-Searching Statements

This launch is made up of ahead-on the lookout statements that relate to anticipations, beliefs, projections, upcoming plans and approaches, predicted activities or traits and very similar expressions regarding matters that are not historical specifics. Examples of forward-looking statements consist of, amid others, statements we make relating to our expectations with regard to our business enterprise, economic and working final results, which includes deposit balances and funds ratios, potential economic effectiveness and dividends. The forward-looking statements contained herein reflect our present views about long run gatherings and fiscal efficiency and are subject to risks, uncertainties, assumptions and changes in instances that may well lead to our real outcomes to differ considerably from historic benefits and people expressed in any ahead-seeking assertion. Some factors that could lead to true effects to vary materially from historic or expected final results consist of, among some others: the risk components talked about in the Company’s Annual Report on Variety 10-K for the calendar year finished December 31, 2022, as filed with the Securities and Exchange Commission the likely adverse results of unusual and infrequently occurring occasions modifications in basic economic conditions, both nationally or locally in the regions in which we carry out or will carry out our business the influence on financial markets from geopolitical conflicts inflation, desire amount, market place and monetary fluctuations raises in aggressive pressures among the fiscal establishments and businesses offering identical items and expert services larger defaults on our personal loan portfolio than we hope modifications in management’s estimate of the adequacy of the allowance for credit rating losses legislative or regulatory variations or adjustments in accounting concepts, procedures or recommendations supervisory actions by regulatory organizations which could limit our capability to go after specific development opportunities, such as enlargement via acquisitions supplemental regulatory necessities resulting from our ongoing progress management’s estimates and projections of interest premiums and desire rate coverage the execution of our small business prepare and other variables impacting the fiscal solutions business frequently or the banking business in unique.

Any forward-hunting assertion created by us in this release is dependent only on info at the moment available to us and speaks only as of the date on which it is produced. We do not intend and disclaim any duty or obligation to update or revise any sector info or forward-looking statements, whether penned or oral, that may be designed from time to time, established forth in this press launch to mirror new details, potential events or if not.

See source variation on businesswire.com: https://www.businesswire.com/news/home/20230310005318/en/

Contacts

Buyers:
Dale Gibbons, 602-952-5476

Media:
Stephanie Whitlow, 480-998-6547

Takeaways from America’s second-largest bank failure

Takeaways from America’s second-largest bank failure


New York
CNN
 — 

Silicon Valley Bank’s 48-hour collapse led to the second-largest failure of a financial institution in US history.

SVB was one of America’s 20 largest commercial banks and is now under the control of the US Federal Deposit Insurance Corporation after it became unable to pay back customers who withdrew their deposits.

Though experts quelled fears of a wider contagion, the bank’s collapse could have significant ramifications on the startup and tech sectors.

Here’s everything we know so far.

Founded in 1983, Silicon Valley Bank provided financing for almost half of US venture-backed technology and health care companies. They have been hurt by higher interest rates and dwindling venture capital.

While relatively unknown outside of Silicon Valley, SVB was among the top 20 American commercial banks, with $209 billion in total assets at the end of last year, according to the FDIC.

Its stunning, and seemingly rapid, fall is the largest shutdown of a US bank since Washington Mutual in 2008.

ruth health ceo svb

CEO describes pulling money from bank hours before collapse

The wheels began to come off Wednesday, when SVB announced it had sold a bunch of securities at a loss, and it would sell $2.25 billion in new shares to shore up its balance sheet.

California regulators closed down the tech lender Friday. The FDIC is acting as a receiver, which typically means it will liquidate the bank’s assets to pay back its customers, including depositors and creditors.

The FDIC, an independent government agency that insures bank deposits and oversees financial institutions, said all insured depositors will have full access to their insured deposits by no later than Monday morning. It said it would pay uninsured depositors an “advance dividend within the next week.”

The FDIC took over in the midmorning Friday; usually it waits until markets close.

“SVB’s condition deteriorated so quickly that it couldn’t last just five more hours,” wrote Better Markets CEO Dennis M. Kelleher. “That’s because its depositors were withdrawing their money so fast that the bank was insolvent, and an intraday closure was unavoidable due to a classic bank run.”

To combat rampant inflation, the central bank has been aggressively raising interest rates since 2022. It made borrowing for businesses and individuals more expensive to cool the economy down.

When interest rates were near historical lows, the banks bought up on long-dated, seemingly low-risk Treasuries. But as rates rose, the value of those assets has fallen, leaving them sitting on unrealized losses.

High rates significantly constrained tech companies, which undercut the value of tech stocks and made it difficult to raise funds.

Faced with higher interest rates, loss of IPOs and a funding drought, SVB’s clients began pulling money out of the bank.

“The higher rates have also lowered the value of their treasury and other securities which SVB needed to pay depositors,” Moody’s chief economist Mark Zandi said. “All of this set off the run on their deposits that forced the FDIC to takeover SVB.”

aaron klein smerconish iso 3 11 23

Hear why ex-US Treasury official questions regulators’ handling of Silicon Valley Bank

US customers held at least $151.5 billion in uninsured deposits by the end of 2022, SVB’s latest annual report said. Foreign deposits reached at least $13.9 billion and are also uninsured.

Companies may have gotten a decent amount out during the bank run, but there is still a lot of money at stake if a buyer or bailout isn’t reached.

Roku held approximately $487 million of its $1.9 billion in cash at Silicon Valley Bank, 26{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} of the company’s total. The streaming company added most of the deposits were uninsured. Video game site Roblox and bankrupt cryptocurrency lender BlockFi are also facing the fallout.

On Thursday, billionaire hedge fund manager Bill Ackman compared SVB to Bear Stearns, the first lender to collapse at the start of the 2007-2008 global financial crisis.

“The risk of failure and deposit losses here is that the next, least well-capitalized bank faces a run and fails, and the dominoes continue to fall,” Ackman wrote on Twitter.

But most analysts say the implosion of SVB appears company-specific for now, wrote Julia Horowitz and Anna Cooban.

Banks and lenders with specialized clientele, just like SVB, will feel the brunt of the fallout.

“The reason [SVB is] in trouble is because they have exposure to particular industries,” said Jonas Goltermann, deputy chief markets economist at Capital Economics. Most other banks, he added, are more “diversified.”

There’s also less anxiety about the stability of the banking sector due to the significant regulatory reforms put in place after the crisis in 2008.

Everyday consumers, on the whole, are unlikely to be affected. But the collapse is a good reminder to be aware of where your money is held, and not to have it all in one place.

“The first bank failure since 2020 is a wake-up call for people to always make sure their money is at an FDIC-insured bank and within FDIC limits and following the FDIC’s rules,” Matthew Goldberg, a Bankrate analyst said.

SVB was a top lender for the startup community, whose founders now worry about getting their money out, making payroll and covering operating expenses, Catherine Thorbecke wrote.

“Now that the bank has folded, I just want to know what happens next,” Ashley Tyrner, founder of health food delivery company FarmboxRx, told CNN in an e-mail. “The FDIC covers 250K, but am I going to recover my whole 8 figures?”

Some are getting creative. Children’s toy, apparel and experience retailer CAMP sent an email to customers Friday and advertised on their site.

“Unfortunately, we had most of our company’s cash assets at a bank which just collapsed. I’m sure you’ve heard the news.” It urged customers to use the code BANKRUN to save 40{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} off all merchandise (or pay full price – which it said would be appreciated).

Lenders somewhat similar to SVB are in an unfortunate situation.

Crypto-focused lender Silvergate said it is winding down operations and will liquidate the bank after being financially pummeled by turmoil in digital assets.

“In light of recent industry and regulatory developments, Silvergate believes that an orderly wind down of Bank operations and a voluntary liquidation of the Bank is the best path forward,” it said in a statement Wednesday.

But the risks of broader contagion are thought to be limited for now.

“Overall, the banking system is in good shape and able to withstand significant shocks,” said Jens Hagendorff, a finance professor at King’s College London. “I think SVB is special in the sense that they have a fickle depositor base.”

The Dow fell by 345 points, or 1.1{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} on Friday. The S&P 500 dropped 1.5{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} and the Nasdaq Composite was 1.8{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} lower.

For the week, The Dow fell by 4.4{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b}, its worst week since June. The S&P 500 was down 4.6{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} and the Nasdaq was 4.7{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} lower.

Wall Street’s fear gauge, the VIX, jumped 15{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} on Friday afternoon as investors rushed to safe havens to avoid being pulled into any banking sector contagion, the markets team reported.

Democratic Sen. Elizabeth Warren called for authorities to come down hard on Silicon Valley Bank management in the aftermath of the historic bank failure, CNN’s Matt Egan reported. She is a strong supporter of strict oversight of banks.

“SVB executives must be held accountable for any malfeasance or mismanagement that led to this failure,” Warren said in a statement late Friday.

The Massachusetts Democrat said she is receiving regular updates from the FDIC, which seized control of the bank, which has 17 branches in California and Massachusetts.

“I expect there will soon be a better assessment of how much help is available for customers in Massachusetts and across the nation,” Warren said.


Silicon Valley Bank collapses after failing to raise capital

Silicon Valley Bank collapses after failing to raise capital


New York
CNN
 — 

Silicon Valley Lender collapsed Friday early morning just after a beautiful 48 hours in which its capital crisis established off fears of a meltdown throughout the banking business.

Its failure marks the premier shutdown of a US bank considering that 2008, when Washington Mutual fell through the money crisis.

California regulators closed down the tech loan provider and put it in handle of the US Federal Deposit Insurance Corporation. The FDIC is performing as a receiver, which usually signifies it will liquidate the bank’s belongings to pay out back its clients, together with depositors and lenders. The FDIC is an independent federal government company that insures financial institution deposits and oversees economical institutions.

The FDIC claimed all insured depositors will have total obtain to their insured deposits by no afterwards than Monday early morning, and it will fork out uninsured depositors an “advance dividend in the subsequent 7 days.”

The bank, previously owned by SVB Economic Team, didn’t reply to CNN’s ask for for remark.

When somewhat unknown outside of Silicon Valley, SVB was among the prime 20 American business banking companies, with $209 billion in whole property at the conclude of past calendar year, in accordance to the FDIC.

But SVB catered mainly to to higher-possibility tech startups that have not too long ago been harm by increased curiosity costs and dwindling enterprise cash.

The financial institution partnered with practically 50 percent of all enterprise-backed tech and well being care companies in the United States, quite a few of which pulled deposits out of the financial institution.

SVB’s shares were halted Friday early morning immediately after slipping extra than 60{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} in premarket investing. The stock tumbled 60{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} Thursday following the financial institution explained it experienced to market a portfolio of US Treasuries and $1.75 billion in shares at a loss to deal with swiftly declining client deposits — essentially facing a run on the bank.

Many other financial institution shares were being temporarily halted Friday, which includes Very first Republic, PacWest Bancorp, and Signature Lender.

On Thursday, as financial institution stocks all-around the planet fell in reaction to the disaster at SVB, contagion fears distribute on Wall Road. Hedge fund supervisor Invoice Ackman as opposed the circumstance at SVB to the last days of Bear Stearns, the very first financial institution to collapse at the start of the 2007-2008 world-wide economic crisis.

“The hazard of failure and deposit losses here is that the next, the very least very well-capitalized bank races a run and fails and the dominoes carry on to fall,” Ackman wrote in a series of tweets.

By Friday, several the panic appeared to simplicity. Bank stocks remained mainly down, but secure.

Mike Mayo, Wells Fargo senior financial institution analyst, reported the crisis at SVB may well be “an idiosyncratic scenario.”

“This is night time and working day vs . the worldwide monetary disaster from 15 many years back,” he instructed CNN’s Julia Chatterly on Friday. Back then, he reported, “banks ended up getting excessive threats, and people today believed almost everything was fine. Now everyone’s anxious, but beneath the surface area the banks are extra resilient than they’ve been in a technology.”

SVB’s sudden tumble mirrored other dangerous bets that have gotten exposed in the earlier year’s sector turmoil.

Crypto-focused loan company Silvergate claimed Wednesday it is winding down operations and will liquidate the lender immediately after currently being economically pummeled by turmoil in digital assets. Signature Financial institution, another crypto-helpful lender, was hit hard by the financial institution selloff, with shares sinking 30{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} right before becoming halted for volatility Friday.

“SVB’s institutional issues reflect a larger and much more widespread systemic issue: The banking industry is sitting down on a ton of low-yielding belongings that, thanks to the last 12 months of level increases, are now much underwater — and sinking,” wrote Konrad Alt, co-founder of Klaros Team.

Alt estimated that level boosts have “effectively wiped out approximately 28{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} of all the funds in the banking market as of the finish of 2022.”

When fascination prices were being in close proximity to zero, banking institutions loaded up on prolonged-dated, very low-danger Treasuries. But as the Fed raises curiosity rates to fight inflation, the benefit of people belongings has fallen, leaving banks sitting down on unrealized losses.

– CNN’s Matt Egan contributed to this report

Benin: African Development Bank, government and stakeholders explore strategies to boost the textile sector | African Development Bank

Benin: African Development Bank, government and stakeholders explore strategies to boost the textile sector | African Development Bank

The African Growth Bank Group’s country workplace in Benin held a workshop on the issues going through the country’s textile market and how to develop the potential of stakeholders to create price chains.

The workshop drew material producers, dyers, stylists, designers, embroiderers, seamstresses, people, help function specialists, and benefit chain pros, representatives of textile associations and federal government reps.   The aim was to comprehend the wants and anticipations of the textile producing ecosystem and to incorporate local actors into worth chains for mass-creation of textiles.

“This workshop fits perfectly into the dynamics of structural reinforcement of the textile business in Benin and the logic of consuming domestically created solutions,” claimed Dario G. Ebo Sacramento, Deputy Director of the Cabinet of the Ministry of Industry and Trade through the workshop. “This is a sector which offers many chances at all phases of the value chain. The venture for the industrialisation of small-scale clothes in Benin, proposed by the African Growth Bank, is section of the innovation motion with superior extra price for the Beninese purchaser, which the authorities is attempting to advertise within the Beninese business,” he included.

The African Development Financial institution Group’s Benin state supervisor, Robert Masumbuko, explained, “the workshop is a action to helping Beninese smaller and medium-sized enterprises to framework them selves and pool their endeavours to assist the dynamics set up by the Beninese authorities in favour of the advancement of the textile sector, via nearby mass manufacturing.”

 Robert Masumbuko, African Growth Financial institution Benin State Supervisor, defined that the workshop aimed to support Beninese small and medium textile enterprises enhance their structure. 


Non-public sector development is amid the bank’s priority areas in Benin for the 2022 2026 period. The aim is to help the transformation of agriculture and industrial development in the region.

“It is in the curiosity of all stakeholders in the Beninese garment business that the textile sector be ruled by worldwide norms and requirements so that generation is beautiful and meets the desires of local individuals as nicely as the more and more urgent desire which comes not only from outdoors the state but also from outside the house the continent,” said Nadia Adanlé, founder of Couleur Indigo, an indigo dyeing company which employs a the vast majority of people with disabilities. Adanlé is also a member of Benin’s Chamber of Crafts

According to the federal government, the country’s textile marketplace has the likely to grow to be one of the country’s main businesses. The regional current market is expected to expand remarkably in the coming decades.

In addition to accumulating qualitative info from stakeholders on the desires of private and community operators, the workshop also delivered an chance to suggest an substitute to importation of lower high quality garments and textiles.

In addition to the mass production of textile products and solutions, the expectation is that the initiative must also guide to the implementation of a mutually advantageous creation model that is accessible and economically financially rewarding for nearby individuals whilst also satisfying demand for exports.


Deutsche Bank tightens finance policy on coal, but not on oil and gas

Deutsche Bank tightens finance policy on coal, but not on oil and gas

FRANKFURT, March 2 (Reuters) – Deutsche Lender (DBKGn.DE) on Thursday tightened its coal financing procedures but has yet to improve its standards for the oil and fuel industries, drawing criticism from local weather activists.

Fiscal firms are underneath pressure from policymakers and traders to decrease the scale of local weather-detrimental carbon emissions linked to their lending and underwriting.

Germany’s largest bank reported it would not just take as new shoppers businesses that create much more than 30{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} of revenue from coal and that do not supply a “credible diversification program”.

The amount is down from a previous 50{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} and is far more in line with sector expectations.

The bank explained it will give existing clientele until eventually 2025 to persuade it of their potential to shift to reduced carbon small business types, and that, following that date, it will quit funding consumers who do not meet its conditions.

“Parting with a client soon after a transition dialogue can only ever be a past resort,” CEO Christian Sewing stated. “But in circumstances exactly where we noticed no willingness on the portion of a consumer to embark on a credible changeover, we would not shy away from exiting a romance.”

Hottest Updates

View 2 far more stories

The lender reported it already does not present venture funding for thermal coal and that its publicity to the sector at the conclude of 2022 accounted for .09{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} of its corporate financial loan reserve or 321 million euros ($340 million).

Shareholders and activists experienced termed on Deutsche to introduce similar limitations for oil and fuel, but the financial institution only said it “designs to update its oil and gasoline coverage” without having providing a timeframe.

All around 20 of Europe’s financial institutions have fully commited to phasing out funding for thermal coal ability or mining and numerous, such as NatWest (NWG.L) and HSBC (HSBA.L), have claimed they would similarly limit that for oil and gasoline.

Regine Richter, a campaigner at NGO Urgewald said the plan was “much too very little much too late” and the absence of update on the bank’s oil and fuel plan “is rather disappointing in the 12 months 2023 when all people can feel the effects of weather chaos”.

Deutsche Financial institution in recent many years has promoted by itself as a lender that companies can convert to as they move to a greener upcoming, a system it sights as central to its possess turnaround and boosting gains.

“We are nevertheless funding the industry, mainly because the planet economic climate is even now much way too dependent on fossil fuels,” Deutsche Financial institution Main Sustainability Officer Joerg Eigendorf said. “We acknowledge we need to have to adjust this quickly and are actively supporting our clients to transfer in the right way.”

Weather activists panic that the financial industry allows industries such coal and oil to carry on polluting, and claimed Deutsche Bank in particular has not carried out plenty of.

Deutsche explained its funding of the oil and fuel sector declined by a lot more than 20{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} last year, which it attributed to the bank’s exit from Russia and its cessation of assist for Russian gasoline firms as perfectly as motivation reductions for “chosen bigger clientele.”

This corresponded with a 28.9{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} slide in the carbon emissions affiliated with the bank’s lending to the oil and gasoline sector, however this was partly a consequence of mounting share rates, indicating that Deutsche’s overall share of funding and emissions fell.

The Worldwide Power Company said in 2021 that investment in new oil, gas and coal source jobs need to be halted to realize net-zero emissions by the middle of the century.

($1 = .9433 euros)

Reporting by Virginia Furness, Marta Orosz and Tom Sims, Enhancing by Friederike Heine and Barbara Lewis

Our Standards: The Thomson Reuters Believe in Concepts.