

Rural Oregon pharmacies fear closure without further health care industry regulation

Rural Oregon pharmacies fear closure without further health care industry regulation

Fewer competition has meant additional small business for little, impartial pharmacies, but retail outlet entrepreneurs say they’re nonetheless experiencing an existential disaster.

In late January, the Oregon Household Committee on Behavioral Overall health and Health and fitness Treatment held a listening to about a trio of expenses intended to regulate a cog in the treatment offer chain small recognized to most individuals: pharmacy gain professionals.

Acknowledged as PBMs, these corporations act as middlemen in between pharmacies, drug manufacturers and insurance corporations. Pharmacies count on PBMs to get the job done with insurers to provide reimbursements for the medicine they dispense, but pharmacies say that inadequate reimbursements and excessive fees are putting them at threat of shutting down for very good.

In Eastern Oregon, in which larger pharmacy chains are sparse, losing a pharmacy could imply losing the community’s, or even a county’s, only drug shop.

Representing her keep Murray’s Drug, Ann Murray manufactured the four-hour travel from Heppner to Salem very last thirty day period to make her scenario in entrance of the committee. She mentioned she started operating with the Legislature 10 many years ago to go PBM restrictions, but past efforts have not long gone much plenty of.

“Unfortunately, the legislation has not had the enforcement capabilities, and has remaining unchecked these monopolistic corporations that have swelled, merged and vertically integrated adequate that the expression pharmacy deserts is now frequent,” she said.

In composed testimony, her partner and co-proprietor John Murray was no less crucial of PBMs.

“Corporate greed is destroying yet a different strand of our excellent local community cloth,” he wrote. “It is a strand that if lost will charge us funds and wellness. PBM’s will try out to say our medications charges will raise if these expenses are passed, I simply call ‘bullshit.’”

A masked pharmacist is looking down, standing behind a counter that has three decorative jars full of pills that are layered by color.

Medicap Pharmacy workers pharmacist Ryan Baker in December 2021 works on prescription orders at this impartial pharmacy in Expertise, Oregon.

April Ehrlich / OPB

Rural pharmacies’ purpose in Japanese Oregon

Murray’s Drug originally opened in 1959 before Ann and John Murray purchased the pharmacy from his dad and mom in 1990. Murray’s Drug is headquartered in Heppner but also has places in Boardman and Condon, in addition to offering prescriptions to outlying locations like Umatilla, Irrigon and Arlington.

In spots the place smaller well being care units are now strained, pharmacies are important, Murray stated in an interview soon after the conference.

“Pharmacies in small towns in Jap Oregon, proven by the COVID pandemic, are actually the locations men and women go when folks will need assist. … We are the public’s most effective wellbeing care provider,” Murray reported.

Independent pharmacies say they are emotion the squeeze because of how PBMs get the job done with drug stores. Multiple pharmacy house owners advised the committee that PBMs normally reimburse medication bills at rates that either eat into their financial gain margins or trigger them to offer prescription medication at a decline. Moreover, PBMs can cost “clawback” expenses after the sale is done. With the PBM business dominated by a handful of companies hooked up to key pharmacy chains or coverage corporations, drug retailer owners explained they didn’t have a lot selection if they were unsatisfied with their possess PBM.

Pharmacies think the a few charges that had been launched this legislative session will assistance stage the taking part in discipline. Residence Invoice 3012 requires PBMs to report their expenses and drug rebate figures to the point out. Property Monthly bill 3013 would build a new posture in the Oregon Section of Shopper and Company Companies to control PBMs, who would also will need to sign-up with the office to keep on procedure. The package deal is rounded out by Property Bill 3015, which makes boundaries on reimbursements and clawback costs.

‘We’re on the verge of collapse’

Aid for these costs arrived from all throughout the point out and the Oregon State Pharmacy Affiliation, an industry lobbying team. According to information compiled by the affiliation, from 2008 to 2022 the range of pharmacies in Oregon dropped from 681 to 499. The lion’s share of the lessen arrived from unbiased pharmacies.

Jack Holt, the proprietor of a little chain of pharmacies in northwestern Oregon and southwestern Washington, mentioned he recently closed retailers in Veneta and Vancouver and is in the procedure of selling yet another. Holt pointed to PBMs as 1 of the explanations he’s experienced to deal.

The PBM sector did not take all the criticism with out pushback. Tonia Sorrell-Neal, a senior director of state affairs for the Pharmaceutical Treatment Administration Association, advised the committee that PBMs provide people rather than pharmacies. In accordance to the lobbyist, independent pharmacies are staying troubled by other economic issues and the business in general was stable.

“I’m not going to say a one bad factor about the pharmacies,” she said. “I like them. I want to sit at the table with them. And I want to be equipped to function with them to determine out what we can do to assist the entire situation.”

Brian Mayo, representing the point out pharmacy affiliation, did not look to watch Sorrell-Neal as a likely ally when he went up to discuss.

“I really don’t treatment what the PCMA lobbyist suggests, [the] pharmacy [industry] is not stable in Oregon,” he stated. “We’re on the verge of collapse.”

Rural communities will come to feel the issue acutely should they drop their pharmacies. Murray’s Drug serves an spot of 3,000 square miles. Tilli Slusarenko, a pharmacy supervisor at the John Day-dependent Len’s Pharmacy, who also testified in favor of the bills, stated Len’s is the only pharmacy in Grant County. If lost, John Day people would need to travel 70 miles to Burns to select up a prescription.

Numerous pharmacy homeowners also cited the reduction of Bi-Mart pharmacies as acquiring a enormous impression on their businesses. When the chain retailer obtained out of the prescription drug company in 2021, other area pharmacies experienced to select up the slack.

Lines at pharmacies acquired so negative in Baker County before this yr that a resident claimed men and women feeding on dinner in line and the county authorities regarded as selecting staff to wait around in line on behalf of seniors. A labor shortage for vital positions like pharmacy technicians has only exacerbated the problem in rural Oregon.

The prospective clients for the charges are boosted by their bipartisan guidance. The health and fitness treatment committee chair, Rep. Rob Nosse, D-Portland, is a sponsor. Three Japanese Oregon legislators — Rep. Bobby Levy, R-Echo, Sen. Monthly bill Hansell, R-Athena, and Lynn Findley, R-Vale — are also sponsors when Rep. Greg Smith, R-Heppner, voiced assist for the bills at the committee assembly.

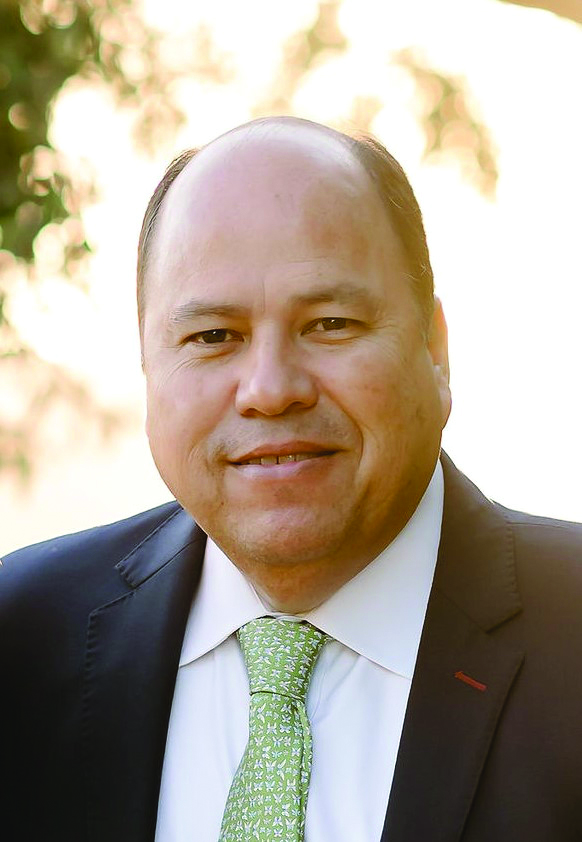
An inside look at the latest trends in housing regulation and policy, featuring the 2022 Vanguard Honoree, Armando Falcon

An inside look at the latest trends in housing regulation and policy, featuring the 2022 Vanguard Honoree, Armando Falcon

In this series of interviews, we focus on the men and women who are shaping the point out of housing at the major — the policy and regulation specialists. The FHFA and the GSEs are critical to painting the picture of today’s housing marketplace and marketplace tendencies. To help get rid of some gentle in this location, many of the 2022 HousingWire Vanguard honorees shared their insights on what’s happening at the federal amount that’s heading to have an affect on housing this 12 months and into 2023.

Armando Falcon, CEO at Falcon Capitol Advisors

Falcon_Armando-Regulation
Armando Falcon, CEO at Falcon Capitol Advisors

HousingWire: Which traits in housing regulation are you and your group most centered on as we move into 2023?

Armando Falcon: Hunting ahead to 2023, there are a couple of wide trends that we are focusing on. The to start with is the total enterprise transformation that is taking spot in the home finance loan field. This is the outcome of several forces: the Fed’s anti-inflation coverage the immediate deceleration in lending that’s resulted in a 40{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} fall in apps the growing cost of house loan generation, which has now damaged the $10,000 for every loan threshold and the continued push in direction of digitization in mortgage loan lending.

These are prime of intellect for my workforce, our purchasers and the sector. The second wide development is accessibility to homeownership and affordability. Dwelling rates have in no way been increased, pent-up desire stronger and housing stock tighter. These ailments are hard for even the average homebuyer, permit on your own minimal-earnings and minority consumers.

There is a increasing sentiment in the two the community and private sectors that more requirements to be completed to help people, specially underserved buyers, get ready for homeownership and to shut the affordability gap. We’re observing new power and new initiatives in this area at numerous house loan and housing businesses.

Similarly, massive lenders are expanding their ESG and social responsibility applications. The dedication is genuine, and we see it only acquiring much better.

HW: As a 2022 Vanguard honoree, what has been your proudest accomplishment?

AF: Is it alright to say that I am proud of building a consulting firm designed of some incredibly talented folks who are supporting the mortgage loan market adapt to a current market in changeover? That I’m proud of the part that they are playing in supporting modernize property finance loan generation and the secondary marketplace? Mainly because I am.

About the earlier 15 yrs, our team has developed to more than 50-moreover associates, several of whom have held management positions at leading loan companies, tech and details companies and mortgage loan companies.

It’s really hard to decide just a person project because we’ve had many interesting engagements recently: for instance, our do the job with Ginnie Mae on its Digital Collateral Method or the asset income program that we handle for HUD that has moved a lot more than 50{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} of these vacant homes to nonprofit companies for reasonably priced housing or the analytic get the job done we offer to the business individuals to enable them evaluate development on their ESG investments.

These engagements are assisting to make the property finance loan business far more productive and far more resilient, two objectives that I pursued as a regulator and carry on to emphasis on as a guide to the business.

HW: What major adjustments in federal regulation and legislative guidelines need to people be paying out extra interest to?

AF: As I talked about, there is a large amount of desire and momentum about the regulation of issues of affordability and inclusion in homeownership. It is a priority at FHFA, FHA, HUD and Ginnie Mae. These organizations are making an attempt to occur up with creative options to make housing more inexpensive and homeownership additional achievable.

There is practically a New Offer spirit at perform. We’re also seeing new marketplace-primarily based initiatives coming from the personal sector. 1 of the nation’s largest loan companies, for instance, has just announced that it is tests a new plan that will give zero-down payment mortgages with no closing expenditures to very first-time homebuyers in Black and Hispanic neighborhoods in five big towns.

HW: How has your knowledge as the director of OFHEO (now FHFA) affected your initiatives and management at Falcon Capital?

AF: The GSEs and Ginnie Mae have been evangelical in their aid of digital lending. Nowadays approximately 5{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} of all conforming home loans are eNotes, and all of the companies are on record encouraging loan providers to originate extra property digitally. Ginnie Mae has been accepting eNotes on a pilot foundation given that the beginning of the calendar year. In June, they expanded their Digital Collateral System, and they are now in the system of accepting new applications from eIssuers, eCustodians, and subservicers. This was an vital milestone in digitizing govt lending, which was roughly a $757 billion sector.

HW: Falcon Money often works with govt agencies in system management and regulation method. Is there one particular task or partnership that you are very pleased of in specific?

AF: Creditors see the value in offering their shoppers the similar variety of easy digital expertise that they come upon in other features of their life (e.g., banking, purchasing, transportation). They are also concerned that if they really don’t offer this experience, more substantial countrywide retail lenders will. This is why I think these initiatives will proceed even in the smaller, much more aggressive environment that the market is now facing.

Making electronic, somewhat than paper, assets offers increased cash industry efficiencies and lessens prices and mistakes. Latest ROI reports have revealed that eClosings and eNotes can help save originators roughly $400 per loan. That’s a major variety when you take into consideration that the ordinary originator misplaced $82 for every loan in the 2nd quarter, in accordance to the Mortgage Bankers Association.

This interview was at first posted in the Oct/November difficulty of HousingWire Journal. To perspective the whole concern, click here.