Why Created House Sector Customers Ought to Remark on the DOE Made Housing Electrical power Rule to Need its Hold off and Withdrawal Manufactured Housing Assoc Regulatory Reform MHARR.
MHARR is Defending The American Aspiration of Household Possession. MHARR Brings Shoppers, Industry Gurus, General public Officials and Media Prevalent Sense Alternatives Others May well Miss out on.
Manufactured Housing Association for Regulatory Reform (MHARR) Thoreau Quote – Image Collage of Present day HUD Code Manufactured Properties Infographic Compares Price tag Per Sq. Foot of New Standard Site Developed Housing vs New Manufactured Homes. (Click Picture to Grow.)
Made Housing Affiliation for Regulatory Reform (MHARR) Submits Regulatory Remarks-Urges Industry Associates and Manufactured Residence Advocates to Get Redo.
Key Troubles holding the manufactured property sector at very low ebb in the course of an reasonably priced housing crisis consist of the failure to completely and appropriately carry out present federal legislation.” – MHARRWASHINGTON , D.C., UNITED STATES, April 20, 2023/einpresswire.com / — The Manufactured Housing Affiliation for Regulatory Reform (MHARR) has issued the following statement to the media, sure community officers, and users of the made housing marketplace.
TO: HUD CODE Produced HOUSING Business Associates FROM: MHARR RE: WHY Created House Sector Users Have to Comment ON THE DOE Made HOUSING Electricity RULE TO Demand ITS Hold off AND WITHDRAWAL
As promised in its March 28, 2023 memorandum, entitled“DOE Delays Energy Rule – Sector Must Now Need Complete Revocation of Destructive Regulation,” connected for your information and facts and use, in full or in section, if you so want, is a duplicate of MHARR reviews to the U.S. Department of Electrical power (DOE) supporting not only a hold off in the enforcement of its May perhaps 31, 2022“final” manufactured housing“energy conservation” specifications, but, extra importantly, in search of as soon as all over again, the entire withdrawal of these specifications and DOE’s return“to the drawing board” to fully re-begin its criteria development system in full compliance with the specifications of each the Strength Independence and Stability Act of 2007 (EISA) and appropriate elements of the Manufactured Housing Advancement Act of 2000 (2000 Reform Legislation).
As MHARR has asserted and stated from the outset of the DOE rulemaking procedure, 15 many years in the past, DOE’s development of produced housing energy specifications has been and carries on to be in total defiance of the most important provisions of EISA – i.e., its price-reward mandate and, even far more importantly, its prerequisite for the enhancement of made housing electrical power benchmarks in whole cooperation, coordination and consultation with the two HUD and the statutory Produced Housing Consensus Committee (MHCC).
…
MHARR…strongly encourages all business associates to post comments (because of by April 24, 2023) to DOE addressing the two the delay of the implementation/enforcement day of the DOE produced housing vitality expectations, as well as the whole withdrawal of these inappropriate and illegal requirements merged with a return to the“drawing board” for a comprehensive and total“re-do” of the criteria in comprehensive cooperation, coordination and session with both equally HUD and the MHCC as essential by EISA and federal made housing legislation. In doing so, remember to come to feel cost-free to cite or reference MHARR’s connected responses.
MHARR will go on to intently observe this rulemaking which has particularly significant implications for the business and its shoppers.
Made Housing Affiliation for Regulatory Reform (MHARR) 1331 Pennsylvania Ave N.W., Suite 512 Washington D.C. 20004 Cellphone: 202/783-4087 Fax: 202/783-4075 E mail: Web site: manufacturedhousingassociation.org
The entire MHARR press launch is identified on their web page at this url in this article. It involves the MHARR comments letter to the U.S. Section of Electrical power (DOE) at the backlink beneath.
Prior MHARR reviews and remarks on the DOE Electrical power Rule problem are located at the backlinks under.
As MHARR has suggested field audience and fascinated get-togethers, the Manufactured Housing Institute (MHI) and the Texas Produced Housing Affiliation (TMHA) submitted go well with from the DOE and other named get-togethers to halt the development of the implementation of the DOE’s pending rule. That circumstance variety is Scenario No. 23-cv-00174 was submitted on 02/14/23 in the United States District Court for the Western District of Texas.
MHARR has also warned affordable housing advocates that present-day policies have resulted in the 5th straight month of produced housing manufacturing declines. The major known selection of several years of monthly manufactured housing marketplace manufacturing/shipment records are discovered in this article.
About MHARR
The Manufactured Housing Affiliation for Regulatory Reform is a Washington, D.C.-primarily based nationwide trade association representing the sights and pursuits of impartial producers of federally-controlled produced housing.
Hottest Produced Housing Sector News from MHARR
The greatest recognised collection on the net of made housing field focused information supplied by a manufactured home marketplace nonprofit focused on unbiased producers’ details and sights are observed at this connection beneath.
MHARR Troubles and Perspectives
MHARR Issues and Views are insider-insights and point-packed article content authored by MHARR President and CEO, Mark Weiss, J.D. A long time of “Troubles and Views” are identified at the url under. They routinely offer insights not found from other resources.
Assortment of MHProNews Q&As with Founding MHARR President and Present Senior Advisor Danny Ghorbani
Danny Ghorbani was a vice president for the Produced Housing Institute (MHI) ahead of leaving and starting to be the founding president and CEO of MHARR. Ghorbani’s vocation spans some 5 a long time and was regarded by the RV MH Corridor of Fame. He was an engineer and played a vital position in creating some 200,000 property web sites for manufacturing facility built cell property houses prior to the HUD Code made housing era. Individuals Q&A style interviews with Ghorbani are observed at this website link underneath.
Brief Historical past and Targets of the Manufactured Housing Association for Regulatory Reform (MHARR)
Main and Continuing MHARR Achievements for the HUD Code Produced Housing Market and Buyers of Economical Housing
Key Problems keeping the manufactured home market at reduced ebb in the course of an reasonably priced housing crisis contain the failure to fully and effectively put into practice current federal legal guidelines.” The Manufactured Housing Enhancement Act of 2000 and its ‘enhanced preemption’ provision is commonly seen by business professionals as not being adequately enforced by the U.S. Section of Housing and Urban Enhancement (HUD). Likewise, far more cost-powerful manufactured dwelling lending has been delivered for by federal law, but all those guidelines – in MHARR’s pro perspective – are not becoming appropriately enforced. See the mharr website for articles or blog posts on enhanced preemption .
Mark Weiss, J.D., President & CEO Created Housing Affiliation for Regulatory Reform +1 202-783-4087 email us right here Go to us on social media: facebook twitter linkedin youtube other
The study grants in-depth research into several factors, including constraints, opportunities, drivers, and trends, driving demand for insulation blow-in machines. It also delves further into key observations on growth parameters common in segments such as material, power type, product type, production rate, application, and regions.
Rockville , April 19, 2023 (GLOBE NEWSWIRE) — The global insulation blow-in machine market is set to record a valuation of US$ 500 million in 2023. Increased speculation about thermal and sound insulation in both residential and commercial buildings has led to rising insulation blow-in machine sales.
Global sales of insulation blow-in machines are expected to surpass US$ 990 million by 2033. The market is predicted to expand at a CAGR of 7{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} from 2023 to 2033.
Increased acceptance of insulation-blowing machines has led to surging use of environmentally friendly, inexpensive, effective, easy-to-install, and relatively high recycled waste materials. A few of these materials include cellulose, fiberglass, and rock wool.
With increasing do-it-yourself (DIY) and home enhancement tasks to fill attics, wall voids, and joist cavities, manufacturers would continue to move their focus to portable products. It is likely to help in creating new opportunities in the insulation blow-in machine industry.
Key players are estimated to add chemicals to loose-fill insulation to offer fire resistance properties for certain industrial applications.
Based on region, North America is expected to maintain its leading position in the insulation blow-in machine domain, with sales of over 10,000 units in 2018.
As traditional infrastructure wears out and new home prices rise, homeowners in the region are concentrating on home development and renovation activities, including blowing in insulation, thereby contributing to market expansion.
In East Asia, the construction business is growing exponentially. It is due to refining economic conditions, government initiatives involving infrastructure expansion, and high demand for living spaces.
Demand for insulation blow-in machines in the residential sector is projected to remain strong, accounting for a significant share in 2023. The ever-growing population looking for new spaces to stay can surge the need for insulation in new and prevailing wall voids & attics.
Blow-in insulation can also effectively reduce sound transmission between walls and deliver heat insulation. This property is further projected to accelerate energy saving and continue to drive insulation blow-in machine demand.
Key Takeaways:
North America is expected to dominate the market, accounting for more than 50{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} of revenue during the forecast period.
The United States is expected to emerge as the most remunerative country for insulation blow-in machine manufacturers.
Germany is expected to spearhead growth in Europe insulation blow-in machine market over the next ten years.
In terms of material, the cellulose segment is predicted to account for around 60{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} of revenue in 2023.
Based on application, the commercial category is anticipated to generate the lion’s share over the assessment period.
Growth Drivers:
Growing need for acoustic and thermal insulation in buildings to influence heating & cooling systems is set to fuel growth in the market.
Increasing funding in soundproofing and thermal insulation in commercial & residential buildings is projected to boost insulation blow-in machine sales.
Restraints:
Service providers are directing on renting rather than buying new gear as there is no one-size-fits-all blow-in available, which can limit the market.
Insulation materials in blow-in machines can create a lot of dust and debris, which might be difficult to clean up.
Key manufacturers in the insulation blow-in machine market are likely to profit from offering new insulation goods incorporating modern technology. These players are likewise focusing on expanding their production capacity to allow adequate production of critical end products.
Mergers, joint ventures, acquisitions, and partnerships are likely to be key growth strategies for manufacturers to gain a competitive edge.
For instance,
In December 2022, SEI Group LLC acquired Insulation & Fireplace Services, LLC, as well as its affiliates, namely, Affordable Energy Services, LLC and Finish Line Supply, Inc. The company’s footprint in important areas would be widened and strengthened as a result of this acquisition, further solidifying SEI’s position as a national player in the specialty goods and insulation markets.
In 2022, Rotobrush International, LLC joined hands with a renowned supplier of portable insulation machines named Intec. The collaboration would help both companies to create new opportunities for their clients.
Key Companies Profiled by Fact. MR
More Valuable Insights on Insulation Blow-in Machine Market
In its up-to-date research, Fact.MR reveals the factors projected to boost the insulation blow-in machine market over the estimated period (2023 to 2033). This study bids an in-depth study of the growth drivers and the challenges estimated to surge sales in the insulation blow-in machine market through segmentation as follows:
Key Questions Covered in the Insulation Blow-in Machine MarketReport
What will be the demand outlook for the insulation blow-in machine industry during the forecast period?
Which are the factors limiting the demand in the insulation blow-in machine industry?
Which region will lead the growth in the insulation blow-in machine industry from 2023 to 2033?
What is the projected valuation of the insulation blow-in machine industry in 2033?
Which are the factors driving the insulation blow-in machine industry from 2023 to 2033?
Which product type will generate the maximum revenue in the insulation blow-in machine industry?
Explore Fact. MR’s Coverage on the Industrial Goods Domain
Industrial Insulation Market: The industrial insulation market is projected to surge steadily, surpassing US$ 12.4 billion by 2031. Sales in the market topped a valuation of US$ 7.4 billion in 2021. Demand in the market is estimated to rise at a CAGR of 5.3{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} on the back of increasing application of ecological insulation goods in the power generation industry.
Insulation Tester Market: As the importance of electrical safety and preventive maintenance continues to expand, there is an increasing demand for insulation testers worldwide. This is due to their ability to measure the insulation resistance of electrical systems and equipment. It can help prevent electrical failures and reduce the risk of electrical shock.
Insulation Flanges Market: The key application of insulating flanges is in the insulation of cathodic protection systems. These flanges are lined with plastic to provide insulation, avert current flow, and avoid galvanic corrosion. These are used in transmissions or pipelines containing liquids. North America and Western Europe are projected to be the key markets for insulating flanges.
About Fact.MR
We are a trusted research partner of 80{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} of fortune 1000 companies across the globe. We are consistently growing in the field of market research with more than 1000 reports published every year. The dedicated team of 400-plus analysts and consultants is committed to achieving the utmost level of our client’s satisfaction.
Contact:
US Sales Office 11140 Rockville Pike Suite 400 Rockville, MD 20852 United States Tel: +1 (628) 251-1583, +353-1-4434-232 (D)
The “Dwelling Infusion Remedy Marketplace” was valued at US$ 21,765.95 million in 2022 and is predicted to arrive at US$ 35,696.05 million by 2028 it is approximated to file a CAGR of 8.6{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} from 2022 to 2028.
The escalating incidences of continual issues coupled with the mounting geriatric population, and the lowering period of hospital stays and the surging expense of care are driving the property infusion treatment sector development. Nonetheless, recalls of infusion pumps and security issues related with household infusion hamper the residence infusion treatment market place development.
Get a Sample PDF of report @: https://www.premiummarketinsights.com/sample/Tip00012592?utm_source=OpenPr&utm_medium=10688
Providers Profiled in this report involves:
• B. Braun Melsungen AG • Micrel Health care Gadgets SA • Baxter International Inc • Nipro Corp • Becton Dickinson and Co • Fresenius Kabi AG • ICU Health care Inc • JMS Co Ltd • Eitan Clinical Ltd • Terumo Corp
According to the National Home Infusion Association (NHIA), 3.2 million people obtain home infusion each and every calendar year, and 98{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} of these admitted are getting “pretty pleased” with their treatment. According to a examine by the NHIA in 2019, property infusion and specialty providers in the US served ~3 million sufferers in 2019, reporting a 300{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} maximize in their profits in the final ten years. House infusion imparts sizeable cost-price savings compared to a traditional medical center infusion location. Infusion delivered at household costs 50{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} a lot less than infusion supplied at healthcare facility amenities. In accordance to the posting published by Beckers Hospital in 2020, the average cost of home infusion is US$ 140-250 for each day, while the regular expense of medical center infusions is US$ 590 per affected individual per infusion. In accordance to the Commonwealth Fund, medical center-at-home applications aid to cut the value of treatment by around 30{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b}, executing remarkably properly in international locations with solitary-payer systems, this kind of as Canada, England, and Israel.
Get Total Report right here @: https://www.premiummarketinsights.com/studies-idea/household-infusion-remedy-current market
Dwelling Infusion Therapy Current market Segmentation:
By Route of Administration: • Intramuscular • Subcutaneously • Epidural
According to the Nationwide Home Infusion Affiliation (NHIA), 3.2 million individuals receive house infusion each and every calendar year, and 98{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} of these admitted are becoming “really happy” with their therapy. According to a research by the NHIA in 2019, residence infusion and specialty companies in the US served ~3 million people in 2019, reporting a 300{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} maximize in their product sales in the last decade. House infusion imparts sizeable price tag-savings when compared to a common medical center infusion placing. Infusion provided at property prices 50{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} significantly less than infusion delivered at medical center facilities. In accordance to the report posted by Beckers Clinic in 2020, the common price tag of residence infusion is US$ 140-250 for each day, whereas the normal value of clinic infusions is US$ 590 per individual for every infusion. In accordance to the Commonwealth Fund, hospital-at-home programs enable to slice the value of care by over 30{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b}, performing remarkably properly in countries with single-payer methods, these kinds of as Canada, England, and Israel.
Invest in this Report @: https://www.premiummarketinsights.com/buy/Tip00012592?utm_supply=OpenPr&utm_medium=10688
People requiring intravenous therapies in emergency departments can be shifted to dwelling infusion immediately after scientific assessment. The homecare plan incorporates robust clinical checking at household, which lets the early identification of more medical issues and the implementation of remedy plans to steer clear of readmissions. An Choice Treatment analyze of 124 dwelling parenteral nutrition (HPN) and 126 dwelling enteral nourishment (HEN) clients showed that dwelling infusion helps prevent hospitalization and enhances client treatment. Both equally HPN and HEN therapies can be quickly administered in hospitals, nonetheless ~40,000 HPN patients and 344,000 HEN patients annually receive their diet therapies at residence. Hence, a major reduction in the charge of care with a lessen in the duration of hospital stays, alongside with the escalating quantity of individuals availing homecare companies, fuel the property infusion remedy market expansion.
Other Stories:
Battery Screening Devices Industry Emerging Development Evaluation, Upcoming Demand and Business Possibilities 2028- https://www.marketwatch.com/push-launch/battery-testing-devices-current market-emerging-progress-investigation-future-need-and-business-prospects-2028-2023-04-20?mod=look for_headline
Gentle Control Switches Marketplace Essential Manufacturers Development Developments and Aggressive Investigation 2028- https://www.marketwatch.com/press-launch/mild-handle-switches-current market-vital-companies-advancement-trends-and-competitive-examination-2028-2023-04-20?mod=look for_headline
Speak to Us:
If you have any queries about this report or if you would like even more data, you should Make contact with Particular person: Sameer Joshi Telephone: +1-646-491-9876 Email: sales@premiummarketinsights.com
About Us:
Top quality Market Insights is a one halt store of marketplace study reports and alternatives to several providers throughout the world. We enable our shoppers in their choice assist process by encouraging them choose most appropriate and expense-powerful investigate stories and alternatives from many publishers. The marketplace investigation industry has improved in very last ten years. As corporate concentrate has shifted to market marketplaces and rising international locations, a number of publishers have stepped in to fulfil these information and facts desires. We have knowledgeable and skilled team that assists you navigate various options and allows you choose greatest investigate answer at most productive price. Premium Market place Insights has an considerable coverage of industry stories, firm reports and nation studies throughout all industries. In case your investigate requirements are not fulfilled by syndicated experiences offered by main publishers, we can assistance you by giving a custom-made analysis resolution by liaising with different investigation organizations saving your important time and money. We supply greatest in course consumer provider and our shopper support group is generally out there to support you on your exploration queries. Our determination to client service is very best exemplified by free of charge analyst support that we give to our clients which sets us apart from any other provider. We also provide business subscriptions which present substantial price savings to our clientele.
College STATION, Texas (KBTX) -Issues from labor shortages, offer chain difficulties and inflation are just some of the struggles house builders have long gone by way of given that the get started of the pandemic.
In spite of all that, gurus say the design market is displaying various indicators of development throughout 2023.
“I’m a 3rd technology residence builder,” explained Pitman. “My grandfather was a builder, my father, my uncle, my cousin, my stepfather. I have been doing the job in the company for 12 decades.”
Through the pandemic and past, Pitman explained his business has confronted a number of unprecedented difficulties.
“Never have I viewed it like in 2021 and 2022. The problem was, we had so substantially need locally. It set a ton of strain on our qualified trade employees so we did not have ample. So then, it took a whole lot of the time, meaning an prolonged period, to build a residence,” reported Pitman.
In 2023, Pitman reported the design procedure is seeking up.
“What we’ve observed in excess of the previous four or five months is costs for our expert labor type of flatten out. But, the major point we’ve viewed is the time it requires to do the undertaking, has come down. Immediately after the good deal is created, it can take six to 8 months to create a property. Which is in comparison to up to 12 months just not long ago,” mentioned Pitman.
Specialists say the development marketplace in the United States is predicted to mature steadily about the upcoming 4 quarters Increasing by 6.1{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} to get to $1,419,192 in 2023.
Yet another favourable Pitman stated was the availability of supply.
“The truth we can choose and have far more options in common,” reported Pitman. “I’m not declaring we really do not have complications. In the past 36 months, we have noticed the inflationary pressures appear in to variable on pricing. A large amount of the elements, even if they flattened or arrived down a very little bit, they are nonetheless very well previously mentioned wherever they had been pre-COVID,” reported Pitman. “But, price ranges of lumber ideal now are the most affordable they’re gonna go. I’d say the pricing is 30 to 40 percent more than pre-COVID-19.”
Keep Supervisor, Brent Cathey, told KBTX that rates for materials are still significant but have leveled out general.
“We observed file highs that we have in no way seen in the course of the pandemic,” explained Cathey. “Right now, we’re not at pre-pandemic pricing, but we’re fair across the marketplace. Lumber, panel merchandise, things of that nature have freed up tremendously. When we seem at some of our non-commodity products like windows or doorways, people have elevated for the duration of the top of the pandemic and haven’t lowered.”
As offer continues to improve, both equally Cathey and Pitman agreed on a very good outlook for the relaxation of 2023.
“We’re hopeful that developing carries on to improve and need stays robust,” mentioned Cathey.
“Interest costs have come down some. This is a actually good time for individuals to invest in simply because the future is unsure. Actually, all indicators lead to us acquiring a whole lot of action in the development current market,” Pitman claimed.
For more information and facts on Pitman Tailor made Residences, take a look at in this article.
While they may seem like outliers from the perspective of most providers in the country, publicly traded home health companies are often a great indicator of where the industry is – and where it’s going.
Whether they’re investing in new service lines or diversifying their revenue streams, the big providers on the block continue to change the home health industry at large.
Scott Fidel, an analyst at the private investment banking company Stephens, is part of a team that analyzes and evaluates those moves. He covers the post-acute space, as well as the managed care space.
Fiedel sat down with Home Health Care News on the latest edition of HHCN+ Talks to discuss Medicare Advantage trends, financial stability, home-based care M&A and a lot more.
The transcription of that conversation is below.
HHCN: Before we get going, Scott, I do want to get your background and a background on your company.
Scott Fidel: I’ve been a sell-side equity research analyst covering the health care services sector on Wall Street for the past 24 years or so. I focused on health care services for pretty much my entire career on Wall Street. The way that we break down our coverage is we look at three primary subsectors.
First, and very relevant for this conversation, is the post-acute care space — including all of the home-based care areas. We cover most of the publicly traded home health companies. Then we also cover managed care. That’s a sector I’ve covered very closely for the past quarter century. In areas like Medicare Advantage, for example, we’ve been covering that space for a long time.
I actually was a health care lobbyist for a while even before working on Wall Street where I had been involved with the whole Balanced Budget Act of ’97, and the transition of Medicare+Choice — ultimately leading to Medicare Advantage. Then we also covered the health care facilities, companies, acute care hospitals and behavioral health companies as well.
In terms of Stephens, the firm is one of the largest privately-held independent investment banks in the US. The firm has offices in the U.S. and Europe. The firm was founded in 1933 and provides a range of services to our clients, including equity research, investment banking, capital markets and capital management.
Given your scope of research and coverage, how are home-based care companies specifically faring right now compared to everyone else?
Let’s put that in context since the pandemic. It’s really been a tale of two different stories for this sector. The stocks actually started out the pandemic as real pandemic winners when we had the whole work-from-home-type analog trade in the market and with the expectation that the space would be a significant beneficiary of that.
Then, as the pandemic sustained itself, and a lot of the pressure started to build and when the broader investment climate deteriorated, the stocks faced more challenges. When we look at the overall aggregate period of the last three years, the post-acute home health sector has actually underperformed on the market. In managed care and health care facilities, that underperformance has been more weighted towards the last 18 months or so.
Within the sector, though, there’s been variation in generally what we see and companies focused more on personal care and home-based care outperform given how much better the reimbursement environment has been there. Whereas companies that are more levered to Medicare home health reimbursement, in particular, have been relative underperformers.
Then we’ve had all the consolidation dynamics, too, at play.
One of the things I love that Stephens puts out are the underlying drivers that dictate success in home health care. There are a few things that you’re measuring on a monthly or quarterly basis that generally are good indicators of the long-term and short-term success of these companies. Can you go into that a little bit? What are you tracking in order to see if these companies are on the right track?
For personal care, we focus on hours served and billable hours. On reimbursement for home health, we focus on their organic growth trends. It ultimately comes down to this home-based care tracker that we cover and it looks at a whole range of functions. It looks at home health admissions trends, reimbursement trends that we see in Medicare, Medicare Advantage trends and what we’re seeing in the episodic and non-episodic trends.
With personal care, we look at particularly billable hours and then the rate trends.
We also cover hospice in this as well. We’d look at a number of the variables that drive the hospice sector including things like hospice admissions, length of stay — which has been a big area of focus as well from the pandemic. Ultimately, what we’re trying to do with this product is determine inflection trends across these bottom-up metrics. And, while looking at the broader subset of all the drivers of the industry, trying to glean which companies are outperforming in particular areas.
What’s interesting is we do see a wide range of success factors across different companies in the sector. We put this out in our home-based care dashboard product where we look at all the KPIs. That’s just one of a lot of products that we publish.
A few examples. It’s interesting if we look at just home health to start with and look at same-store admissions trends. Going into the fourth quarter, we actually saw Humana — who had acquired the Kindred at Home asset and is now the largest home-health operator — actually show some of the strongest same-store admissions trends in the fourth quarter.
We thought that was interesting because Humana is now rolling out their value-based care program across the contracting structures for home health. They’re still relatively early into that phase, but that’s likely going to continue here into 2023 and into 2024.
When we look at some of the revenue generation statistics in terms of maximizing revenue opportunity — the Pennant Group — which is the spinout from Ensign, has actually shown quite strong performance when we look at things like revenue per admission and revenue per day on the hospice side. That company has actually been effective at realizing the revenue opportunities, particularly as we transitioned into the PDGM model and away from the former Prospective Payment System for home health.
Then if we look at the personal care, I would say that some of the themes have been consistent across operators. If we look at the rate trends, generally, they’ve been pretty robust across all the companies that disclose these metrics. We tend to look at Addus.
Modivcare, as well, has become a meaningful player in that market. Amedisys has traditionally disclosed some of these metrics but now they’re actually divesting that asset.
On the hours side, in terms of the volumes, what we’ve seen is that it’s been constrained because of the challenges in hiring caregivers, but it does feel like we are on the cusp now of starting to see those volumes start to inflect more positive for these companies starting in the fourth quarter. We think that will likely continue into the first quarter and then continue to improve in 2023.
Are you surprised at all by Humana’s effectiveness with CenterWell this early? Is that something that you thought may take a little bit longer to get going, or just because of how established Kindred was, how established Humana is as a company, is that something that’s not as surprising?
It’s not too surprising for us just because of how deliberate Humana really was around the process of ultimately acquiring Kindred at Home, which is now a centerpiece of the CenterWell brand and broader clinical platform that Humana continues to build. Remember that Humana had a long-term investment in the platform and they really spent a couple of years deliberating on whether they would be able to successfully create value by acquiring the asset and rolling out the value-based care platform.
Now, clearly, the backdrop has gotten that much more challenging since they acquired the asset with the pressures that we’re seeing with add-on expenses – on wages, on reimbursement and on volumes. With Humana, we are seeing them committed to that rollout. Also, they’re going to be taking on a larger piece of the spend as part of this. It actually helps them enhance the revenue picture, too, in terms of the partners that they’re working with.
We really think that tracking Humana in terms of how they’re performing on this rollout of the value-based care initiative in home health is going to be really insightful for the rest of the industry because, clearly, right behind them we have UnitedHealth and Optum. Now having acquired LHCG, we’re going to be very interested in whether Optum and United roll out a similar model for LHCG or take a bit of a different track.
That’s the conversation that we’re having about UnitedHealth and another company that we cover as well. Clearly, the focus on value-based contracting and on Medicare Advantage contracting is a huge area of focus right now and critical for home-based companies.
What will another rate cut mean for these companies given that it had made them underperform recently? It’s obviously something that’s baked into how people are viewing these companies right now, but at the same time, it’d be yet another cut. Obviously, that’s going to be a challenge for them. How do you feel about how that’s going to affect them, short and long-term?
It’s the biggest single overhang in the public investor community right now around the home health companies and it’s frustrating because CMS clearly utilizes a meaningful level of lag data in terms of how they conduct their analyses. The real-world inflation has clearly accelerated. We do understand that CMS, even more recently in some of the stakeholder interactions, hasn’t seemed to reflect that they are fully recognizing or sympathetic to the idea that this will be a major challenge and affect access to care.
We can see, in the volume trends that these companies report, that it is really constraining the ability to hire more skilled nurses. This is something with CMS that can often be a bit frustrating — and with payers in general — is where they’ll speak to certain policy objectives that are core to their view on advancing the health care system, and making for a more efficient and productive health care system. But then they do things with reimbursement that don’t seem to be aligned with that.
To boil it down: while there is a lot going on across all three of these subsectors, what CMS does with the 2024 home health rates is most likely going to be the single largest determinant of investor sentiment, and then also of investment in general. It’s important, putting aside just the publicly traded stocks, how things like the M&A environment will be dictated.
For example, just yesterday I spent the day hosting investor meetings with the Addus management team. They have been a successful, consistent operator. They operate in all three of these markets. Home health for them is relatively smaller. It’s only around 5{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} of their revenue. With that said, it is an area they wanted to deploy capital to grow that business through acquisitions, but clearly, they’re going to be very disciplined right now and prudent around engaging in deals focused on home health until we have that clarity on the reimbursement. And again, how that influences the valuation dynamics too where the publicly traded companies have been under the microscope for a while.
A lot of these stocks have been substantially pressured. The valuation multiples have come down quite meaningfully since their peaks during the earlier part of the pandemic, but on the sellers’ side, I think a lot of these sellers are still holding on to some of the memories of where deals were getting done and that’s creating friction in the market right now. That’s going to have to work itself out.
Hospice is another good example of that where we had a tremendously active deal environment for a number of years. Really, hospice was the tip of the spear in terms of M&A activity with strategics and with private equity, too. Valuation multiples have gotten very rich, but hospice fundamentals themselves have been more pressured over the last 12 to 18 months with a variety of headwinds from the pandemic.
That’s affecting margins, and that’s affecting EBITDA for these companies, and that’s another area where it feels like the pace of activity has frankly slowed quite significantly from where we were 12, 18, 24 months ago.
Because of those Medicare fee-for-service conditions, how important do you think it is for these companies to be successful in their negotiating with Medicare Advantage payers moving forward to offset some of those cuts to make sure that the financials are stable as they take on more beneficiaries in MA?
It’s central to the story and to the strategies. It’s absolutely critical. Separate from even if the Medicare fee-for-service reimbursement environment hadn’t suddenly gotten so stunted, the long-term structural trend in Medicare is still towards a significant long-term movement into Medicare Advantage. The numbers are simple right now, right? We’ve just pretty much eclipsed 50{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} or half of the overall Medicare market being in Medicare Advantage.
When I started covering the managed care stocks after the Balanced Budget Act of ’97, we had dipped into the low-teens percentage. I’ve watched this go from 12{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b}, 15{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} to 50{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} in, let’s call it, a little bit over 20 years. And the Medicare Advantage space is still growing 7{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} to 9{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} annually, and Medicare fee-for-service is barely growing. Now, when you add on the variance and the margin profiles, the economics where you look at many of these Medicare home health companies, maybe they’re reporting 12{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b}, 13{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b}, 14{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} adjusted EBITDA margins.
Inside of that, you have Medicare fee-for-service business with margins substantially higher. MedPAC tries to argue that the margins are in the low 20s. I’m sure the industry would push back on that, but they’re clearly higher than the consolidated average. Medicare Advantage is barely profitable for a lot of these companies with single-digit margins to begin with. Ultimately, the economics need to balance out between Medicare fee-for-service and Medicare Advantage. It’s as simple as that.
I have these conversations on both sides of the negotiating table. I cover the home health companies and I cover all the managed care companies too. I do find it very interesting that the managed care companies across the board, when they talk about their key long-term mega themes in health care, obviously value-based care is an enormous one, but the shift to the home is a theme that all these companies emphasize over and over again in their investor presentations to investors and in their discussions with the market and with analysts. Yet we always hear from home health companies about how terrible the reimbursement is in home health.
I think, ultimately, there’s going to have to be some shaking out and some achievement of more of a balance here. It does feel to me right now like the economics are inordinately skewed toward MA, relative to home health in this particular area. Remember, the other challenge that we’re going to have to remember is out there. And that is that the Medicare Advantage companies themselves are going to be facing a tougher reimbursement climate.
In the last couple of years, CMS has given the MA companies unusually strong reimbursement updates and it’s still been really tough for home health companies to get proper reimbursement. Now the MA companies are looking at much tighter reimbursement, a new risk model that’s being implemented that is going to create a lot of complexity, and at the same time, the home health companies have to even negotiate more furiously for higher reimbursements. That’s a story we’re going to be tracking, but it’s uncertain exactly what the end result is going to be as we look out to 2024 and beyond.
It’s interesting to see, it could go two ways. Obviously, home health providers are hoping that those MA plans will react to that by saying, “Hey, let’s put more money and more focus on the home-based care side of things to control post-acute spend,” but they could also say, “Hey, we’re getting less. That means you’re getting less.” It’ll be interesting to see that dynamic play out.
Yes, absolutely. Ultimately, we need to remember that when you’re shifting a care consumption or utilization into the home, it drives substantial savings for Medicare Advantage plans, relative to being in a SNF or relative to being in an ERF or clearly, being in an acute care facility.
At some level, I do scratch my head sometimes around why MA plans are being so difficult on reimbursement to home health when in the overall scheme of things, that’s not a lot of money, relative to having patients end up staying in a facility.
This also comes down to how fragmented the home health industry is and the difficulties for a lot of home health agencies to really distinguish themselves with MA plans as not just being commoditized, right? Ultimately, value-based care is an area that could separate that dynamic. That is something that probably the more highly scaled companies are able to, on the home health side, participate in more because there is a significant investment in complexity, separate from the regulatory complexity that we’re dealing with that’s being pushed on the industry by CMS. That’s probably a theme that ultimately would drive more consolidation over time.
There’s a lot of debate right now, too, around how this consolidation will play out. Because we’ve got larger home health companies wanting to acquire smaller ones, but there’s this friction around multiples and around deal valuations right now. Then, obviously, you have the Medicare Advantage companies just taking out some of these largest players, too. Remember, they’ve got that leverage dynamic, too, with Medicare Advantage as well, whereas a Humana takes a Kindred as a subsidiary, and United takes on LHCG as a subsidiary — they’re going to want to ensure that the economic future for those subsidiaries is positive and emphasize that opportunity.
They have folks like us writing reports on them every quarter, evaluating them on that. It also raises the point of whether, at Humana or United, how much more interested are they going to be in raising reimbursements right now for these other operators out there when they need to focus on maximizing the value of these assets that they’ve recently acquired.
How was the event with Addus yesterday? Was there anything else that you gleaned from it that you maybe had not considered prior it?
I always enjoy catching up with the Addus management team. I think that they have a long track record of disciplined operation in the industry. They’ve been through the home-based markets in both easy and difficult times. They’re very prudent. Particularly, we see that with their balance sheet, for example, they’ve kept their debt leverage very low. That’s something that their stock has been rewarded for, relative to some of the other stocks with higher leverage, given the market’s focus on rising interest rates and liquidity, essentially.
With Addus, on the M&A side, I think they are eager and ready to do transactions. They’ve talked about wanting to focus a bit more on the personal care, which is their core market, and home health as compared to hospice, where Addus had been very active on the M&A front for a number of years in terms of building out that platform. They want to be very disciplined as well on the acquisition side. Separately, they do think that the reimbursement outlook will remain solid, actually looking at even 12 to 24 months for personal care because of the current positions of the state budgets, which have been favorable.
We’re going to be watching that area, frankly. Clearly, investors are going to be focused on whether or not the economy does flow. What that means for state budgets and what that means for reimbursements as well.
I do want to also mention redetermination. The return of that, which just kicked off four days ago, is a huge area of focus for investors, but it is less relevant — frankly — to personal care companies and to home-based companies in general because the clients and the patients that they serve tend to be polychronic dual-eligible-type patients who are just eligible for core Medicare or Medicaid services.
That doesn’t have to do with normal Medicaid eligibility based on income levels. We cover the managed Medicaid companies, for example, where this is a big area of focus but we’re not expecting that particular issue to be really much of a headwind at all for the personal care companies.
Do you think the home-based care companies on the public market reflect the rest of the industry?
I think that you already named a few of the attributes that are important, but it really sets the overall tone for thinking about both some of the investment considerations as it relates to things like sentiment and valuation, and then also how the market is thinking about evolution in the operating environment. Clearly, from the sentiment perspective, much of the market is going to be at least referencing what is happening with the stock prices and valuations of publicly traded companies.
It’s the most visible and constantly evolving valuation metric to reflect all the latest information in the market. When you think of investor sentiment, many of the large investors are talking to the publicly traded companies, and that’s dictating their overall sentiment in the industry. Then when we think about the operating environment. These companies do tend to have higher margins and more ability to generate free cash flow, which they can then use to invest to try to adapt to how the market is evolving. So whether it’s with Medicare Advantage, whether it’s with value-based care, investing in programs to do that.
I think a clear example of this would be Amedisys acquiring Contessa, which clearly has also had its challenges. I think Amedisys would be the first one to admit to that in terms of the ramp-up of that business. When you think about trying to create a new category within the space by moving more into those hospital- and SNF-at-home-type programs, you need a lot of capital to do that, though.
Frankly, Amedisys has spent a lot of capital, both on what they pay for it and the losses that they’ve invested in to build that business. A small company is not going to be able to do that, but ultimately if the market moves there and that becomes part of the core package of what these companies do, they’re going to have to adapt as well.
There were a lot of rumors about a few home-based care companies going public in 2020 and 2021. Since then, a lot of those rumors have subsided, probably because of those macroeconomic trends that are affecting the entire economy. Do you expect any more home-based care companies to be go public in the near-term future?
Good question. I think that in the near future, the market is still licking its wounds, frankly, from the IPO cycle of 2021. There were a lot of health care services businesses that hadn’t really proven profitability, and they have struggled mightily.
The main one that happened directly in this area was Aveanna, which has struggled, too, with some of these pressures — clearly with both their stock price and also with some of the changes in the fundamental environment. Clearly, the overall market environment is going to have to improve. Then, there’s the bottoms-up-type dynamics that we’ve just spent the last 35 minutes talking about.
If I had to assign a higher weight to a couple of those, I do think that on the home health side, clearly, the investor community getting more conviction on Medicare reimbursements, both for fee-for-service and for MA, is going to be key. Investors are going to want more clarity on that.
Personal care — frankly — that’s been an area where it’s been a bit more stable. More recently, obviously, there are areas to monitor in terms of potential headwinds if the economy slows, but there’s a little bit less controversy right now around the reimbursement dynamics. Again, that’s always the rearview mirror. One thing we’ve always seen is the pendulum swing back and forth around reimbursement, for sure with payers, and particularly with CMS.
CMS tends to overshoot on reimbursement cuts and then will come back and ultimately put corrective reimbursement in. That creates a positive reimbursement cycle. Then the market, both the industry and investors, think that’s going to be sustainable forever and maybe the sentiment gets overinflated. Then, CMS comes and pulls the rug out from underneath everybody and we wash and repeat.
Ultimately, we think that’s going to happen again, most likely. Clearly, if margins get pressured and that data on a lag basis starts to catch up to CMS, we will start to see better reimbursements and that could reopen that opportunity for more active public investing of some of the companies that are still private in terms of opportunities to go public.
I do want to ask you before we go, a prediction that you might have about the home-based care industry at large?
In terms of the under-the-radar screen, I don’t know about that because we try to keep everything above the radar screen as much as possible. I would say that as we just talked about, the centrality of the focus will be on these reimbursement trends. On some of the policy dynamics, there have been some proposals to really invest more in the home-based care area that Biden had proposed, for example, that ultimately didn’t come through.
I’m going to bring it back to something that’s not so spicy, but I think that ultimately, it does come down to having the actual frontline personnel to actually deliver these services. When you look at really the crux of everything, reimbursement has been key, but the other issue has just been around the labor dynamics and it’s been around whether it’s skilled or unskilled.
If I had a prediction to give you there, it does feel like the environment — from the hiring perspective — probably will get better more quickly in the unskilled area. That does tend to be more directly correlated with the overall economic cycle and with the labor market. I would be surprised if we don’t see personal care companies, for example, start to be able to improve their hiring right as the unemployment rate starts to rise.
I think there will also be some level of correlative benefit for skilled workers as well. When the economy gets tougher, nurses that have been sitting out for a while may come back into the workforce, but we still also have the long-term structural constraints that we have around nurse staffing and clinical staffing shortages. That’s going to be an issue for a long, long time to come.
It’s been something that we’ve been focusing on really the whole time I’ve covered the space. I think 10 years from now if we did the same type of talk, we’d still be talking about some of the structural challenges that we’re facing in staffing. Especially as we even have more seniors to care for in the future.
North East-based mostly treatment company Hark Team Holdings has reported it is trying to find to go on to expand through acquisitions as it capitalises on fragmentation in the Uk care sector. Above the last yr, acquisitions have helped the enterprise to treble in dimensions.
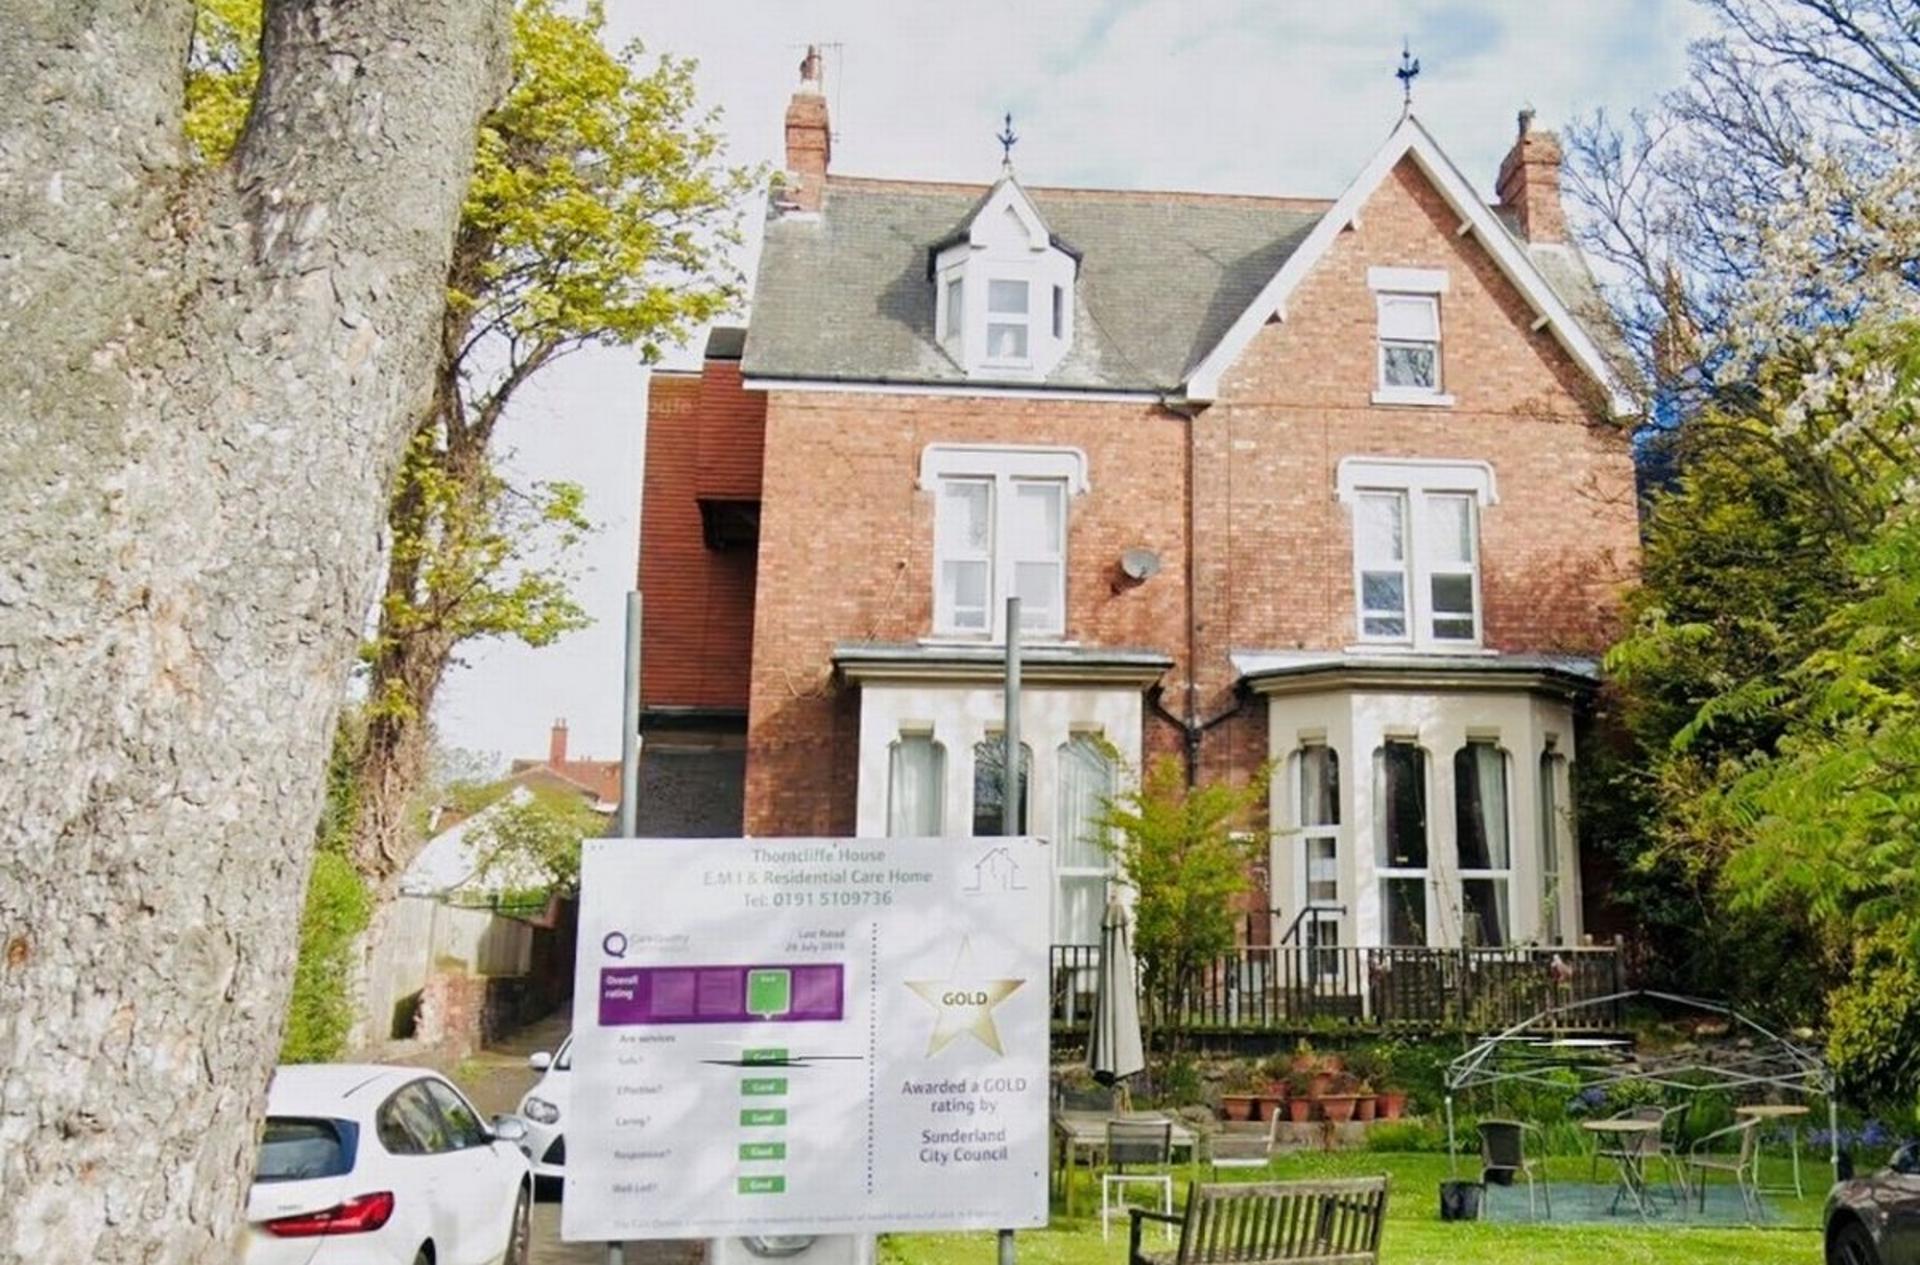
In the previous 12 months, the company has acquired the small business and belongings of Sunderland treatment house Cedar Dwelling, as properly as the entire issued share money of Thorncliffe Care Minimal, which operates the Thorncliffe Property treatment house in Sunderland (pictured higher than).
Hark Group labored with Mincoff Solicitors and accountancy and company advisory Azets on the discounts, with funding furnished by Allica Financial institution. The group’s leadership suggests it is aiming to function with both of those Mincoff and Azets on long term M&A specials.
Hardip Kang, director and owner of the Hark Group, who established the enterprise with his spouse Rupinder Kang, commented: “Our growth and advancement this past yr was significantly assisted with the know-how, knowledge and eye for depth from Chris Hughes and all the team at Mincoffs.”
“It is really the type of reassurance a rising organization needs when seeking to realize their expansion targets. Lee Humble and the workforce at Azets offered me with the economic tips and aid to speed up the momentum desired to get the offer more than the line. I look forward to doing the job with equally all over again for any doable upcoming acquisitions.”
Mincoff Solicitors Corporate Spouse Chris Hughes mentioned: “It has been great to perform intently with the two Hardip and the workforce at Hark and with Lee and the crew at Azets to provide Hark Group Holding’s vision for the North East care sector.”
“Thorncliffe Household and Cedar Property Treatment Residence are amazing additions to Hark’s portfolio and it has been a enjoyment to assist the group in acquiring these two business enterprise, so it can keep on to present essential, leading quality, treatment across the location.”
Azets Corporate Finance Partner Lee Humble extra: “It has been a pleasure to do the job with these kinds of a strong crew with a compelling development eyesight. I am enthusiastic to see what the potential retains for the Group, and we are delighted to be portion of their journey.”
Fragmentation and a large number of owner exits because the COVID-19 pandemic have driven a growth in dealmaking in the care sector and Lee Humble noticed: “The sector is incredibly energetic at current, and we are usually eager to support aid transactions for enterprises like Hark.”