After banking crisis, the housing market faces even more uncertainty

After banking crisis, the housing market faces even more uncertainty

New info from the National Affiliation of Realtors confirmed a 14.5{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} raise in household gross sales in February, a big increase relative to anticipations.

Current residence product sales have gone down continually each individual thirty day period for an full calendar year now. Stock has also been at historic lows. Even though today’s facts might be good information for the market, it comes versus a clean backdrop of financial institution collapse and standard recession stress.

Robert Padilla and his wife Patricia have been on the lookout for a house to get in Santa Fe, New Mexico, for about a calendar year.

“It’s just the two of us, but we have family that we’d like they arrive down to visit us,” Padilla mentioned. “So we needed a a few bed room, two bathtub.”

But there hasn’t been much to seem at in their cost vary — which is about $350,000. Padilla is effective as a stability guard for general public educational institutions. The properties they’ve observed have been disappointing.

“The roofs are leaking,” he claimed. “They’ve experienced animals dwelling in there. chickens. I necessarily mean we just cannot do that.”

If home loan rates had been lower, Padilla states they’d be equipped to glimpse at nicer residences. Rates have appear down from their substantial of a lot more than 7{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} past November. But with premiums about 6.5{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b}, getting is out of get to for many residence buyers.

It is all a little bit of a unfavorable suggestions loop amongst buyers and sellers, claims Selma Hepp, main economist at CoreLogic.

“Both sides assume it is a negative time to acquire and it is a negative time to market,” Hepp said. “And so both of those are sitting down on the sidelines.”

According to her, this trend has been worsening. “Both attribute it to better mortgage loan charges,” Hepp explained.

And now there’s the uncertainty of a banking disaster to element in. “A whole lot of the expectation is that home finance loan charges may perhaps once more go up, and that we will see a tightening of lending ailments,” she claimed.

Hepp also details to shopper sentiment staying minimal as an obstacle. Logan Mohtashami, a guide analyst for HousingWire, agrees.

“A pal of mine that performs in the lending sector, explained to me that a homebuyer just took all the funds out of out of their financial institution, because they had been fearful that the bank was gonna go underneath,” Mohtashami said. “They said, ‘We never want to even acquire a home, we just really don’t want to shed our cash.’”

But Mohtashami and other analysts do see a flicker of hope for the housing market heading ahead.

“Rates may perhaps lower even more in the coming months dependent on reactions to the money market place,” stated Nadia Evangelou, a senior economist for the National Affiliation of Realtors, the team that releases the month-to-month property sales stories.

Evangelou stated she is cautiously optimistic mainly because contract signings rose noticeably for the 2nd straight month and which is a fantastic indicator for home revenue. But like quite a few analysts and would-be household customers and sellers — she’s keeping her breath for the federal reserve’s up coming shift.

There is a great deal happening in the entire world.  Via it all, Marketplace is right here for you. 

You rely on Marketplace to crack down the world’s functions and convey to you how it influences you in a truth-primarily based, approachable way. We rely on your money guidance to continue to keep making that attainable. 

Your donation nowadays powers the independent journalism that you rely on. For just $5/thirty day period, you can enable maintain Market so we can hold reporting on the issues that make any difference to you.  
Demand for Fed help shows the banking industry is still under pressure

Demand for Fed help shows the banking industry is still under pressure

What caused the global banking crisis this week and will it lead to a recession?

What caused the global banking crisis this week and will it lead to a recession?


London
CNN
 — 

Last Friday, the biggest failure of a US bank since the global financial crisis was playing out in real time as a major lender to the tech industry succumbed to a classic bank run.

Silicon Valley Bank’s customers were frantically pulling their money from the California-based lender before US regulators intervened to take control. But the collapse panicked markets, piling pain on weaker financial institutions already struggling with the unintended consequences of soaring interest rates and self-inflicted wounds.

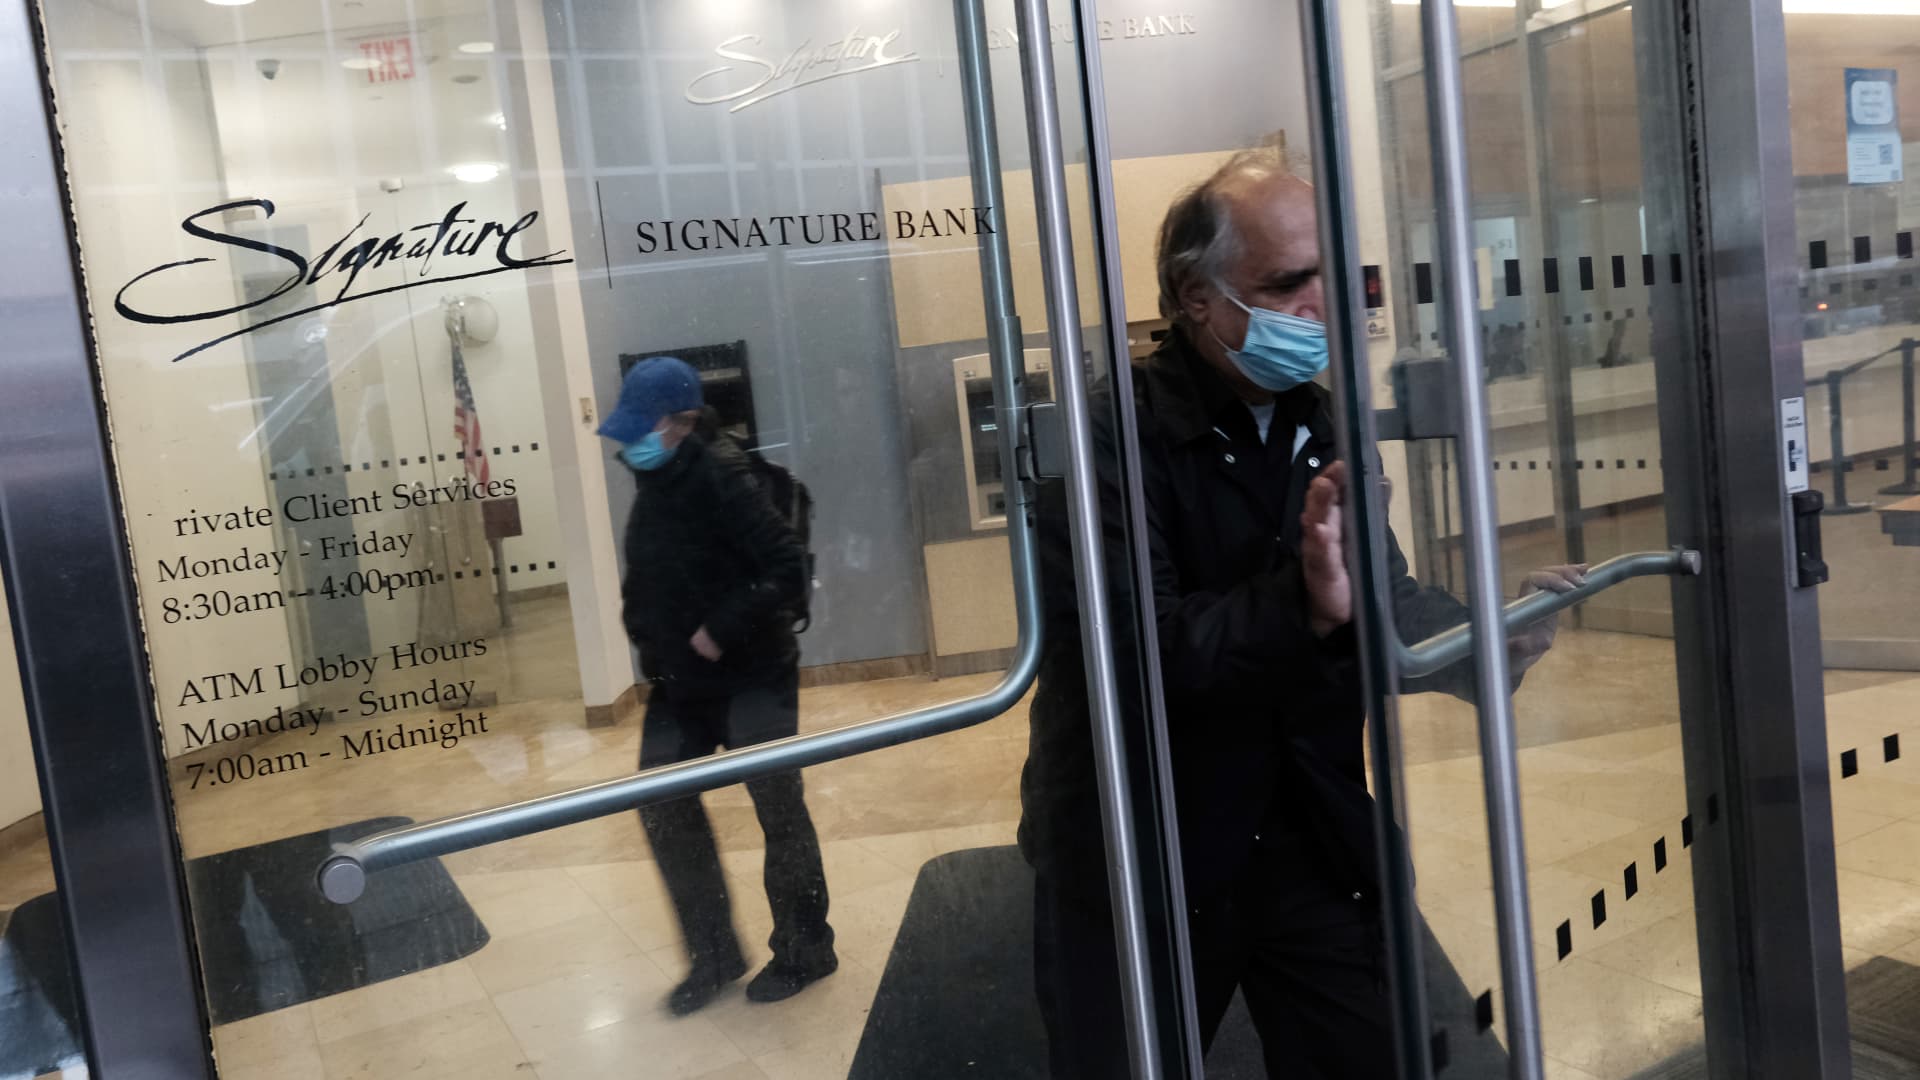
A week on, a second US regional bank — Signature Bank — has been shut down, a third — First Republic Bank

(FRC)
— has been propped up, and the first major threat since 2008 to a bank of global financial significance — Credit Suisse — has been averted, at least for now.

But the relative calm has been restored only thanks to the provision of huge sums of emergency cash from lenders of last resort — central banks — and some of the industry’s strongest players.

Markets remain on edge: Benchmark indexes of shares in US and European banks have lost 20{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} and 13{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} respectively since the close of trading last Wednesday. Wall Street opened lower Friday, and First Republic’s shares tumbled by about 16{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b}.

Friday, March 10 — The US government’s Federal Deposit Insurance Corporation (FDIC) took control of SVB. It was the biggest banking collapse in America since Washington Mutual in 2008. The wheels started to come off 48 hours earlier when the bank took a multibillion-dollar loss cashing out US government bonds to raise money to pay depositors. It tried — unsuccessfully — to sell shares to shore up its finances. That triggered the panic that led to its downfall.

Sunday, March 12 — The FDIC shut down Signature Bank after a run on its deposits by customers who were spooked by the implosion of SVB. Both banks had an unusually high ratio of uninsured deposits to fund their businesses.

Wednesday, March 15 — After watching shares in Credit Suisse

(CS)
collapse by as much as 30{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b}, Swiss authorities announced a backstop for the country’s second-biggest bank. It calmed the immediate market panic but the global player is not out of the woods yet. Investors and customers are worried that it doesn’t have a credible plan to reverse a long-term decline in its business.

Thursday, March 16 — First Republic Bank was teetering on the brink as customers withdrew their deposits. In a meeting in Washington, US Treasury Secretary Janet Yellen and Jamie Dimon, the CEO of America’s biggest bank, drew up plans for a private sector rescue. The result was an agreement with a group of American lenders to deposit tens of billions of dollars of cash into First Republic to staunch the bleeding.

Nearly $200 billion so far in direct central bank support. In guaranteeing all deposits at Silicon Valley Bank and Signature Bank, the US Federal Reserve is on the hook for $140 billion. Then there’s the $54 billion the Swiss National Bank offered Credit Suisse in the form of an emergency loan.

The Fed has also agreed record amounts of loans to other banks this week. Banks borrowed nearly $153 billion from the Fed in recent days, smashing the previous record of $112 billion set during the crisis of 2008.

Banks also drew on nearly $12 billion of loans from the Fed’s new emergency lending program established at the start of the week with the aim of preventing more banks collapsing.

The $318 billion the Fed has loaned in total to the financial system is about half what was extended during the global financial crisis.

“But it is still a big number,” said JPMorgan’s Michael Feroli in a note to investors Thursday. “The glass half-empty view is that banks need a lot of money. The glass half-full take is that the system is working as intended.”

The banking industry has also coughed up billions. JPMorgan Chase, Bank of America and Citigroup are among a group of 11 lenders providing the $30 billion cash infusion aimed at shoring up confidence in First Republic Bank.

HSBC has reportedly committed more than $2 billion to SVB’s UK business, which it bought on Sunday for £1.

If you have less than $250,000 in an account at a US bank insured by the FDIC, then you almost certainly have nothing to worry about. Joint accounts are insured up to $500,000.

European countries operate similar programs. In Switzerland, up to 100,000 Swiss francs ($108,000) is insured per depositor.

Customers of failed banks in the European Union are promised €100,000 ($105,431) of their deposits back. Joint account holders can receive a combined €200,000 ($210,956) in compensation.

In the United Kingdom, depositors can have up to £85,000 ($102,484) returned if their bank goes under, doubling to £170,000 ($204,967) for joint accounts.

The short answer is yes. Stressed banks will pay much greater attention to the creditworthiness of borrowers, whether they’re businesses looking for loans or home buyers trying to find mortgages.

“If banks are under stress, they might be reluctant to lend,” US Treasury Secretary Janet Yellen said Thursday in testimony to the Senate Finance Committee. “We could see credit become more expensive and less available.”

Christine Lagarde, president of the European Central Bank, told reporters Thursday that “persistently elevated market tensions” could further constrict credit conditions that were already tightening in response to rising interest rates.

Yes, again.

Here’s what Yellen also said to the Senate committee: “That could turn this into a source of significant downside economic risk.”

Goldman Sachs said Wednesday that growing stress in the banking sector has boosted the odds of a US recession within the next 12 months. The bank now believes that the American economy has a 35{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} chance of entering a recession within a year, up from 25{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} before the banking sector meltdown started.

The world’s second-biggest economy, China, is also sputtering despite a burst of activity following the rapid ending of draconian Covid lockdown measures late last year.

In a surprise move Friday, the Chinese central bank cut the amount of money the country’s lenders are required to hold in reserve in a bid to keep cash flowing through the economy.

— Anna Cooban contributed to this article.

Top 10 Use Cases For ChatGPT In The Banking Industry

Top 10 Use Cases For ChatGPT In The Banking Industry

Banking institutions have frequently been at the forefront of adopting slicing-edge engineering to offer greater buyer support and satisfy compliance necessities. With the rise of AI, banking companies can now leverage generative language equipment like ChatGPT to make improvements to productiveness, streamline functions, and increase their providers.

Of the quite a few distinct approaches banks can use ChatGPT, listed here are some of my favorites:

1. Buyer Company

Banks can use ChatGPT to completely transform their purchaser company by offering genuine-time help by means of chatbot. With ChatGPT’s organic language processing (NLP) capabilities, it can reply to purchaser queries, grievances, and requests for details speedily and successfully.

2. Fraud Detection

ChatGPT can help banking companies with detecting and avoiding fraud by examining extensive amounts of transaction information and pinpointing suspicious designs. This can assistance banking companies safeguard customers’ money assets and reduce losses from fraud. Lender staff can even established up alerts, so stability experts get notified of suspicious activity.

3. Financial loan Origination

Mortgage origination is a complex method that involves numerous measures, including accumulating consumer facts, examining credit rating scores, evaluating dangers, and processing personal loan programs. By leveraging ChatGPT’s pure language processing (NLP) and machine understanding (ML) abilities, banks can automate lots of of these tasks, generating the bank loan origination method quicker and much easier for consumers and financial institution employees alike.

When buyers utilize for loans, ChatGPT can present genuine-time steering and guidance throughout the procedure.

Then the product can aid banks in collecting customer info, analyzing creditworthiness, and supplying actual-time suggestions on mortgage programs. With ChatGPT’s capability to assess extensive amounts of facts and make exact predictions, banking companies can lessen the danger of default and make knowledgeable conclusions about loan approvals.

4. Wealth Management

ChatGPT can assist banking institutions in supplying customized wealth management expert services to their shoppers by analyzing customer details and providing custom made financial investment tips based on their person money goals and hazard tolerance.

5. Compliance

Compliance is a essential component of banking, and non-compliance can lead to substantial financial penalties and reputational harm.

ChatGPT can support banks comply with regulatory requirements by checking financial institution transactions and figuring out likely compliance violations. This can assistance banks stay away from high-priced fines and penalties and shield their status.

6. Money Scheduling

A lot of buyers rely on banking institutions to provide fiscal scheduling providers, and this is an additional good possibility for applying ChatGPT. Banking companies can use the product to give personalised money preparing products and services, which includes budgeting, personal debt management, and retirement arranging.

7. KYC and AML

Know Your Client (KYC) and Anti-Cash Laundering (AML) procedures are critical for banking companies to mitigate money crime threats and sustain regulatory compliance.

ChatGPT can help banking companies in automating these procedures by examining significant quantities of purchaser knowledge, which includes personalized information and facts and transaction history, and identifying probable compliance problems. It can also validate client identification, examine buyers in opposition to sanction lists and flag suspicious transactions. This cuts down the possibility of mistakes and increases the precision of compliance checks.

8. Customer Onboarding

Buyer onboarding is a important process for banks to catch the attention of and keep consumers, but it can be time-consuming and sophisticated. ChatGPT can guide banking institutions in bettering buyer onboarding by automating a lot of the procedure, lessening wait around moments, and streamlining the purchaser working experience.

ChatGPT can help consumers with:

● Filling out onboarding sorts

● Finding answers to their questions about banking procedures and procedures

● Addressing their fears about switching banking institutions

● Opening new accounts

The product can also support banks with the subsequent tasks during the onboarding course of action:

● Examining consumer details for precision

● Flagging challenges that need to be corrected

● Verifying client identities

● Offering individualized onboarding ordeals for clients

● Addressing customer worries

9. Danger Management

ChatGPT can aid banking companies in identifying and taking care of prospective dangers by examining vast quantities of knowledge and identifying potential chance things. Banks can also use ChatGPT to watch transaction pursuits, flag suspicious transactions, and determine probable fraud.

The product can also analyze current market information and information to assess prospective financial and political threats that may possibly influence the bank’s operations. With ChatGPT’s device finding out abilities, financial institutions can continuously master from earlier challenges and improve danger management procedures over time.

10. Digital Assistants for Banking

Financial institutions can present their shoppers with a digital assistant that is offered 24/7 to support with managing their accounts, having to pay expenditures, and performing transactions.

To remain on best of the newest on new and emerging organization and tech trends, make positive to subscribe to my e-newsletter, abide by me on Twitter, LinkedIn, and YouTube, and verify out my publications ‘Potential Abilities: The 20 Skills And Competencies Every person Requires To Succeed In A Digital Environment’ and ‘Business Tendencies in Apply, which received the 2022 Business enterprise Guide of the Calendar year award.

Rising Digital Banking Driving Growth

Rising Digital Banking Driving Growth

DUBLIN, Feb. 24, 2023 /PRNewswire/ — The “Consumer Finance Market place – World wide Marketplace Dimensions, Share, Developments, Opportunity & Forecast, 2018-2028F Segmented By Kind (Secured Shopper Finance and Unsecured Purchaser Finance), By Secured Client Finance Solution Variety, By Unsecured Purchaser Finance Merchandise Form, By Location” report has been added to  ResearchAndMarkets.com’s providing.


The world client finance marketplace was valued at USD1221.38 billion in 2022 and is predicted to register a CAGR of 7.16{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} via 2028 on account of increasing need for credit rating-centered usage, climbing disposable incomes and robust financial development.

This sector is observing a lot of new firms enter and improve, which include major peer-to-peer creditors and all-electronic players.

Purchaser existence and money conditions are transforming rapidly, which drives the purchaser finance small business. It is believed that a single of the most coordinated and designed industries in the planet is customer finance. Shopper finance has been growing steadily as a end result of the ongoing inhabitants advancement and economic growth.

On top of that, the fast processing of mortgage requests from a variety of general public and non-public banks or monetary establishments, as well as the basic availability of several financial loans including house financial loans, vehicle loans, and university financial loans, are expected to help the growth of the world shopper finance marketplace.

The COVID-19 pandemic slowed the nation’s all round financial growth. The consumer finance industry was also impacted by the economic slump. Shopper expending throughout mortgage classes, this sort of as individual financial loans and customer sturdy loans, experienced been drastically hit by issues like work losses, wage reductions, and problems about the long term, which further more hampered the growth of the global purchaser finance sector during that period of time.

As the principal protected and accessible preference for consumers in the course of the lockdown, the on the net solutions, noted escalating utilization of money products and services.

Economical Fascination Premiums Fueling the Current market Development

Very low curiosity rates strengthen the economic climate by enabling additional men and women to attain credit history. Due to the fact borrowing is less high priced when curiosity charges are reduce, shoppers can spend and commit additional freely. In addition, the price of borrowing funds is drastically impacted over time by interest costs.

When the desire amount is reduce, persons are a lot more possible to borrow cash to shell out for pricey merchandise like households or vehicles. Clients have more cash to commit when curiosity prices are decreased, which can guide to a rise in consumption throughout the economy. Therefore, this aspect is projected to more fuel the client finance market place advancement in the course of the projected period.

Increasing Electronic Banking Driving the Sector Expansion

Digital banking has flourished in several marketplaces, even with the point that this tendency differs enormously. All over 10-15 {1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} of consumers in the United Kingdom and the United States are much more intrigued in electronic banking now than they were before the COVID-19 outbreak.

The thought of electronic banking is getting huge acceptance amid buyers owing to the added benefits available by it. By working with this solution, individuals can save time and cash on transportation. On top of that, people can entry consumer economical products and services through EMIs (Equated Month to month Instalment) with the finance companies of their choice with the support of electronic banking. That’s why, the electronic banking is predicted to be a big contributor in the all round development on customer finance market place around the globe during the forecast period of time.

Rising Advertising and marketing Techniques Aiding the Industry Expansion

In purchase to bring in a significant client foundation and establish themselves apart from competitor companies, numerous organizations pick out unusual and chopping-edge internet marketing procedures. Massive data and automation are getting made use of by several corporations to concentrate on a sizeable consumer base.

Huge information can assist brands focus on certain clients for additional client services or electronic money education and learning because it can help them determine and offer you services right before or immediately after they are needed. For occasion, it can establish people who are possible to need pre-acceptance for a mortgage and are preserving up for a massive buy. As a result, new and exclusive promoting strategies will strengthen the buyer finance market place progress all over the world at a higher speed.

Corporations Described

  • Citigroup Inc.
  • JPMorgan Chase & Co.
  • Wells Fargo & Corporation
  • Bank of The us Company
  • American Convey Company
  • HSBC Holdings plc
  • Industrial and Business Financial institution of China
  • U.S. Bancorp
  • BNP Paribas
  • TD Financial institution, N.A.

Report Scope:

In this report, the international customer finance sector has been segmented into the next classes, in addition to the field trends which have also been comprehensive below:

Buyer Finance Marketplace, By Type:

  • Secured Shopper Finance
  • Unsecured Consumer Finance

Buyer Finance Sector, By Secured Client Finance Item Sort:

  • Housing Mortgage
  • Auto Bank loan
  • Mortgage loan Bank loan
  • Other folks

Shopper Finance Marketplace, By Unsecured Purchaser Finance Products Sort:

  • Particular Personal loan
  • Credit rating Card
  • Property Advancement Bank loan
  • Education and learning Bank loan
  • Other individuals

Customer Finance Marketplace, By Area:

  • North America
  • United States
  • Canada
  • Mexico
  • Europe
  • Germany
  • France
  • United Kingdom
  • Italy
  • Spain
  • Asia-Pacific
  • China
  • India
  • Japan
  • South Korea
  • Australia
  • South America
  • Brazil
  • Argentina
  • Colombia
  • Middle East & Africa
  • Saudi Arabia
  • UAE
  • South Africa
  • Kuwait

For more info about this report go to https://www.researchandmarkets.com/r/66tw7a-finance?w=5

About ResearchAndMarkets.com
ResearchAndMarkets.com is the world’s major source for worldwide market investigate studies and industry details. We offer you with the most recent facts on worldwide and regional markets, vital industries, the top rated companies, new products and the most recent tendencies.

Media Get in touch with:

Exploration and Marketplaces
Laura Wooden, Senior Manager
[email protected]
 
For E.S.T Office environment Hours Contact +1-917-300-0470
For U.S./CAN Toll No cost Phone +1-800-526-8630
For GMT Workplace Hrs Simply call +353-1-416-8900
 
U.S. Fax: 646-607-1907
Fax (exterior U.S.): +353-1-481-1716

Logo: https://mma.prnewswire.com/media/539438/Analysis_and_Marketplaces_Emblem.jpg

Supply Investigation and Marketplaces

New Law Relaxes Restrictions on Hiring Individuals with Criminal Records in the Banking and Finance Industry | Miller & Martin PLLC

New Law Relaxes Restrictions on Hiring Individuals with Criminal Records in the Banking and Finance Industry | Miller & Martin PLLC


On December 23, 2022, President Biden signed into law a bill pertaining to fiscal institutions which relaxes limits on employing folks with criminal data. 

Section 5705 of the 2023 Nationwide Protection Authorization Act (“2023 NDAA”), which is titled the “Fair Employing in Banking Act,” amends (i) Area 19 of the Federal Deposit Insurance policy Act, 12 U.S.C. § 1239 (“Section 19”) and (ii) Portion 205(d) of the Federal Credit Union Act, 12 U.S.C. § 1785(d) (“Section 205(d)”) to expand some of the exceptions relating to the work of individuals with legal records.  

Part 19 and Portion 205(d) describe the conditions less than which an particular person may possibly be utilized by a federally insured depository establishment or credit rating union, respectively. These Sections prohibit this sort of establishments from using persons who have been convicted of a crime involving dishonesty, breach of have faith in, or income laundering, or those who have agreed to enter pretrial diversion or a identical method in link with these types of an offense. If a economic institution wishes to make use of such individuals, it ought to obtain prior penned consent to do so from the Federal Deposit Insurance Company (FDIC) or the National Credit score Union Administration (NCUA). Segment 19 and Section 205(d) require financial institutions to carry out a “reasonable inquiry” into an applicant’s felony record to stay away from using the services of another person with a included conviction with no getting this consent.

Ahead of the passage of the 2023 NDAA, Sections 19 and 205(d) created a life span ban on employment with an FDIC-insured depository institution or an NCUA-insured credit union without the prior created consent of the applicable regulatory authority referenced earlier mentioned. The Reasonable Using the services of in Banking Act provisions of the 2023 NDAA narrow the scope of the crimes which are topic to Sections 19 and 205(d) and the conditions beneath which this consent is demanded. 

Specifically, pursuant to the Honest Using the services of in Banking Act, an personal no for a longer period wants the consent of the FDIC or the NCUA to come to be utilized with an insured economical establishment for “Certain More mature Offenses” below any of the next circumstances: 

  • 7 (7) decades or far more have passed since the person dedicated the offense or
  • The individual was incarcerated with respect to the offense, and 5 (5) years or additional have handed due to the fact the specific was released from incarceration or
  • The unique fully commited the offense when they had been 21 many years of age or younger, and additional than 30 months have passed because the sentencing for the offense transpired.

These exceptions do not utilize to people who have been convicted, or who have entered a pretrial diversion application for, “any of the enumerated offenses” [1] subject matter to a “minimum 10-yr prohibition” beneath Sections 19 and 205(d).

Furthermore, the Good Choosing in Banking provisions make it possible for the FDIC and NCUA to exclude other de minimis offenses by rulemaking, matter to the next 3 (3) necessities: 

  • The de minimis offense “was punishable by a time period of 3 (3) decades or much less confined in a correctional facility.”
  • Any de minimis exception with respect to offenses for composing inadequate-fund checks calls for that the combination whole face worth of all insufficient-fund checks is $2,000 or significantly less (no matter of the range of convictions and/or pretrial diversion plans). and
  • The FDIC and NCUA may possibly designate exemptions for other lesser offenses (which includes the use of a fake ID, shoplifting, trespassing, fare evasion, and driving with an expired license or tag) if at the very least just one (1) 12 months has handed considering that the conviction and/or pretrial program for this sort of offense.

These requirements triple the current interval of imprisonment qualifying for a de minimis offense (from a single (1) calendar year or a lot less to a few (3) decades or considerably less), double the mixture whole deal with benefit of inadequate-cash checks across convictions or pretrial packages (from $1,000 to $2,000), and cut down the demanded passed time time period for particular “lesser offenses” to only one particular (1) 12 months or far more. Since the FDIC and NCUA have broad discretion to issue new regulations in this space, the complete scope/effect of these new de minimis offense exceptions stays to be witnessed. 

Additionally, as a common make a difference, the Good Choosing in Banking Act provides that the prohibitions in Sections 19 and 205(d) do not utilize when a protected offense has been expunged, sealed, or dismissed. If there is “an purchase of expungement, sealing, or dismissal” that has been issued with regard to a included offense, and either the language of the buy or the legislative provisions governing the get indicate an intent that the conviction be destroyed or sealed from the individual’s federal, point out, or other file, then the prohibitions on employment are not relevant. 

Finally, the Good Hiring in Banking Act describes the method for getting the prior created consent referenced previously mentioned from the FDIC and NCUA, as effectively as the specifications these companies must implement in contemplating this sort of requests. The FDIC and NCUA must perform an “individualized assessment” when examining such requests, taking into consideration “evidence of rehabilitation, the applicant’s age at the time of the conviction or method entry, the time that has elapsed given that the conviction or method entry, and the connection of the individual’s offense to the responsibilities of the applicable place.” These agencies also have to contemplate other “individualized” factors, such as the individual’s employment history, letters of suggestion, completion of substance abuse, task preparation, or educational programs, and other relevant mitigating data. 

The Good Hiring in Banking Act presently is in result and will be carried out by the FDIC and NCUA this year. Therefore, as a functional subject, federally insured money institutions can no extended depend on Segment 19 or Area 205(d) to supply the grounds to instantly disqualify applicants who have been convicted of sure offenses. These institutions will need to have to modify their selecting techniques with regard to applicants with prison records accordingly and continue to be up to date on further guidelines and other assistance issued by the FDIC and NCUA pertaining to these procedures.

[1] These “enumerated offenses” contain: receipt of commissions or items for procuring loans theft, embezzlement, or misapplication by a lender officer or staff filing or building bogus/deceptive bank entries, studies, and transactions submitting or building phony/misleading federal credit score institution entries, studies, and transactions concealment of property from conservator, receiver, or liquidating agent of a economical institution financial institution fraud obstructing evaluation of a fiscal institution laundering of financial devices engaging in financial transactions in home derived from specified illegal activity frauds and swindles and fraud by wire, radio, or television.