CARTERSVILLE, Ga.—Surya has signed an arrangement to invest in Worldwide Views for an undisclosed sum, Surya introduced this early morning. The offer will empower Surya to superior penetrate the larger-stop interior design and style phase although boosting its current assortment with a wider array of accent pieces and accessories.
Under the phrases of the obtain, Dallas-centered Worldwide Sights will go on to function as an independent brand with inventive route from CEO David Gebhart. The offer is envisioned to be done in the coming months.
“This marks the start of a transformative new chapter for our business. With the addition of Global Sights to the Surya spouse and children, we will be in a position to reach additional designers and superior provide their desires,” said Surya CEO Satya Tiwari. “We seem ahead to becoming the custodians of the legendary Worldwide Views model and we are self-assured that, less than our leadership and David’s inventive vision, it will carry on to prosper for generations to appear.”
Whilst Surya has a powerful foothold in the rug enterprise, it has been steadily including item classes, like lights, accent home furniture and decorative add-ons, to its assortment.
Meanwhile, interior designers account for approximately 55{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} of World-wide Views’ small business, in accordance to Gebhart.
“Partnering with Surya to preserve the World Sights brand developing and thriving in the residence decor market is a blessing for me, and my partners Frederick Rayner and Lois Del Negro,” Gebhart said in a launch. “I will continue to spearhead the World Sights model with the resourceful group already in place.
“Having witnessed firsthand the spectacular development and progress of Surya, we are self-assured Global Views, underneath Satya’s stewardship, will have an even greater impact in our industry and the potential of household furnishings style,” he extra.
“Global Sights has a potential way beyond my lifespan,” he explained to Residence Accents Nowadays. “The brand is the most crucial part of this deal.”
The acquisition frees Gebhart to concentrate on the factors he likes the most, he mentioned — solution advancement, design and presentation — although leaving other folks to consider care of the functions crucial to working a company this sort of as overseeing funds stream, IT and warehousing. Lots of back again-business functions between the two firms will be shared, he mentioned, but all the existing staff who continue to keep the brands working will continue to be. “There will be no layoffs in anyway,” he reported.
One of the items he uncovered when the Surya workforce came to Dallas to speak was their shared business enterprise lifestyle philosophy, according to Gebhart. “We share the exact tips of how to operate a corporation and interact with staff members,” he claimed. “The synergies of the corporate tradition is a definitely great issue to have.”
Gebhart stated he, Rayner and Del Negro have thought of prospects to partner with other brands in the past but have now located the perfect custodian for World wide Sights. “I’ve marketed it to a further like-minded person and that’s the most effective that could perhaps come about,” he said. “It’s complete get for Frederick, Lois and myself.”
See also:
Surya packing much more oomph into machine-created rugs
While they may seem like outliers from the perspective of most providers in the country, publicly traded home health companies are often a great indicator of where the industry is – and where it’s going.
Whether they’re investing in new service lines or diversifying their revenue streams, the big providers on the block continue to change the home health industry at large.
Scott Fidel, an analyst at the private investment banking company Stephens, is part of a team that analyzes and evaluates those moves. He covers the post-acute space, as well as the managed care space.
Fiedel sat down with Home Health Care News on the latest edition of HHCN+ Talks to discuss Medicare Advantage trends, financial stability, home-based care M&A and a lot more.
The transcription of that conversation is below.
HHCN: Before we get going, Scott, I do want to get your background and a background on your company.
Scott Fidel: I’ve been a sell-side equity research analyst covering the health care services sector on Wall Street for the past 24 years or so. I focused on health care services for pretty much my entire career on Wall Street. The way that we break down our coverage is we look at three primary subsectors.
First, and very relevant for this conversation, is the post-acute care space — including all of the home-based care areas. We cover most of the publicly traded home health companies. Then we also cover managed care. That’s a sector I’ve covered very closely for the past quarter century. In areas like Medicare Advantage, for example, we’ve been covering that space for a long time.
I actually was a health care lobbyist for a while even before working on Wall Street where I had been involved with the whole Balanced Budget Act of ’97, and the transition of Medicare+Choice — ultimately leading to Medicare Advantage. Then we also covered the health care facilities, companies, acute care hospitals and behavioral health companies as well.
In terms of Stephens, the firm is one of the largest privately-held independent investment banks in the US. The firm has offices in the U.S. and Europe. The firm was founded in 1933 and provides a range of services to our clients, including equity research, investment banking, capital markets and capital management.
Given your scope of research and coverage, how are home-based care companies specifically faring right now compared to everyone else?
Let’s put that in context since the pandemic. It’s really been a tale of two different stories for this sector. The stocks actually started out the pandemic as real pandemic winners when we had the whole work-from-home-type analog trade in the market and with the expectation that the space would be a significant beneficiary of that.
Then, as the pandemic sustained itself, and a lot of the pressure started to build and when the broader investment climate deteriorated, the stocks faced more challenges. When we look at the overall aggregate period of the last three years, the post-acute home health sector has actually underperformed on the market. In managed care and health care facilities, that underperformance has been more weighted towards the last 18 months or so.
Within the sector, though, there’s been variation in generally what we see and companies focused more on personal care and home-based care outperform given how much better the reimbursement environment has been there. Whereas companies that are more levered to Medicare home health reimbursement, in particular, have been relative underperformers.
Then we’ve had all the consolidation dynamics, too, at play.
One of the things I love that Stephens puts out are the underlying drivers that dictate success in home health care. There are a few things that you’re measuring on a monthly or quarterly basis that generally are good indicators of the long-term and short-term success of these companies. Can you go into that a little bit? What are you tracking in order to see if these companies are on the right track?
For personal care, we focus on hours served and billable hours. On reimbursement for home health, we focus on their organic growth trends. It ultimately comes down to this home-based care tracker that we cover and it looks at a whole range of functions. It looks at home health admissions trends, reimbursement trends that we see in Medicare, Medicare Advantage trends and what we’re seeing in the episodic and non-episodic trends.
With personal care, we look at particularly billable hours and then the rate trends.
We also cover hospice in this as well. We’d look at a number of the variables that drive the hospice sector including things like hospice admissions, length of stay — which has been a big area of focus as well from the pandemic. Ultimately, what we’re trying to do with this product is determine inflection trends across these bottom-up metrics. And, while looking at the broader subset of all the drivers of the industry, trying to glean which companies are outperforming in particular areas.
What’s interesting is we do see a wide range of success factors across different companies in the sector. We put this out in our home-based care dashboard product where we look at all the KPIs. That’s just one of a lot of products that we publish.
A few examples. It’s interesting if we look at just home health to start with and look at same-store admissions trends. Going into the fourth quarter, we actually saw Humana — who had acquired the Kindred at Home asset and is now the largest home-health operator — actually show some of the strongest same-store admissions trends in the fourth quarter.
We thought that was interesting because Humana is now rolling out their value-based care program across the contracting structures for home health. They’re still relatively early into that phase, but that’s likely going to continue here into 2023 and into 2024.
When we look at some of the revenue generation statistics in terms of maximizing revenue opportunity — the Pennant Group — which is the spinout from Ensign, has actually shown quite strong performance when we look at things like revenue per admission and revenue per day on the hospice side. That company has actually been effective at realizing the revenue opportunities, particularly as we transitioned into the PDGM model and away from the former Prospective Payment System for home health.
Then if we look at the personal care, I would say that some of the themes have been consistent across operators. If we look at the rate trends, generally, they’ve been pretty robust across all the companies that disclose these metrics. We tend to look at Addus.
Modivcare, as well, has become a meaningful player in that market. Amedisys has traditionally disclosed some of these metrics but now they’re actually divesting that asset.
On the hours side, in terms of the volumes, what we’ve seen is that it’s been constrained because of the challenges in hiring caregivers, but it does feel like we are on the cusp now of starting to see those volumes start to inflect more positive for these companies starting in the fourth quarter. We think that will likely continue into the first quarter and then continue to improve in 2023.
Are you surprised at all by Humana’s effectiveness with CenterWell this early? Is that something that you thought may take a little bit longer to get going, or just because of how established Kindred was, how established Humana is as a company, is that something that’s not as surprising?
It’s not too surprising for us just because of how deliberate Humana really was around the process of ultimately acquiring Kindred at Home, which is now a centerpiece of the CenterWell brand and broader clinical platform that Humana continues to build. Remember that Humana had a long-term investment in the platform and they really spent a couple of years deliberating on whether they would be able to successfully create value by acquiring the asset and rolling out the value-based care platform.
Now, clearly, the backdrop has gotten that much more challenging since they acquired the asset with the pressures that we’re seeing with add-on expenses – on wages, on reimbursement and on volumes. With Humana, we are seeing them committed to that rollout. Also, they’re going to be taking on a larger piece of the spend as part of this. It actually helps them enhance the revenue picture, too, in terms of the partners that they’re working with.
We really think that tracking Humana in terms of how they’re performing on this rollout of the value-based care initiative in home health is going to be really insightful for the rest of the industry because, clearly, right behind them we have UnitedHealth and Optum. Now having acquired LHCG, we’re going to be very interested in whether Optum and United roll out a similar model for LHCG or take a bit of a different track.
That’s the conversation that we’re having about UnitedHealth and another company that we cover as well. Clearly, the focus on value-based contracting and on Medicare Advantage contracting is a huge area of focus right now and critical for home-based companies.
What will another rate cut mean for these companies given that it had made them underperform recently? It’s obviously something that’s baked into how people are viewing these companies right now, but at the same time, it’d be yet another cut. Obviously, that’s going to be a challenge for them. How do you feel about how that’s going to affect them, short and long-term?
It’s the biggest single overhang in the public investor community right now around the home health companies and it’s frustrating because CMS clearly utilizes a meaningful level of lag data in terms of how they conduct their analyses. The real-world inflation has clearly accelerated. We do understand that CMS, even more recently in some of the stakeholder interactions, hasn’t seemed to reflect that they are fully recognizing or sympathetic to the idea that this will be a major challenge and affect access to care.
We can see, in the volume trends that these companies report, that it is really constraining the ability to hire more skilled nurses. This is something with CMS that can often be a bit frustrating — and with payers in general — is where they’ll speak to certain policy objectives that are core to their view on advancing the health care system, and making for a more efficient and productive health care system. But then they do things with reimbursement that don’t seem to be aligned with that.
To boil it down: while there is a lot going on across all three of these subsectors, what CMS does with the 2024 home health rates is most likely going to be the single largest determinant of investor sentiment, and then also of investment in general. It’s important, putting aside just the publicly traded stocks, how things like the M&A environment will be dictated.
For example, just yesterday I spent the day hosting investor meetings with the Addus management team. They have been a successful, consistent operator. They operate in all three of these markets. Home health for them is relatively smaller. It’s only around 5{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} of their revenue. With that said, it is an area they wanted to deploy capital to grow that business through acquisitions, but clearly, they’re going to be very disciplined right now and prudent around engaging in deals focused on home health until we have that clarity on the reimbursement. And again, how that influences the valuation dynamics too where the publicly traded companies have been under the microscope for a while.
A lot of these stocks have been substantially pressured. The valuation multiples have come down quite meaningfully since their peaks during the earlier part of the pandemic, but on the sellers’ side, I think a lot of these sellers are still holding on to some of the memories of where deals were getting done and that’s creating friction in the market right now. That’s going to have to work itself out.
Hospice is another good example of that where we had a tremendously active deal environment for a number of years. Really, hospice was the tip of the spear in terms of M&A activity with strategics and with private equity, too. Valuation multiples have gotten very rich, but hospice fundamentals themselves have been more pressured over the last 12 to 18 months with a variety of headwinds from the pandemic.
That’s affecting margins, and that’s affecting EBITDA for these companies, and that’s another area where it feels like the pace of activity has frankly slowed quite significantly from where we were 12, 18, 24 months ago.
Because of those Medicare fee-for-service conditions, how important do you think it is for these companies to be successful in their negotiating with Medicare Advantage payers moving forward to offset some of those cuts to make sure that the financials are stable as they take on more beneficiaries in MA?
It’s central to the story and to the strategies. It’s absolutely critical. Separate from even if the Medicare fee-for-service reimbursement environment hadn’t suddenly gotten so stunted, the long-term structural trend in Medicare is still towards a significant long-term movement into Medicare Advantage. The numbers are simple right now, right? We’ve just pretty much eclipsed 50{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} or half of the overall Medicare market being in Medicare Advantage.
When I started covering the managed care stocks after the Balanced Budget Act of ’97, we had dipped into the low-teens percentage. I’ve watched this go from 12{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b}, 15{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} to 50{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} in, let’s call it, a little bit over 20 years. And the Medicare Advantage space is still growing 7{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} to 9{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} annually, and Medicare fee-for-service is barely growing. Now, when you add on the variance and the margin profiles, the economics where you look at many of these Medicare home health companies, maybe they’re reporting 12{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b}, 13{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b}, 14{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} adjusted EBITDA margins.
Inside of that, you have Medicare fee-for-service business with margins substantially higher. MedPAC tries to argue that the margins are in the low 20s. I’m sure the industry would push back on that, but they’re clearly higher than the consolidated average. Medicare Advantage is barely profitable for a lot of these companies with single-digit margins to begin with. Ultimately, the economics need to balance out between Medicare fee-for-service and Medicare Advantage. It’s as simple as that.
I have these conversations on both sides of the negotiating table. I cover the home health companies and I cover all the managed care companies too. I do find it very interesting that the managed care companies across the board, when they talk about their key long-term mega themes in health care, obviously value-based care is an enormous one, but the shift to the home is a theme that all these companies emphasize over and over again in their investor presentations to investors and in their discussions with the market and with analysts. Yet we always hear from home health companies about how terrible the reimbursement is in home health.
I think, ultimately, there’s going to have to be some shaking out and some achievement of more of a balance here. It does feel to me right now like the economics are inordinately skewed toward MA, relative to home health in this particular area. Remember, the other challenge that we’re going to have to remember is out there. And that is that the Medicare Advantage companies themselves are going to be facing a tougher reimbursement climate.
In the last couple of years, CMS has given the MA companies unusually strong reimbursement updates and it’s still been really tough for home health companies to get proper reimbursement. Now the MA companies are looking at much tighter reimbursement, a new risk model that’s being implemented that is going to create a lot of complexity, and at the same time, the home health companies have to even negotiate more furiously for higher reimbursements. That’s a story we’re going to be tracking, but it’s uncertain exactly what the end result is going to be as we look out to 2024 and beyond.
It’s interesting to see, it could go two ways. Obviously, home health providers are hoping that those MA plans will react to that by saying, “Hey, let’s put more money and more focus on the home-based care side of things to control post-acute spend,” but they could also say, “Hey, we’re getting less. That means you’re getting less.” It’ll be interesting to see that dynamic play out.
Yes, absolutely. Ultimately, we need to remember that when you’re shifting a care consumption or utilization into the home, it drives substantial savings for Medicare Advantage plans, relative to being in a SNF or relative to being in an ERF or clearly, being in an acute care facility.
At some level, I do scratch my head sometimes around why MA plans are being so difficult on reimbursement to home health when in the overall scheme of things, that’s not a lot of money, relative to having patients end up staying in a facility.
This also comes down to how fragmented the home health industry is and the difficulties for a lot of home health agencies to really distinguish themselves with MA plans as not just being commoditized, right? Ultimately, value-based care is an area that could separate that dynamic. That is something that probably the more highly scaled companies are able to, on the home health side, participate in more because there is a significant investment in complexity, separate from the regulatory complexity that we’re dealing with that’s being pushed on the industry by CMS. That’s probably a theme that ultimately would drive more consolidation over time.
There’s a lot of debate right now, too, around how this consolidation will play out. Because we’ve got larger home health companies wanting to acquire smaller ones, but there’s this friction around multiples and around deal valuations right now. Then, obviously, you have the Medicare Advantage companies just taking out some of these largest players, too. Remember, they’ve got that leverage dynamic, too, with Medicare Advantage as well, whereas a Humana takes a Kindred as a subsidiary, and United takes on LHCG as a subsidiary — they’re going to want to ensure that the economic future for those subsidiaries is positive and emphasize that opportunity.
They have folks like us writing reports on them every quarter, evaluating them on that. It also raises the point of whether, at Humana or United, how much more interested are they going to be in raising reimbursements right now for these other operators out there when they need to focus on maximizing the value of these assets that they’ve recently acquired.
How was the event with Addus yesterday? Was there anything else that you gleaned from it that you maybe had not considered prior it?
I always enjoy catching up with the Addus management team. I think that they have a long track record of disciplined operation in the industry. They’ve been through the home-based markets in both easy and difficult times. They’re very prudent. Particularly, we see that with their balance sheet, for example, they’ve kept their debt leverage very low. That’s something that their stock has been rewarded for, relative to some of the other stocks with higher leverage, given the market’s focus on rising interest rates and liquidity, essentially.
With Addus, on the M&A side, I think they are eager and ready to do transactions. They’ve talked about wanting to focus a bit more on the personal care, which is their core market, and home health as compared to hospice, where Addus had been very active on the M&A front for a number of years in terms of building out that platform. They want to be very disciplined as well on the acquisition side. Separately, they do think that the reimbursement outlook will remain solid, actually looking at even 12 to 24 months for personal care because of the current positions of the state budgets, which have been favorable.
We’re going to be watching that area, frankly. Clearly, investors are going to be focused on whether or not the economy does flow. What that means for state budgets and what that means for reimbursements as well.
I do want to also mention redetermination. The return of that, which just kicked off four days ago, is a huge area of focus for investors, but it is less relevant — frankly — to personal care companies and to home-based companies in general because the clients and the patients that they serve tend to be polychronic dual-eligible-type patients who are just eligible for core Medicare or Medicaid services.
That doesn’t have to do with normal Medicaid eligibility based on income levels. We cover the managed Medicaid companies, for example, where this is a big area of focus but we’re not expecting that particular issue to be really much of a headwind at all for the personal care companies.
Do you think the home-based care companies on the public market reflect the rest of the industry?
I think that you already named a few of the attributes that are important, but it really sets the overall tone for thinking about both some of the investment considerations as it relates to things like sentiment and valuation, and then also how the market is thinking about evolution in the operating environment. Clearly, from the sentiment perspective, much of the market is going to be at least referencing what is happening with the stock prices and valuations of publicly traded companies.
It’s the most visible and constantly evolving valuation metric to reflect all the latest information in the market. When you think of investor sentiment, many of the large investors are talking to the publicly traded companies, and that’s dictating their overall sentiment in the industry. Then when we think about the operating environment. These companies do tend to have higher margins and more ability to generate free cash flow, which they can then use to invest to try to adapt to how the market is evolving. So whether it’s with Medicare Advantage, whether it’s with value-based care, investing in programs to do that.
I think a clear example of this would be Amedisys acquiring Contessa, which clearly has also had its challenges. I think Amedisys would be the first one to admit to that in terms of the ramp-up of that business. When you think about trying to create a new category within the space by moving more into those hospital- and SNF-at-home-type programs, you need a lot of capital to do that, though.
Frankly, Amedisys has spent a lot of capital, both on what they pay for it and the losses that they’ve invested in to build that business. A small company is not going to be able to do that, but ultimately if the market moves there and that becomes part of the core package of what these companies do, they’re going to have to adapt as well.
There were a lot of rumors about a few home-based care companies going public in 2020 and 2021. Since then, a lot of those rumors have subsided, probably because of those macroeconomic trends that are affecting the entire economy. Do you expect any more home-based care companies to be go public in the near-term future?
Good question. I think that in the near future, the market is still licking its wounds, frankly, from the IPO cycle of 2021. There were a lot of health care services businesses that hadn’t really proven profitability, and they have struggled mightily.
The main one that happened directly in this area was Aveanna, which has struggled, too, with some of these pressures — clearly with both their stock price and also with some of the changes in the fundamental environment. Clearly, the overall market environment is going to have to improve. Then, there’s the bottoms-up-type dynamics that we’ve just spent the last 35 minutes talking about.
If I had to assign a higher weight to a couple of those, I do think that on the home health side, clearly, the investor community getting more conviction on Medicare reimbursements, both for fee-for-service and for MA, is going to be key. Investors are going to want more clarity on that.
Personal care — frankly — that’s been an area where it’s been a bit more stable. More recently, obviously, there are areas to monitor in terms of potential headwinds if the economy slows, but there’s a little bit less controversy right now around the reimbursement dynamics. Again, that’s always the rearview mirror. One thing we’ve always seen is the pendulum swing back and forth around reimbursement, for sure with payers, and particularly with CMS.
CMS tends to overshoot on reimbursement cuts and then will come back and ultimately put corrective reimbursement in. That creates a positive reimbursement cycle. Then the market, both the industry and investors, think that’s going to be sustainable forever and maybe the sentiment gets overinflated. Then, CMS comes and pulls the rug out from underneath everybody and we wash and repeat.
Ultimately, we think that’s going to happen again, most likely. Clearly, if margins get pressured and that data on a lag basis starts to catch up to CMS, we will start to see better reimbursements and that could reopen that opportunity for more active public investing of some of the companies that are still private in terms of opportunities to go public.
I do want to ask you before we go, a prediction that you might have about the home-based care industry at large?
In terms of the under-the-radar screen, I don’t know about that because we try to keep everything above the radar screen as much as possible. I would say that as we just talked about, the centrality of the focus will be on these reimbursement trends. On some of the policy dynamics, there have been some proposals to really invest more in the home-based care area that Biden had proposed, for example, that ultimately didn’t come through.
I’m going to bring it back to something that’s not so spicy, but I think that ultimately, it does come down to having the actual frontline personnel to actually deliver these services. When you look at really the crux of everything, reimbursement has been key, but the other issue has just been around the labor dynamics and it’s been around whether it’s skilled or unskilled.
If I had a prediction to give you there, it does feel like the environment — from the hiring perspective — probably will get better more quickly in the unskilled area. That does tend to be more directly correlated with the overall economic cycle and with the labor market. I would be surprised if we don’t see personal care companies, for example, start to be able to improve their hiring right as the unemployment rate starts to rise.
I think there will also be some level of correlative benefit for skilled workers as well. When the economy gets tougher, nurses that have been sitting out for a while may come back into the workforce, but we still also have the long-term structural constraints that we have around nurse staffing and clinical staffing shortages. That’s going to be an issue for a long, long time to come.
It’s been something that we’ve been focusing on really the whole time I’ve covered the space. I think 10 years from now if we did the same type of talk, we’d still be talking about some of the structural challenges that we’re facing in staffing. Especially as we even have more seniors to care for in the future.
A lot of workers prioritize obtaining the option to operate remotely at minimum just one day for every week.
Workforce who get the job done remotely clearly show proof of increased work pleasure.
With remote get the job done below to remain, extra businesses are investing in the methods their personnel need for flexible operate environments.
This write-up is for administrators and enterprise entrepreneurs interested in the existing and long term condition of remote perform.
Distant operate was unusual a 10 years in the past. Operating from household was usually available only as a specific arrangement to accommodate family members in distinct cases. On the other hand, teleconferencing and telework technologies have highly developed to the place exactly where some organizations prosper with completely remote groups.
The mass transition to remote doing work came about in the early levels of the COVID-19 pandemic. Further than blocking disease from spreading – a ill group just can’t be as productive – remote do the job has proven helpful in a number of methods.
Considering that doing work from residence is below to stay, it’s essential to know how to get the most out of distant conversation know-how. Following all, your workforce can be just as efficient, if not more, doing the job from home if you have the suitable applications. Read through ahead for a guide on the past, present and future of distant doing work.
Is remote doing work helpful?
A decade in the past, most employers would have balked at the plan of staff members regularly doing work from household. A single key issue most employers experienced for doing the job remotely was a loss of efficiency. But the pandemic confirmed that workers could operate on their individual. Prodoscore, for case in point, reported that distant workers’ efficiency enhanced 47 per cent through the lockdown in March and April 2020, getting that communication functions these kinds of as emailing (up 57 per cent), telephoning (up 230 percent) and chat messaging (up 9 p.c) all climbed.
Other current experiments suggest that distant perform possibilities improve career satisfaction. Buffer’s 2023 Condition of Remote Function report located that 91 p.c of survey respondents relished doing work remotely, with versatility mentioned as the biggest advantage. On top of that, in 2022, McKinsey surveyed 25,000 workers across a vary of industries about their distant do the job knowledge. In accordance to the research, in search of out versatile do the job environments is the third cause why men and women search for new employment (greater spend/hrs and profession prospects are the other folks). Distant operate is this sort of a big precedence for personnel that 87 per cent of the respondents explained that when made available the probability to function remotely, they would consider it.
Finally, performing remotely is successful, but it has to be place into apply appropriately, and it might not be the greatest scenario for every single worker or each and every business.
Personnel are selecting to get the job done remotely when offered the option, and those who do report greater task fulfillment.
How remote perform has developed
There was a time when distant operate as we know it wasn’t even a probability, because the engineering did not exist. If your colleagues and business enterprise partners desired to get in contact with you when you were being out of the workplace, they couldn’t electronic mail, textual content or direct message you. You would’ve required to deliver an option cell phone amount or e mail to have a work-related dialogue. Even entire-time “remote” positions have been distinctive from what they are currently.
“Ten a long time back, distant employment in essence intended a telemarketing or shopper company posture at under minimum amount wage,” mentioned Samantha Lambert, director of human assets at Centific. “It seldom was linked with a whole-time profession. Now, technologies affords us the capability to get the exact same job done, no make any difference where in the entire world we are. [It has] enabled us to be in get hold of with co-workers or consumers at any time.”
Just one of the most beneficial systems for seamless distant perform is video clip conferencing. Stay online video feeds assist out-of-place of work staff see and talk to just one a different in genuine time, wherever with an internet connection, which is the upcoming very best matter to a experience-to-face meeting. But this capability would not be doable without the need of the widespread broadband world wide web adoption of the previous 10 to 15 decades.
This technology has superior so promptly that several businesses have even accomplished away with regular offices and instead run their companies out of coworking spaces to accommodate their mostly distant workforce.
“Shared office spaces, exactly where remote personnel can get to do the job, have been created and are additional extensively out there in various towns,” Lambert claimed. “This in by itself signifies the escalating amount of distant personnel in recent decades.”
Remote work also provides special possibilities in the facial area of a disaster, these as a normal disaster or an epidemic. As the pandemic carries on, distant work solutions let staff to defend community well being and be aspect of resilient groups.
The present condition of remote function
For the reason that of these advancements in conversation know-how and net entry, teleworking has come to be an accepted exercise in a lot of workplaces, each in the U.S. and globally. This sort of work is not performed completely from house: Distant staff often transform to espresso stores or coworking spaces, and some even travel the world while retaining their occupation aims.
“The contemporary workforce is significantly cell, collaborative [and] dynamic, and contains multi generations, all with various interaction tastes,” said Stacey Epstein, main marketing officer at Freshworks. “These workers span many industries … all of who[m] depict unique issues when it comes to keeping connected although on the task.”
Nonetheless, a lot of firms proceed to resist this work trend for different explanations. Some organization house owners may well worry a lack of productiveness in their employees, when other people have not invested in teleconferencing and telework tech to aid distant workers. Even now, some corporations are generating the needed investments to guidance remote function.
In Buffer’s 2023 report, most companies paid for charges such as components, business office gear and materials, with 64 {1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} of respondents indicating their corporation supplied components and 40 {1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} reporting that things like a desk and chair have been also presented. Net services was specified to 28 percent of distant workforce.
This is marginally much better than Buffer’s 2019 report, in which 75 p.c claimed their employers would not pay back for web service. As the want and expectation of doing work remotely increase drastically each and every 12 months among the workforce, companies may possibly be far more very likely to guidance remote-friendly guidelines.
Adopting a distant doing the job coverage can also help you save providers revenue by eradicating the need for costly office environment house (or satellite offices) whilst enabling staff the independence to develop their individual schedules and perform from where ever they make sure you. It can be a acquire-acquire condition.
As additional employees hope remote function alternatives, far more corporations are investing in the tech and programs necessary to guidance working from residence.
What the long run retains
When the construction of distant get the job done may keep on to evolve, this versatile business enterprise product is here to continue to be. Remote choices may perhaps proceed to develop as technological improvements these kinds of as AI are capable to participate in a key purpose in handling distant team.
The transition to overseeing a distant workforce may be challenging, but with the correct tech and hardworking personnel, it can be a seamless approach. In the prolonged run, considering the fact that several workforce now anticipate distant work alternatives, it is critical to embrace place of work innovation.
Adapt your approach for distant operate results
Alternatively of resisting transform, companies really should increase their remote function insurance policies and capabilities. If your corporation is concerned about efficiency and general performance concerns due to a companywide skill to work from dwelling, Lambert endorses building typical important efficiency indicators (KPIs) for both equally management and personnel. This way, she claimed, remote workforce members are mindful of employee expectations, and their functionality can be monitored. It’s just like conventional in-business office perform, but from a distance.
North East-based mostly treatment company Hark Team Holdings has reported it is trying to find to go on to expand through acquisitions as it capitalises on fragmentation in the Uk care sector. Above the last yr, acquisitions have helped the enterprise to treble in dimensions.
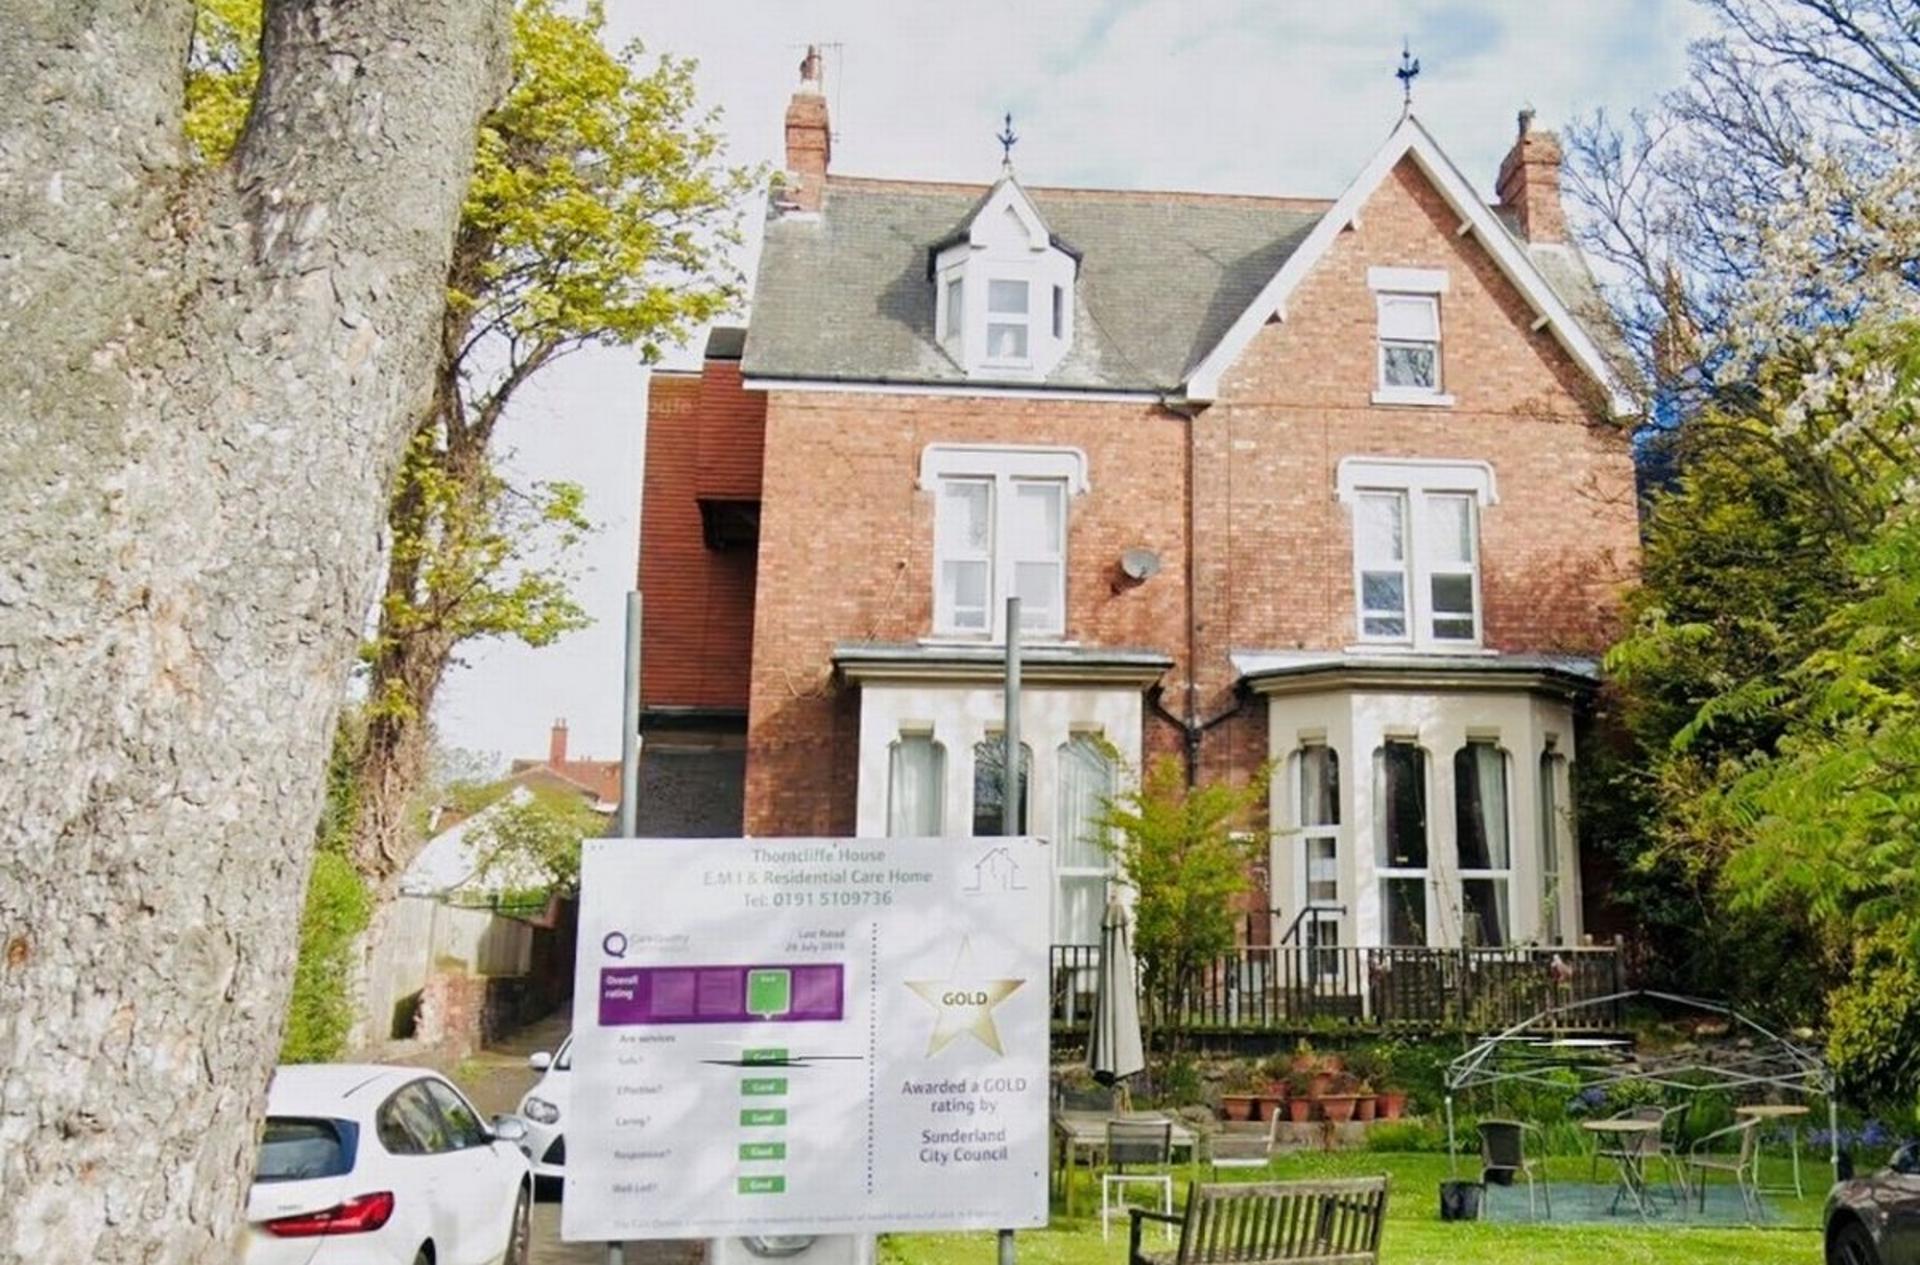
In the previous 12 months, the company has acquired the small business and belongings of Sunderland treatment house Cedar Dwelling, as properly as the entire issued share money of Thorncliffe Care Minimal, which operates the Thorncliffe Property treatment house in Sunderland (pictured higher than).
Hark Group labored with Mincoff Solicitors and accountancy and company advisory Azets on the discounts, with funding furnished by Allica Financial institution. The group’s leadership suggests it is aiming to function with both of those Mincoff and Azets on long term M&A specials.
Hardip Kang, director and owner of the Hark Group, who established the enterprise with his spouse Rupinder Kang, commented: “Our growth and advancement this past yr was significantly assisted with the know-how, knowledge and eye for depth from Chris Hughes and all the team at Mincoffs.”
“It is really the type of reassurance a rising organization needs when seeking to realize their expansion targets. Lee Humble and the workforce at Azets offered me with the economic tips and aid to speed up the momentum desired to get the offer more than the line. I look forward to doing the job with equally all over again for any doable upcoming acquisitions.”
Mincoff Solicitors Corporate Spouse Chris Hughes mentioned: “It has been great to perform intently with the two Hardip and the workforce at Hark and with Lee and the crew at Azets to provide Hark Group Holding’s vision for the North East care sector.”
“Thorncliffe Household and Cedar Property Treatment Residence are amazing additions to Hark’s portfolio and it has been a enjoyment to assist the group in acquiring these two business enterprise, so it can keep on to present essential, leading quality, treatment across the location.”
Azets Corporate Finance Partner Lee Humble extra: “It has been a pleasure to do the job with these kinds of a strong crew with a compelling development eyesight. I am enthusiastic to see what the potential retains for the Group, and we are delighted to be portion of their journey.”
Fragmentation and a large number of owner exits because the COVID-19 pandemic have driven a growth in dealmaking in the care sector and Lee Humble noticed: “The sector is incredibly energetic at current, and we are usually eager to support aid transactions for enterprises like Hark.”
Present for Existence, the reward and residence industries’ sole charitable group, currently declared that industry veterans Todd and Jannetta Litzman will be honored with its 2023 Present for Everyday living Business Accomplishment Award on June 21, 2023, in Dallas, TX. Reward for Life’s Marketplace Accomplishment Award, which has been offered at Items & Ornamental Accessories’ Retailer Excellence Awards (REA) considering the fact that 2009, acknowledges over-all excellence and contribution to the gift and property marketplace – regardless of whether as a imagined leader, common-bearer or all round sector influencer.
“I can not consider of a lot more deserving recipients of Gift for Life’s Sector Accomplishment Award,” reported Ari Lowenstein, chair of the Reward for Everyday living board. “Todd and Jannetta are trailblazers. They have served the gift and household industries for a lot more than 25 many years and pioneered much of the technological know-how that varieties the basis of our wholesale ecosystem these days. Their continual and committed engagement with businesses, reps, models and prospective buyers alike is reflected in the resources they have designed to assist all stakeholders involved in the sales method. Every person in our business has been touched by their do the job and benefited from their several contributions.”
Jannetta Litzman is the EVP of Finance and HR for MarketTime and former co-founder and CFO of Brandwise, Inc. Her vocation started off in the telecom marketplace as an govt with AT&T in product sales and marketing. Just after earning her master’s diploma in Business Administration at the University of Denver, she took the plunge into entrepreneurialism when she commenced a Residence Décor and Accent Furnishings Showroom. Even though attending a lot of trade displays as a buyer, she discovered a engineering hole in the wholesale reward and dwelling industries. As a result, she and her husband and business associate, Todd Litzman, co-started Showroom Options, which later on arrived to be recognized as Brandwise, Inc. Prior to its acquisition by MarketTime, Brandwise was the largest SaaS provider for the wholesale present and property business for a lot more than 25 many years. In addition to her company roles, Jannetta also served for 12 decades on the Gift for Daily life board.
Todd Litzman has more than 30 several years of encounter proudly owning, managing and functioning technology companies. Todd was a Co-founder, President and CEO of Brandwise/Showroom Answers right before providing Brandwise to MarketTime in 2021. At the moment, as President of MarketTime, Todd is intimately associated in doing the job with buyers to guarantee that the software and companies satisfy requirements, and that the consumer accomplishment crew continues to give extraordinary assistance. He has often been very included with the market and was earlier the President and Chairman of the Gift and Property Trade Association (GHTA) Board and now serves as a common board member and has served on other boards across the numerous industries that MarketTime serves.
“We are honored to be nominated by the Gift for Everyday living board for this most coveted market award,” explained Todd and Jannetta Litzman. “When we developed our technologies company to assist this field, we experienced no concept how deeply we would connect with our buyers and how substantially our technology would positively impact their company and personal lives. It is this perception of reason and duty that drives our staff forward each and every working day. Throughout our 25-year journey, we have created so a lot of lifelong mates and distinctive memories. We humbly accept this award and rejoice it with all our staff members, enterprise partners, shoppers and sector buddies who have supported us through the yrs.”
The 2023 Present for Life Business Accomplishment Award will be presented to Todd and Jannetta Litzman at the 72nd Annual Retailer Excellence Awards (REAs), on June 21, 2023 at The Southside Audio Hall at Gilley’s Dallas. Donations in celebration of Todd and Jannetta Litzman will reward Globe Central Kitchen’s around the world crisis-connected hunger aid efforts. Donate at https://donate.wck.org/REA2023.
Considering the fact that 1951, Presents & Decorative Accessories has been celebrating the very best of the finest in seven retail categories: Specialty Shop, Multiple Locations, Visible Merchandising, Retail outlet Situations, Retailer Design, Social Media Outreach, Online Initiatives, and Socially Accountable. Awards are also offered to Producer of the 12 months and Gross sales Consultant of the Calendar year. Details, nominations and registration for the 72nd Retailer Excellence Awards is available at https://www.retailerexcellenceawards.com/.
The smart home market size is valued at USD 101.7 Billion in 2023 and is anticipated to be USD 163.7 Billion by 2028; growing at a CAGR of 10.0{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} from 2023 to 2028.
Factors such as the Expansion of the smart home product portfolio by large number of players, and Growing concern about safety, security, and convenience among general population are driving the growth of the market during the forecast period.
Expansion of smart home product portfolios by large number of players.
The smart home industry involves a wide range of manufacturers worldwide, including those who produce components, devices, systems, software algorithms, and service providers. Tech giants such as Samsung, Amazon, Google, and Apple have introduced innovative products like SmartThings, Echo, Home, and HomeKit for the smart home market. In January 2023, Apple launched HomePod Gen 2, which allows users to monitor temperature, humidity, establish smart home automation with Siri, and receive notifications during the detection of smoke alarm. Due to the convenience, energy efficiency, and cost-saving benefits offered by home automation solutions, homeowners are adopting them on a large scale. Lighting control, HVAC controls, and security and access products have a high penetration rate in North America and Europe. As a result, manufacturers of smart home products are expanding their portfolios to cover different application areas in a household.
Growing adoption of smart devices and increasing number of internet users.
The Internet of Things (IoT) has become increasingly popular among residential consumers due to its ability to connect household products to the internet and provide real-time data and decision-making capabilities. As a result, companies of all sizes are investing heavily in the IoT industry, and it is expected to be applied in a wide range of areas such as lighting, security, healthcare, and entertainment. The growth of the smart home market is driven by the increasing adoption of video doorbells, voice-assisted technologies like Alexa and Google Home, and surveillance systems. The widespread adoption of internet-enabled devices such as RFID, barcode scanners, and mobile computers, which is being driven by the growing number of internet users worldwide, is expected to further boost the IoT market. The penetration rate of the internet has increased significantly in the past decade, especially in developed regions such as according to Internet World Stats as of June 2022, North America and Europe, registered penetration rates of 93.4{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} and 89.2{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} respectively, while Asia and Africa registered penetration rates of 67.0{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} and 43.2{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} respectively.
Asia Pacific is the fastest-growing region in the smart home market.
There is a significant market for smart homes in Asia Pacific, specifically in countries like Japan, South Korea, and China. Among these countries, South Korea has become a significant market for smart home systems due to the high demand for lighting and entertainment controls. China, with its rapidly growing economy and population, is investing heavily in energy-efficient technologies. Meanwhile, South Korea is also a major player in the smart home market for household appliances. Furthermore, the high rate of internet usage in Japanese households is expected to drive the growth of the smart home industry in the Asia Pacific region.
Market Dynamics
Drivers
Increasing Number of Internet Users and Growing Adoption of Smart Devices
Increasing Disposable Income of People in Developing Economies
Increasing Importance of Home Monitoring in Remote Locations
Growing Need for Energy-Saving and Low Carbon Emission-Oriented Solutions
Expansion of Smart Home Product Portfolios by Large Number of Players
Growing Concerns About Safety, Security, and Convenience Among General Population
Restraints
More Convenience-Driven Rather Than Necessity-Driven Market
High Cost of Switching for Existing Smart Device Consumers
Issues Related to Security and Privacy Breaches
Opportunities
Favorable Government Regulations to Promote Green Buildings
Incorporation of Lighting Controllers with In-Built Data-Connectivity Technology
Integration of Power Line Communication Technology in Smart Homes
Challenges
Difficulties Linking Disparate Systems, Limited Functionality, and Lack of Open Standards
Risk of Device Malfunctioning
Compatibility Issues Between Devices of Different Companies
About ResearchAndMarkets.com ResearchAndMarkets.com is the world’s leading source for international market research reports and market data. We provide you with the latest data on international and regional markets, key industries, the top companies, new products and the latest trends.