South Africa’s banking sector is well capitalised and its capital adequacy and liquidity ratios have remained well above minimum statutory requirements. Total banking sector assets increased in the year to end-March 2022, with increases reported in gross loans and advances, investment and trading securities and short-term negotiable securities.
Profitability improved significantly. However, the operating environment remains highly volatile and the banking sector is facing elevated domestic and global risks, including the possibility of being placed on an international grey list over South Africa’s failure to implement adequate measures to prevent illicit money flows.
Trends
Mobile and digital banking are key drivers of financial inclusion in South Africa. Despite the uptake of digital banking, cash transactions are prevalent, and banking activity continues to be dominated by cash withdrawals, which are often made at supermarket till points. Many banks are consolidating and closing underserved branches and ATMs. Demand for credit is rising, and rising inflation and interest rates are placing consumers under growing pressure and increasing the risk of bad debt. Cybercrime poses a growing threat to banking service providers and their customers, and money-laundering is on the increase.
Financial Inclusion
South Africa’s formally financially included is high at over 90{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} and various banks offer products for low-income earners. Co-operative financial institutions and microfinance institutions play a fundamental role in financial inclusion. Stakeholders say that migration to formal savings platforms has accelerated since 2020.
Report Coverage
This report covers the banking industry in South Africa including the major commercial banks, development banks, central bank, digital banks, microfinancing and stokvels. It includes comprehensive information on the size and state of the sector, industry statistics and performance indicators, rankings, corporate actions and other developments.
There are profiles of 81 companies including the major banks such as FirstRand (FNB), ABSA, Standard, Nedbank, Capitec and Investec, development banks such as the Land Bank and relatively new players such as TymeBank and Bank Zero.
Key Topics Covered:
1. INTRODUCTION
2. DESCRIPTION OF THE INDUSTRY 2.1. Industry Value Chain 2.2. Geographic Position 2.3. Size of the Industry 2.4. Key Success Factors and Pain Points
3. LOCAL 3.1. State of the Industry 3.2. Key Trends 3.3. Notable Players 3.4. Corporate Actions 3.5. Regulations 3.6. Enterprise Development and Social Economic Development
4. AFRICA
5. INTERNATIONAL
6. INFLUENCING FACTORS 6.1. The War in Ukraine 6.2. Economic Environment 6.3. COVID-19 6.4. Financial Inclusion 6.5. Technology, Research & Development (R&D) and Innovation 6.6. Government Support 6.7. Labour 6.8. Cryptocurrency 6.9. Crime 6.10. Environmental Issues
7. COMPETITIVE ENVIRONMENT 7.1. Competition 7.2. Ownership Structure of the Industry 7.3. Barriers to Entry
8. SWOT ANALYSIS
9. OUTLOOK
10. INDUSTRY ASSOCIATIONS
Select Companies Mentioned:
Absa Bank Ltd
Access Bank South Africa Ltd
African Bank Ltd
African Dawn Capital Ltd
Afriticket System (Pty) Ltd
Agribel Capital (Pty) Ltd
AgricReview (Pty) Ltd
AgriRewards (Pty) Ltd
Albaraka Bank Ltd
Alicerose Nominee (Pty) Ltd
All In One Vermietung GmbH
API Capital (Pty) Ltd
Axis Security Services Ltd
BA Excepted Group Life Scheme Ltd
BA Holdco Ltd
BANCO Bocom BBM SA
Bank of China Ltd
Bank of Taiwan Co. Ltd
Bank Zero Mutual Bank
Barko Financial Services (Pty) Ltd
Baroda Pioneer Asset Management Co Ltd
Batho Bonke Absa HDSA Employee Trust
Bemax International (Pty) Ltd
Bidvest Asset Management (Pty) Ltd
Blue Holdings (Pty) Ltd
BNP Fortis Factor NV
BNP Paribas Commercial Finance Ltd
BOC International (China) Ltd
BoCom International Holdings Company Ltd
BOCOM Wealth Management Co Ltd
Buyers Trust Investment Solutions (Pty) Ltd
C T International Financiers (Pty) Ltd
Capital Harvest (Pty) Ltd
Capitec Bank Ltd
Cavalry Holdings Ltd
CCB Financial Asset Investment Corporation Ltd
CH Risk and Securities (Pty) Ltd
China Construction Bank Corporation
Citibank N.A.
CNH Industrial Capital Europe SAS
Co-Operative Switch (Pty) Ltd (The)
Deutsche Bank AG
Development Bank of Southern Africa
Diners Club (S A) (Pty) Ltd
Direct365Online Ltd
Discovery Ltd
East Africa Investment (Mauritius) Ltd
FHP Managers (Pty) Ltd
Finamics Accounting Services (Pty) Ltd
Finbond Group Ltd
FinGlobal Finance (Pty) Ltd
FireID Payments (Pty) Ltd
First Garment Rental (Pty) Ltd
FirstRand Bank Ltd
GBS Mutual Bank
Geniob Trading (Pty) Ltd
Gloster Farm (Pty) Ltd
Golden Fountain Finance Ltd
Grindrod Bank Ltd
Habib Overseas Bank Ltd
HBZ Bank Ltd
HKFT Properties (Pty) Ltd
HSBC Bank PLC
ICICI Bank Ltd
Imfundo Finance (RF) (Pty) Ltd
Industrial Development Corporation of South Africa Ltd
About ResearchAndMarkets.com ResearchAndMarkets.com is the world’s leading source for international market research reports and market data. We provide you with the latest data on international and regional markets, key industries, the top companies, new products and the latest trends.
Media Contact:
Research and Markets Laura Wood, Senior Manager [email protected]
For E.S.T Office Hours Call +1-917-300-0470 For U.S./CAN Toll Free Call +1-800-526-8630 For GMT Office Hours Call +353-1-416-8900
U.S. Fax: 646-607-1904 Fax (outside U.S.): +353-1-481-1716
Campaign contribution data from economic connected industries obtained from opensecrets.org for Senator Wyden, D-Oregon and chairman of the Senate Finance Committee, and Senator Crapo, R-Idaho and position member of the Senate Finance Committee, shows higher assistance for Wyden from the securities and investment business and greater support from commercial banks and finance and credit organizations for Crapo.
Senators Wyden and Crapo are nicely-suited to have their contributions compared and applied as a circumstance study for marketplace support for the Democratic and Republican functions. Donations to this pair should make more perception into sector assistance for their respective functions than any other pairing in the Senate.
They are both equally incumbent senators, so they would each advantage from incumbent fundraising strengths. They are each up for re-election this year, so donors who donate late in an election cycle are included for each candidates. They equally maintain seats that are viewed as electorally protected, this means the donors are unlikely to be interested in striving to swing a close election. They are also equally the greatest-position associates of the Senate Finance Committee of their respective get-togethers, so neither is getting a seniority reward that the other isn’t.
And they stand for states not famous for their financial sector, indicating many of their economic marketplace donors are from other states.
Study from Brandice Canes-Wrone , professor of politics at Princeton College, and Kenneth Miller, professor of political science at the University of Nevada, Las Vegas displays that candidates that are far more reliant on out-of-point out donors are inclined to be extra responsive to the opinions of the nationwide donor base as opposed to the belief of the voters they characterize. Safer seats, this sort of as individuals occupied by Senators Wyden and Crapo, also tend to be more responsive to nationwide voters. Because finance is a countrywide business, clustered in states not represented by Wyden and Crapo, such as New York, the impact of the national donor foundation on financial problems should to be significantly acute for both of those.
But why donate to a prospect in a risk-free seat? If they will get in any scenario, why not conserve your funds? Candidates in protected seats are nonetheless expected by their celebration to fundraise, and candidates can transfer limitless sums of income to the countrywide and state bash committees. For that reason, contributions can even now enhance their status and leverage within their occasion, and so donations can nevertheless be made use of to curry favor with them, researchers located.
Analysis from Anthony Fowler, professor of general public coverage at the University of Chicago, reveals that corporations ordinarily do not gain adequate from electing favored candidates, at least not by a margin to justify their donation. However, donors are much more likely to get meetings with users of Congress than common voters, and donations are much more of a way to get a member’s consideration, gain entry, and cultivate personalized interactions with them and their team. Considering the fact that Wyden and Crapo are both senior customers of their committees, and possible to serve until finally their retirement, receiving their consideration with donations can be a beneficial organization investment.
With that in hand, what type of aid do the two senators acquire from finance-relevant industries?
Working with contribution information compiled from opensecrets.org, contributions from industries of desire and contributions from people and people from political action committees, or PACs can be examined.
Particular person contributions are capped at $2,900 for every prospect for each election, which means a donor can add the maximum in a most important and then all over again in the basic election, totaling $5,800 for the election cycle. In this circumstance, PACs are corporations developed by a enterprise (union PACs are not involved in this dataset) that can fundraise from the workforce of that business enterprise. Which includes both equally particular person donations and PAC donations supplies a broader view of help inside the marketplace for Wyden and Crapo.
The info show that Crapo received extra contributions from the industrial banking sector, $64,342 from people doing work in that market, and $210,000 from PACs produced by enterprises in that field, than did Wyden. Wyden’s contributions from industrial banking institutions had been $19,395 from people today and $19,750 from PACs, totaling $39,145 vs. a overall of $274,342 for Crapo.
Crapo also gained more from finance and credit rating corporations than did Wyden. Crapo received a complete of $159,550 with $37,850 and $121,700 coming from people and PACs respectively. Wyden received a complete of $31,173 with $11,673 and $19,500 coming from people today and PACs respectively.
1 conflating variable as it relates to these two industries is that Crapo is a member of the Banking, Housing, and City Affairs Committee and Wyden is not. On the other hand, both business banking institutions and finance and credit organizations donated more to Republicans in standard in 2022.
Wyden received far more funds from the securities and expense industry and from donors classified as currently being in miscellaneous finance industries than did Crapo. He also been given far more from retired donors than Crapo.
Crapo gained $748,754 from securities financial investment, and finance donors, in comparison to $1,105,310 for Wyden. Donors in the miscellaneous finance classification donated a whole of $194,119 to Crapo and $311,714 to Wyden. Retired donors donated $106,692 to Crapo and $1,185,095 to Wyden.
Nevertheless retired individuals do on constitute an industry, their contributions are involved in this assessment owing to associates of that group’s use of monetary items. The Senate Finance Committee is included in the challenge of retirement coverage reform and passed the Gain Act previously this yr as aspect of a broader established of reform expenses dubbed “SECURE 2..” Market insiders believe that this reform really should go all through this Congress and it is supported by each senators.
Following the earlier sample, miscellaneous finance donors have presented additional to Democrats in typical in 2022, as did the securities and investments field. Retired people on the other hand, have specified more to Republicans ($316.7 million) than Democrats ($289 million).
Why the Banking, Finance and Insurance plan industries must embrace digital brokers right before they’re left powering
By Sanjeev Kumar, VP EMEA at Increase.ai
Technology’s romance with the entire world of finance is one particular of contradiction. Innovation is a critical part of the business, and fintech in unique is a slicing-edge place. However, legacy banking companies remain averse to embracing new tech that they see as risky and untested globally. If latest developments, like the wide move to digital banking, have shown anything, it’s that the world of finance is in the midst of seismic modify and that there is even far more sizeable improve to occur.
2022 has been a difficult year throughout all industries. Younger generations exhibit less loyalty to support suppliers, models, and workplaces. In an unsettled environment, organisations will need to established by themselves aside. People are spoilt for alternative and pressed for time. It has in no way been more vital for banking institutions and money establishments to offer buyers a premium service and to have rock-sound personnel retention techniques in spot.
The remedy lies with synthetic intelligence (AI). Smart automation, digital agents and conversational AI are tested units for money establishments to tackle customer and staff churn immediately. As an ever-rising number of economical organisations adopt these systems, it is no longer a subject of if but of when conversational AI becomes a essential and commonplace option in the finance marketplace.
How Intelligent Automation will work
Clever automation combines artificial intelligence and automation technologies to automate very low-stage jobs. For illustration, freeing up personnel to engage in the responsibilities they have been properly trained for, alternatively than low-stage administration and very simple customer requests.
While clever automation can take many kinds, a person of the much more typical sorts we see in the banking, fiscal products and services and insurance (BFSI) industries is virtual brokers. Digital agents use innovative all-natural language algorithms in the form of conversational AI to fully grasp the user intent of internal and external queries and supply contextual responses. For instance, just one digital agent could possibly be in place for client complaints, though one more will be put in to deal with interior service desk requests. On an specific degree, the profit is obvious for workers – position fulfillment – and for shoppers – support fulfillment.
Smart Automation in motion
It is not just a suggestion to embrace a modern day, electronic-initially shopper banking expertise, but at this issue, it is an expectation. With banks and insurers remaining gradual off the mark, new entrants to the business have been equipped to swiftly get market-share by providing sleek, efficient, and shopper-friendly solutions crafted about AI systems.
Simply call centres garner significantly ire from clients they are clunky and time-consuming nevertheless, human interaction nonetheless plays a crucial job in consumer provider procedures. The trouble is that human interaction ought to only be utilised when vital, not as the initial port of simply call. For case in point, if a digital agent can not solve a query, then a individual will be on hand to carry in their expertise to address whichever the trouble is.
On the other hand, thanks to conversational AI, this is rarely a issue that banks and finance establishments need to have to offer with any extended. With the suitable implementation, digital brokers can solve more than 90{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} of client queries. Any remaining provider tickets are normally more advanced and can be dealt with by human agents, building a streamlined, nevertheless very personalised, provider.
So, what is keeping organisations back again?
In a term, fear. Concern of shopper backlash at ‘robots’ responding to their issues. Fear all over the security of allowing AI accessibility to broad swathes of consumer facts. Fear of expense-to-advantage ratios. 85{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} of executives concur that anxiety holds back again innovation efforts often or generally in their organisations. But nine out of 10 organisations are undertaking practically nothing to simplicity individuals fears.
When easy to understand,, these fears are increasingly misplaced, as developments in conversational AI technological know-how have assisted to dispel these fears. Intelligent virtual agents are creating absolutely sure that terribly built chatbots are staying relegated to historical past. Safety is prioritised with these solutions as nicely, producing positive that consumer and question info is stored and shielded appropriately. And smart automation does not will need to be high-priced. Organizations can choose and pick the extent and scope of automation they wish to utilize, with the skill to take a look at out a alternative before going all in on it. Most importantly, conversational AI and automation technologies are no for a longer period just for large firms with great economies of scale scaled-down-scale businesses can craft bespoke automation applications that do the job to their scale also.
Personalisation is a escalating aspect of conversational AI and a escalating precedence for buyers. As AI technological innovation advances, new applications inside BFSI will burst forth – from spotting fraudulent action through pattern tracking to pinpointing probable tries at fraud by comprehending shopper keystrokes and voice styles – and the options are endless.
The upcoming is bright, the potential is automatic
The time is now for steady, streamlined adoption of digital brokers and conversational AI. With electronic banking becoming the principal form of banking, specially as consumers turn out to be additional digitally-savvy, creating a cohesive electronic providing for shoppers has never been additional significant, and discussion AI has a substantial job to perform in enabling this.
Building the ideal knowledge for customers and personnel is only attainable by creating on good foundations, and it’s vital that organizations have the suitable technologies in put to attain this. And when it will come to developing foundations, conversational AI has a massive purpose to participate in. This technological know-how not only aids consumers to acquire improved-top quality products and services, but personnel see a lot less time spent on mundane administrative and low-amount jobs. The benefits even attain corporate final decision-makers, who can accomplish greater consumer pleasure, more staff retention and a sleeker and far more economical inside and exterior conversation resolution with conversational AI.
Of study course, it is important to be aware that not just about every organisation’s AI solution will be the exact same, but it is abundantly very clear that pretty number of organisations will be in a position to do without having a person in the coming many years.
Flagstar Financial institution, the seventh major bank home finance loan loan company in the US, introduced in June, 2022, that it experienced been hacked in December, 2021, and personal facts on 1.5 million clients exfiltrated. In accordance to information reports, Flagstar has not discussed the 6-month time lapse from the attack to the announcement. Earlier in 2021, Flagstar was among the the several organizations breached as a result of the hack of the Accellion file transfer appliance.
Flagstar explained it has no evidence that any of the information and facts obtained in the most up-to-date breach has been misused – even so, at the very least two customer lawsuits are in the courts, one particular filed by a plaintiff who claims that his identification was falsely utilized to get out a loan immediately after the breach. The bank is featuring two a long time of credit rating monitoring to clients.
Estimate of Probable Charges for Flagstar Lender from a Process Intrusion Assault
Flagstar hasn’t made public the aspects of the attack, but let us suppose for assessment that the lender was hit with a technique intrusion attack, in other words, code exploitation, brute force password guessing or other practices that gave cyber criminals a foothold on the network. Employing the RiskLens My Cyber Possibility Benchmark instrument, we can estimate the influence of a procedure intrusion assault on a monetary organization of Flagstar’s size:
$310.3 million for Key Response Fees
$22.7 million for Shed Earnings
$585,000 for Fines & Judgments
$333.6 million Total
Monetary Sector Cyber Incidents Count
The authoritative 2022 Verizon DBIR experiences that finance was strike with 2,527 cyber incidents in 2021, which includes 690 info breaches. That placed this sector at quantity five for overall incidents, but amount 1 for data breaches, out of 21 surveyed.
Most Possible Cyber Dangers by Incident Frequency and Decline for Banking, Insurance plan, and other Economical Institutions
The RiskLens data science staff estimates risk for companies in an market classification centered on the cyber situations historical past plus a broad assortment of parameters these kinds of as profits, quantity of workers and amount of database documents.
In RiskLens modeling, technique intrusion for a fiscal establishment of Flagstar’s size and style comes in as a rather low possibility at a 4 {1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} possibility of transpiring in a year with an anticipated expense of about $330 million. As proven in the chart under, insiders are the most most likely source of cyber functions in finance – banks and other financials have been reasonably thriving in decreasing frequency of exterior productive assaults. As the IBM Safety X-Power Menace Intelligence Index 2022 commented:
“High security standards in position at most economic organizations are yielding concrete final results and the monetary companies marketplace is performing security appropriate. In addition, hybrid cloud environments are dominant at economic providers corporations, allowing for for greater visibility into and management of sensitive data.”
Finance also arrives out rather effectively as opposed to businesses of equivalent measurement in other industries, at selection five for incident probability and variety six for incident price out of nine industries.
Databases Dimensions and Stability Posture Make a Variation
Adjusting the parameters on the My Cyber Danger Benchmark software offers clues on how to reduce cyber decline exposure.
For occasion, lowering the quantity of information in a databases, but leaving the other settings the very same for a money corporation exhibits dramatic enhancement for a process intrusion event
10M – 100M Documents = $330M Reduction
10K-100K Records = $132M Loss
To level stability posture, the Benchmark device incorporates grading by Stability Scorecard. Here’s how the yearly probabilities of a program intrusion assault go up for a financial institution or insurance policy corporation as security grades go down, suggesting the value of controls investments, this kind of as improved obtain management.
A = 2.5{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b}
B = 4.{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} (Flagstar’s Stability Scorecard grade)
C = 5.1{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b}
D = 6.8{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b}
F = 8.3{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b}
In the months leading up to the Glasgow COP26 climate change conference last November, the UK government spent long hours lining up landmark agreements to be announced during the fortnight on car emissions, deforestation, methane and more.
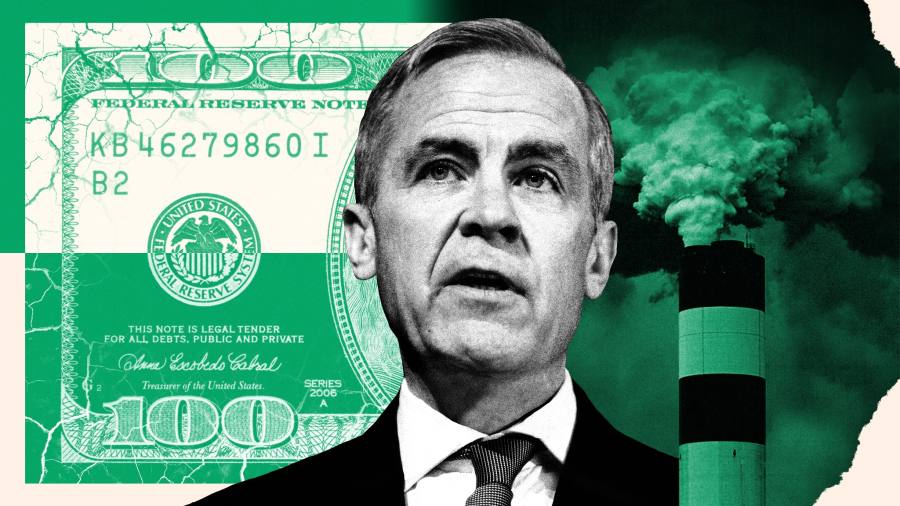
Among the most eye-catching of the announcements was the commitment unveiled by Mark Carney, the former Bank of England governor, on the conference’s finance day: a pledge that $130tn — four in every 10 dollars under management globally — would be deployed to limit global warming. “This is a watershed,” he said. Quoting the climate activist Greta Thunberg, he added: “It’s not blah blah blah.”
The promise was made on behalf of the Glasgow Financial Alliance for Net Zero (Gfanz), the grouping of banks, asset managers, insurers, pension funds and other money managers Carney had launched in April 2021. It was greeted as a fundamental shift away from purely profit-driven capitalism by the financial sector.
Behind the scenes in 2021, not everyone working on COP26 in government was convinced of the timing, or the wisdom, of Carney’s announcement. “Carney saying we’ve got $130tn of money ready” risked looking “misleading”, says one civil servant working on negotiations at a time when the COP26 presidency was struggling to persuade developed governments to deliver on a promise of $100bn in annual climate assistance to poorer nations.
There were also concerns the announcement was more promotional than tangible. “A lot of this came down to Carney’s desire to have something branded as his own thing,” says Ben Caldecott, finance strategy adviser to the UK government in the run-up to COP26. “It became a running joke among those working on finance for Glasgow.”
You are seeing a snapshot of an interactive graphic. This is most likely due to being offline or JavaScript being disabled in your browser.
But without Carney’s “convening power” there would have been no alliance at all, says Alex Michie, who advised the Treasury on private finance ahead of COP and now co-leads Gfanz’s secretariat. “The only design we had was to get the global financial system to make science-based commitments to net zero and take near-term action to implement it.”
To reduce the risk of greenwashing, the UK government laid down a single red line, according to Caldecott and the civil servant. Carney’s brainchild would have to agree to work alongside an existing verification body for corporate and financial sector pledges: the UN’s Race to Zero.
“Civil society knew that many of the finance sector commitments were rubbish, so we needed to be proactive on integrity,” says Caldecott, who also leads the University of Oxford’s sustainable finance group.
When Gfanz expanded in November, its governance documents show Race to Zero was put in charge of vetting new and existing members and helping define the speed at which they decarbonised their portfolios.
Yet one year on, and just 10 days before COP27, that red line was erased. Gfanz officially relegated the UN-backed body to the status of one adviser among many at the end of last month. The financial institutions under the Gfanz umbrella no longer have to be aligned with the multilateral body meant to uphold their integrity.
UN guidelines on preventing corporate greenwashing published at the summit on Tuesday concluded that Gfanz and other alliances needed to tighten their standards and be prepared to remove poorly performing members.
The split from the UN-backed body reflects the difficulties Carney’s team has had keeping this self-governing club of financiers together. It came under intense pressure from mutinous American banks reluctant to divorce the fossil fuel sector in the middle of an energy crisis. It also faced a backlash by litigious rightwing political forces who criticise “woke investing” and say the financial sector’s first duty ought to be to shareholders.
Contacted for an interview, Carney sent the FT a written statement in which he said the perceived risk of antitrust penalties over collective action had been a “big challenge” for Gfanz this year, and called on governments to “move more rapidly” on setting guidelines for company transition plans.
As COP negotiators meet in Egypt on Wednesday to discuss how to raise the capital for green energy and climate adaptation, the troubles Gfanz has faced reflect a broader struggle within the financial sector over whether business or government should be responsible for channelling cash into stemming the financial crisis, and whether they should take a purist or “broad church” approach to fossil fuels. They also raise wider questions about the strength of the finance community’s commitment to the green transition — and whether institutions promised the rest of the world too much too soon at Glasgow.
A battle over coal
An early harbinger of difficulties in how to define the central goal of Carney’s alliance was a battle over coal: specifically, meeting a target of net zero “financed” emissions, which are linked to financing and investment decisions, by 2050.
Scientists at the International Energy Agency and the United Nations broadly agree that reaching net zero by 2050 means fossil fuels should be actively phased out and plans for new coal power plant projects immediately junked.
The co-chair of Gfanz, businessman and philanthropist Michael Bloomberg, funds anti-coal campaigns and has described the fuel as “enemy No 1 in the battle over climate change.”
But as transaction data rolled in over the months following COP26, it became clear that Gfanz members had continued to double down on existing financing patterns — for example, bond issuances for coal companies maturing well into the 2030s.
This was especially glaring among the banks who had been convinced to join Carney’s alliance in the unsettled weeks immediately before Glasgow.
JPMorgan Chase, for example, underwrote a $788mn share issuance by the Indian miner Vedanta Resources the month after it joined the alliance in October, according to open source financial data analysed by the NGO Reclaim Finance. Vedanta is developing a new coal mine in India. JPMorgan declined to comment.
But it was not just US banks. Only 60 out of the alliance’s 240 largest members had any policy excluding support for companies developing new coal projects, according to evidence submitted to the UK’s environmental audit committee by the campaign group ShareAction in June.
Beyond coal, only a few leading banks showed a material reduction in bond underwriting for carbon-intensive industries including mining and automobiles in 2021 compared to 2019, according to a report by financial sector research group Autonomous.
In June, this continuing activity by Gfanz members and other companies was addressed in a revised, much tougher set of membership rules from Race to Zero. The official interpretation guide to its new criteria made clear that members must “restrict” their facilitation of all new fossil fuel projects, and that “no new coal” must be supported.
Carney’s alliance did not officially adopt this messaging, and nor did financial sector subgroups whose members had strict fiduciary obligations to clients. Some members cited fears that such strict wording would lead to attacks from competition authorities concerned about potentially higher energy costs for consumers if coal plants have to close.
Many financiers argue the sale of a high-emitting asset does not necessarily stop the associated carbon from entering the atmosphere, which means the “carrot” of investment matters more than the “stick” of divestment.
As financiers’ discomfort with the new Race to Zero guidance became clear, activist groups and some lawyers perceived it as a litmus test of their seriousness on climate action. “Banks at Glasgow saw the alliance as a kind of ethereal thing on climate change without ever mentioning the F-word: fossil fuels,” said Beau O’Sullivan, from the Sunrise Project, a network of NGOs. “It is only when the ambition was lifted that the antitrust concern was raised.”
Others like Simon Holmes, a competition law expert and visiting professor at Oxford university, say that if the alliance collectively refused to invest in fossil fuels it could face “genuine issues” of antitrust, particularly in the US. “From a competition law perspective it can be seen as a collective boycott agreement not to provide a service like finance or insurance to customers,” he says.
The political risks of rapid decarbonisation were uncontestably real, especially in the US. Republican attorneys-general and state governors in the US spent the summer cracking down on members of Carney’s alliance, including the asset manager BlackRock, for perceived environmentally driven neglect of the oil and gas industries that provide jobs to the US economy’s heartlands.
This pressure, amplified by rocketing energy prices, pulled at the seams of the alliance. A grouping of US banks including JPMorgan threatened to leave altogether if they were not given more freedom to decarbonise at their own pace, according to a senior banking executive and people involved in talks between Gfanz and banks.
The US bank underwrote a $788mn share issuance by the Indian miner Vedanta Resources
Given the success of Gfanz had in part been measured by its ability to attract a broad church of capital, the stakes of any exit were high. “There was a bit of gamesmanship [from the banks],” says a party to crisis talks within Gfanz. “Were they threatening to leave to force the disconnect to Race to Zero, or did they want out anyway because it was an easy sacrificial lamb to give to the attorneys-general?”
Then, one evening in September, “no new coal” was quietly wiped from Race to Zero’s website. The UN-backed body had taken legal advice, it said when asked, and was told the strict language put its own staff at risk.
The next month, Gfanz put out a statement highlighting its members’ legal rights to follow whatever voluntary pledges they chose to. The banks remain within the alliance.
No business as usual
Despite its shift away from the UN framework, Gfanz says it is committed to transparency and robust benchmarks. “We are acutely aware that unclear boundaries and guardrails on these financing activities can obscure ‘business as usual’ financing,” Mary Schapiro, vice-chair of Gfanz and former chair of the US Securities and Exchange Commission told a press conference in the run-up to COP27.
A new Gfanz-backed data initiative designed to provide greater transparency will be up and running by the end of 2023, the alliance has said, while net zero targets will be “systematically embedded across the financial sector” by 2027. It has galvanised many of its members to set near-term decarbonisation targets, meaning they have pledged to reduce financed emissions as soon as 2025 or 2030.
“We’re going to get real time feedback, not just on individual performance, Gfanz member performance, but also the system as a whole,” Carney said at the FT Moral Money Americas summit last month.
Global banks’ pledges to date put them on track to deliver $1.9tn in energy transition finance a year until 2030, according to research group Autonomous. It says this number is growing but is still roughly half the level of bank support needed for the transition to net zero, which it puts at between $3tn and $5tn a year.
HSBC counts £2.2bn of sustainability-linked loans it organised last year for British Airways and UAE’s Etihad airline towards $1tn of green finance by 2030
“The hardest work is still to come,” says Hortense Bioy, global director of sustainability research at Morningstar, describing the situation as an “existential crisis” for Carney’s climate finance movement — now worth $150tn. “The reality is that not enough has been done in the past 12 months — some would argue we have moved backwards.”
In his statement, Carney emphasised the alliance’s long term plans. “We need to ensure that energy supply is maintained during the transition so that consumers do not continue to bear the burden of unreliable, expensive energy sources,” he said. “In the short term, that will involve financing for some oil and gas, but what is important is ensuring that we are dramatically scaling up investment in renewable energy to a 4:1 ratio.”
But as Gfanz sets out new commitments, the voluntary bodies intended to set independent standards for the finance industry are falling by the wayside.
The Finance Sector Expert Group, set up during COP26 to develop Race to Zero membership criteria for financial institutions, was quietly disbanded in February. Race to Zero has also postponed plans to set up a new accountability mechanism in order to examine the progress of individual financial institutions. Race to Zero did not respond to requests for comment.
Thomas Hale, a public policy professor at the University of Oxford and co-chair of Race to Zero’s expert peer review group, says the UN body did not have the capacity to be a “global police force” that helps the world sort “good” and “bad” net zero. “I’m glad the UN has created this much more robust system . . . but it will need to be backed up by standards and a whole ecosystem working together.”
A different world
The world has changed since last November and, in a time of escalating financial and energy crises, the need to fund the green transition has had to compete with the need to keep the lights on.
The energy crisis sparked by Russia’s invasion of Ukraine has “dented the idealism” of some of the worlds biggest financiers, says Huw van Steenis, a former senior adviser to Carney at the BoE.
US banks’ exposure to oil and gas increased in the first half of 2022 on the back of higher energy prices, while it fell at Canadian and European banks. “There’s a bit of ‘oh, we live in the real world, not the world we want it to be’,” Van Steenis says. “They have to look at some very complex trade-offs between energy security, energy affordability and environmentalism.”
Those trade-offs risk shifting the timeline of the alliance’s path to net zero, especially as it has focused on setting targets over ensuring they are delivered.
The German insurance company has cut back coverage of oil and gas projects but has not ruled out offering coverage for new gas pipelines, liquefied natural gas plants and gas-fired power plants
While just 8 out of 122 banks in Gfanz have set a 2030 emissions reduction target for the coal sector, 31 have set such a target for oil and gas, covering on average 80 per cent of their oil and gas portfolio, according to analysis published by Gfanz’s banking subgroup on Wednesday.
Close to a third are so-called intensity targets, which assess emissions only in relation to revenues, production or the size of portfolios. These targets are meant to incentivise investments in transition industries — like a steel company investing in hydrogen technology — but do not guarantee any change in real world emissions.
Targets expressed in absolute terms are less common, and stymied by gaps in disclosures and coverage — the asset manager Vanguard, a member of Gfanz, has only committed to manage 4 per cent of its assets under management in line with net zero goals.
Other targets are overly broad and open to interpretation. In the US, for example, Goldman Sachs’ target of $750bn by 2030 includes its advisory business — suggesting it could include the entire value of deals as long as these contribute to the bank’s core pillars of “climate transition and inclusive growth”. The bank declined to comment for this story.
The Canadian asset manager, where Carney is head of transition investing, recently raised a $15bn energy transition fund
Alliances such as Gfanz will only work if they introduce binding requirements to make sure they have an impact on real world emissions, says Jakob Thomä, co-founder of the 2 degree Investing Initiative think-tank.
He blames a reluctance by financiers to acknowledge the difficult decisions involved in transitioning away from fossil fuels, for example in the case of national governments’ exposure to oil and gas investments.
“If a bank comes out with general guidance on no new fossil fuels, and a smart-ass like me says: ‘Well that means no investment in US sovereigns [government debt] or UK bonds’, that’s a necessary translation,” he adds.
There are undoubtedly more trade-offs to come, as financial institutions wrestle with their obligations to investors, to governments, and to the planet. And nobody involved with Gfanz would dispute that there is much more to do.
Claire Perry, a former energy minister for the UK now at the World Business Council For Sustainable Development, credits the alliance with having already “unlocked chunks of capital into tricky parts of the transition”.
“There is a weird presumption that everything corporates do is a load of greenwash and what governments do is golden,” she says. “We need to be a little more nuanced in thinking about what needs to happen.”
Additional reporting by Camilla Hodgson
Climate Capital
Where climate change meets business, markets and politics. Explore the FT’s coverage here.
The Zacks SBIC & Commercial Finance industry will continue to bear the brunt of higher prepayments as interest rates rise. This will likely keep hurting the industry players’ profitability to some extent.
Yet, higher interest rates, favorable regulatory changes and decent economic growth are expected to keep supporting the industry in the coming days. Robust asset quality continues to act as a major tailwind. Hence, a few industry players like Ares Capital Corporation ARCC, Main Street Capital Corporation MAIN and Hercules Capital, Inc. HTGC are likely to gain from these favorable developments.
About the Industry
The Zacks SBIC & Commercial Finance industry comprises companies that provide finance to small and mid-sized privately-held developing firms. These firms are typically underserved by traditional banks and other lenders. Additionally, firms suffering from financial distress are the primary target clients of these lenders. The industry players provide customized financing solutions ranging from senior-debt instruments to equity capital. This financing is provided for change of ownership transactions, strategic buyouts, recapitalizations and growth initiatives in partnership with business owners, management teams and financial sponsors, among others. Some of the other products offered by the industry participants are mezzanine loans that typically pay high-interest rates and could be converted into equity in the target firm.
3 Major Factors Shaping the Future of SBIC & Commercial Finance Industry
Rising Rates: The Federal Reserve has been aggressively raising interest rates this year, and such moves are expected to continue in the coming days to control raging inflation numbers. While this has led to a spike in prepayments and refinancing before interest rates climb further, higher rates will benefit SBIC & Commercial Finance industry players. Also, given the decent economic growth, demand for products and services offered by these companies is likely to keep growing. Thus, the industry players are expected to witness a solid improvement in revenues going forward.
Solid Asset Quality: Following the coronavirus outbreak and subsequent halt in business activities in 2020, the majority of sectors wherein SBIC & Commercial Finance companies provide loans were hit hard. This raised fears of a deterioration of asset quality for industry players. Yet, support from the administration in the form of stimulus packages, extensive vaccination drives and re-opening of businesses continue to support economic growth. These are likely to prevent a substantial rise in delinquency rates for the industry players, though inflation remains a headwind.
Regulatory Changes: In 2018, an amendment to the Investment Company Act of 1940 by the Small Business Credit Availability Act eased the leverage limits for such companies, allowing them to increase their debt-to-equity leverage to 2:1 from 1:1. This helped these companies to reduce portfolio risk by investing in higher capital structures without foregoing current returns. In other words, the act provided extra funding flexibility to these companies and will continue offering more growth opportunities.
Zacks Industry Rank Indicates Brighter Prospects
The Zacks SBIC & Commercial Finance industry is a 36-stock group within the broader Zacks Finance sector. The industry currently carries a Zacks Industry Rank #14, which places it in the top 6{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} of more than 250 Zacks industries.
The group’s Zacks Industry Rank, which is basically the average of the Zacks Rank of all the member stocks, indicates outperformance in the near term. Our research shows that the top 50{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} of the Zacks-ranked industries outperform the bottom 50{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} by a factor of more than 2 to 1.
The industry’s positioning in the top 50{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} of the Zacks-ranked industries is a result of encouraging earnings outlook for the constituent companies in aggregate. Looking at the aggregate earnings estimate revisions, it appears that analysts are gradually gaining confidence in this group’s bottom-line growth potential. Over the past year, the industry’s earnings estimates for the current year have been revised 13.3{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} upward.
Hence, we are presenting a few stocks that are well-positioned to outperform the market based on a strong earnings outlook. Before that, let’s check out the industry’s recent stock market performance and valuation picture.
Industry Outperforms Sector and S&P 500
The Zacks SBIC & Commercial Finance industry has outperformed both the S&P 500 composite and its own sector over the past year.
While the stocks in this industry have collectively lost 11.5{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} over this period, the Zacks S&P 500 composite and Zacks Finance sector have declined 21.5{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} and 17.5{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b}, respectively.
One-Year Price Performance
Industry’s Current Valuation
One might get a good sense of the industry’s relative valuation by looking at its price-to-tangible book ratio (P/TBV), which is commonly used for valuing loan providers because of large variations in their earnings results from one quarter to the next.
The industry currently has a trailing 12-month P/TB of 0.82X. The highest level of 1.03X, lowest of 0.40X, and a median of 0.92X have been recorded by the industry over the past five years. Also, the industry is trading at a significant discount compared with the market at large, as is evident from the trailing 12-month P/TB for the S&P 500 composite of 9.79X, as the chart below shows.
Price-to-Tangible Book Ratio (TTM)
As finance stocks typically have a low P/TB ratio, comparing SBIC & commercial loan providers with the S&P 500 may not make sense to many investors. But a comparison of the group’s P/TB ratio with that of its broader sector ensures that the group is trading at a decent discount. The Zacks Finance sector’s trailing 12-month P/TB of 4.37X is also way above the Zacks SBIC & Commercial Finance industry’s ratio, as the chart below shows.
Price-to-Tangible Book Ratio (TTM)
3 SBIC & Commercial Finance Stocks to Invest
Ares Capital: This Zacks Rank #2 (Buy) stock is a specialty finance firm that primarily invests in U.S. middle-market companies (firms having annual earnings in the range of $10-$250 million). Based in Maryland, ARCC offers customized financing solutions, ranging from senior-debt instruments to equity capital, with a focus on senior secured debt. Its investments in corporate borrowers generally range from $30 million to $500 million while investment in power generation projects is between $10 million and $200 million.
As of Sep 30, 2022, Ares Capital had total investments (fair value) of $21.34 billion, total assets of $22.04 billion and a net asset value (NAV) of $18.56 per share.
Ares Capital has been witnessing growth in total investment income over the last few years. The company is expected to continue witnessing a rise in investment income in the quarters ahead, given the regulatory changes and rising demand for customized financing. Also, its investment commitments to new and existing portfolio companies have been steadily rising.
As of Sep 30, 2022, ARCC had a debt of $11.82 billion and cash and cash equivalents (including restricted cash) of $257 million. The company has a revolving credit facility, allowing it to borrow up to $4.3 billion at any time, with a maturity date of Mar 31, 2027.
In order to maintain its RIC status, Ares Capital distributes approximately 90{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} of its taxable income. In October 2022, it announced a dividend hike of 12{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b}, marking the third such increase this year. Also, it has a share repurchase program worth $500 million in place, which will expire on Feb 15, 2023.
ARCC has a market cap of $9.7 billion. Over the past 12 months, the company’s shares have lost 7.2{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b}. The Zacks Consensus Estimate for earnings has been revised 5.2{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} upward to $2.04 for 2022 over the past 30 days.
Price and Consensus: ARCC
Main Street Capital: This Zacks Rank #1 (Strong Buy) private equity firm specializes in providing equity capital to lower middle-market (LMM) companies. Main Street Capital also offers debt capital to middle-market companies. Based in Houston, TX, MAIN invests in LMM companies that generate annual revenues between $10 million and $150 million.
As of Sep 30, 2022, Main Street Capital had total investments (fair value) of $3.74 billion in 195 portfolio companies, which consisted of investments in the LMM portfolio, middle-market portfolio and private loan portfolio. As of the same date, MAIN’s NAV was $25.94 per share.
At the end of the September quarter, Main Street Capital had total liquidity of $420.2 million, which included $61.2 million in cash and cash equivalents and $359 million of unused capacity under its revolving credit facility. As of Sep 30, 2022, MAIN had total debt worth $1.48 billion, consisting of debentures and senior notes.
Since its October 2007 initial public offering (IPO), Main Street Capital has regularly raised its monthly dividends. Cumulatively dividends paid or declared since IPO through the third quarter of 2022 stand at $35.80 per share.
Main Street Capital has a market cap of $2.9 billion. Over the past 12 months, MAIN’s stock has declined 16.9{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b}. The Zacks Consensus Estimate for earnings has been revised 4.7{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} upward to $3.15 for 2022 over the past 30 days.
Price and Consensus: MAIN
Hercules Capital: Headquartered in Palo Alto, CA, HTGC is a specialty finance company that provides venture capital to technology and life science-related companies. Its investments are generally between $15.0 million and $40.0 million, and it expects these to generate revenues within at least two to four years.
Despite the tough macroeconomic scenario, Hercules Capital is expected to continue witnessing growing demand for customized financing from private equity firms and venture capitalists. The company maintains a robust balance sheet position.
As of Jun 30, 2022, it had $700.1 million in liquidity, including $57.1 million in unrestricted cash and cash equivalents and $643.4 million in credit facilities. Also, HTGC has long-term issuer ratings of BBB- and Baa3 from Fitch Ratings and Moody’s Investors Service, respectively, along with a stable outlook, which renders it favorable access to the debt market. At the end of the third quarter of 2022, the weighted average cost of debt, comprising interest and fees, was 4.4{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b}.
The fair value of Hercules Capital’s total investment portfolio was $2.83 billion as of Sep 30, 2022. NAV was $10.47 per share on the same date.
HTGC’s concentrated focus on its credit performance is encouraging. Driven by the rise in demand for customized financing and a robust deal pipeline, total new commitments are expected to keep increasing.
Hercules Capital’s capital deployment plan seems impressive. It announced a 2.9{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} hike in the quarterly distribution in October 2022, following hikes of 6.1{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} in July, 3.1{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} in October 2021 and 3.2{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} in May 2019. Management revisits its dividend policy at the end of every quarter and determines if any changes are required.
Hercules Capital has a market cap of $1.8 million. Shares of this Zacks Rank #1 company have declined 18.2{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} over the past year. The Zacks Consensus Estimate for 2022 earnings has been revised 5.9{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} north to $1.43 over the past month.
Price and Consensus: HTGC
Zacks Names “Single Best Pick to Double”
From thousands of stocks, 5 Zacks experts each have chosen their favorite to skyrocket +100{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} or more in months to come. From those 5, Director of Research Sheraz Mian hand-picks one to have the most explosive upside of all.
It’s a little-known chemical company that’s up 65{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} over last year, yet still dirt cheap. With unrelenting demand, soaring 2022 earnings estimates, and $1.5 billion for repurchasing shares, retail investors could jump in at any time.
This company could rival or surpass other recent Zacks’ Stocks Set to Double like Boston Beer Company which shot up +143.0{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} in little more than 9 months and NVIDIA which boomed +175.9{1668a97e7bfe6d80c144078b89af180f360665b4ea188e6054b2f93f7302966b} in one year.


 Why the Banking, Finance and Insurance plan industries must embrace digital brokers right before they’re left powering